
I’ve been watching the real-world asset space for a while now, and every so often something lands that actually feels different. This week it was FinChain teaming up with Plume. They’re launching FLEX & FINO, a leveraged yield strategy built around their FUSD token, and the headline number is hard to ignore: a projected annualized return of up to 7.2%. Not guaranteed, of course, but under baseline assumptions that already puts it in interesting territory for anyone sitting on tokenized Treasuries or looking for more than plain holding yield.
What Exactly Is FLEX & FINO?
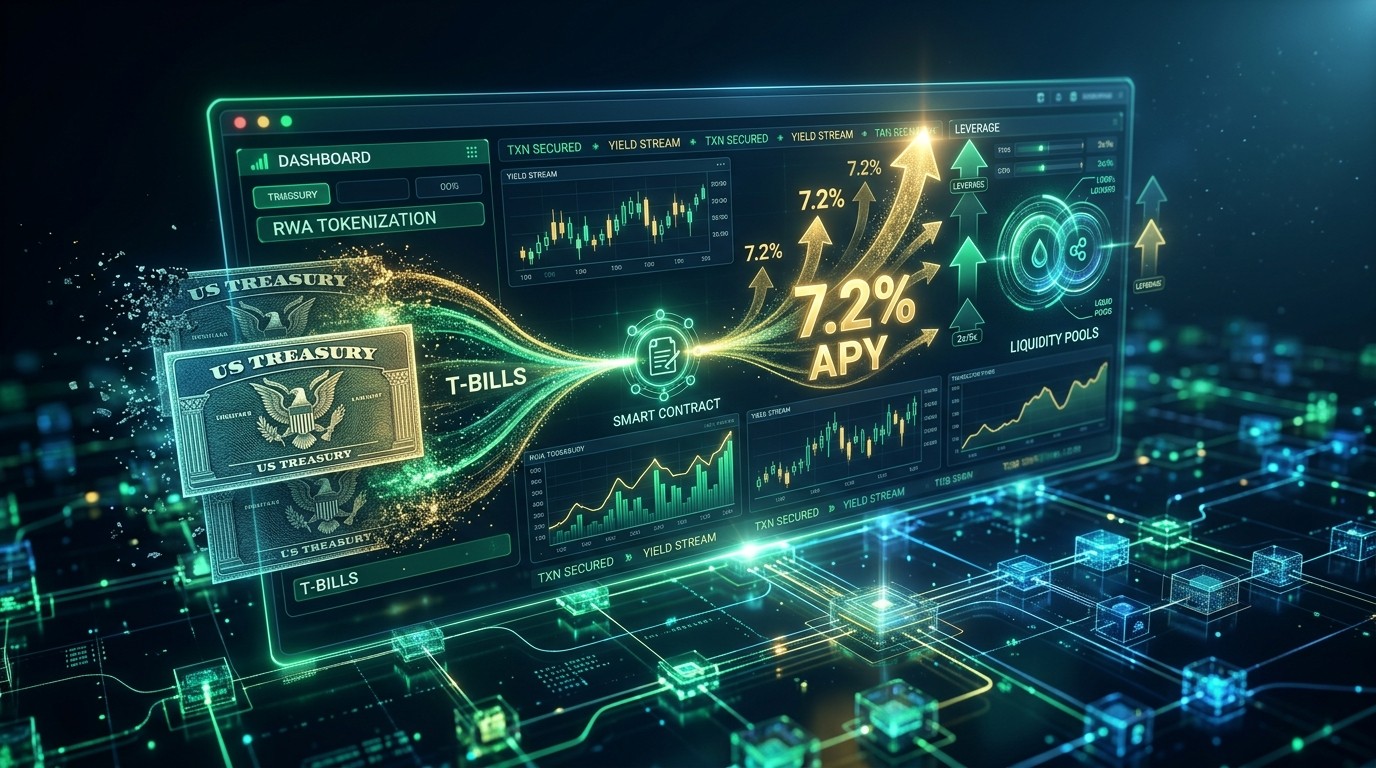
At its core, the product lets holders of FUSD put their tokens to work in a structured way. You deposit FUSD as collateral, borrow USDC against it, then deploy that borrowed stablecoin into on-chain liquidity pools. You keep earning the underlying yield from the Treasuries and money-market funds that back FUSD, and you pick up additional income from the pools. It’s leverage, plain and simple, but with a 90% utilization ceiling baked in so the strategy doesn’t run wild.
FUSD itself is an interest-bearing token. Reserves sit at least 100% collateralized and are held by designated custodians. The underlying assets are short-term U.S. Treasuries and money-market funds, which means the base yield comes from traditional fixed-income markets rather than pure crypto speculation. That part feels reassuring. The leveraged overlay is where things get more dynamic—and riskier.
How the Strategy Actually Works Day to Day
Participants start by depositing FUSD. While those tokens sit as collateral they continue generating their original yield. Next comes the borrow step: users take USDC loans against the FUSD position. That borrowed USDC goes straight into liquidity pools. The income from those pools becomes the second yield stream. Combine both streams, factor in borrowing costs, and under the assumptions FinChain used, the net figure can reach 7.2% annualized.
I’ve found that the real variable here is the cost of leverage. If borrowing rates stay reasonable and the pools perform as expected, the math works. If rates spike or pool returns soften, the net yield compresses quickly. That’s why the 90% utilization cap matters. It keeps the strategy from over-extending when markets get choppy.
Our partnership with Plume is not merely technical synergy. It is part of a broader push to bring institutional-grade asset management strategies onto blockchain rails.
That comment from FinChain’s leadership captures the intent. They’re not just tokenizing another Treasury product. They’re trying to turn the token into a usable building block inside DeFi strategies.
The Plume Angle and Why It Matters
Plume has spent the year focused on one thing: moving tokenized assets beyond simple issuance into products people can actually use. Earlier work included a tokenized vault linked to a major bond ETF and fixed-income offerings on a large exchange. The FinChain collaboration fits the same pattern. FLEX & FINO is the first product to emerge from the partnership, and total value locked will show up on Plume’s Partner Protocol and Nest Protocol after launch.
In my view the partnership is less about flashy marketing and more about infrastructure. Getting FUSD to work cleanly inside Plume’s environment required technical back-and-forth on strategy design, risk parameters, and settlement mechanics. Redemptions run on a T+2 cycle. Interest settlements stretch from T+14 to T+30. Those timelines are closer to traditional finance than the instant settlement most crypto natives expect, which may actually appeal to the institutional crowd FinChain is targeting.
Risk Controls and What Can Still Go Wrong
FinChain is clear that the 7.2% figure is a projection, not a promise. Actual returns will move with borrowing costs, pool performance, and broader market conditions. The 90% utilization limit is the main guardrail. Still, leveraged strategies always introduce risks that pure holding does not. Liquidity in the pools can dry up. Collateral values can shift. Borrowing rates can jump overnight.
Perhaps the most interesting aspect is how the company has tried to keep the underlying FUSD reserve picture unchanged. The leveraged activity sits on top of the existing 100% collateralization rather than altering it. That separation is intentional. It lets holders who simply want the base Treasury yield stay clear of the extra complexity, while those who want the enhanced return can opt in.
- Base yield continues from short-term Treasuries and money-market funds
- Additional income comes from deploying borrowed USDC into liquidity pools
- Utilization is capped at 90% to limit over-leverage
- Redemptions settle on a T+2 cycle
- Interest periods range from two to four weeks
KuCoin Integration Adds Another Layer
Alongside the Plume launch, FinChain completed an integration that lets FUSD participate in a staking mirror solution on a major exchange. That expands the token’s usefulness as institutional collateral. It’s a quiet but practical step. Tokenized assets only become truly liquid when they can move across venues and serve multiple purposes. The KuCoin arrangement is one more data point that FinChain is thinking about distribution, not just product design.
Looking ahead, the company says it plans more products built on tokenized traditional assets and further partnerships with exchanges and infrastructure providers. FLEX & FINO is presented as the first of several moves rather than a one-off experiment.
Putting the Numbers in Context
Seven point two percent is not a life-changing number in isolation. Compared with pure equity risk or high-volatility crypto strategies it looks modest. Compared with holding short-term Treasuries directly, or parking stablecoins in basic money-market products, it looks competitive—especially if the base FUSD yield is already in the mid-single digits and the leverage layer adds the rest.
The real question investors should ask is how stable that extra layer remains when rates move. I’ve seen plenty of yield products look great in calm markets and then struggle once volatility returns. The 90% cap and the institutional custodianship of reserves are positive signals, but they don’t eliminate market risk.
| Component | Source of Return | Key Risk |
| FUSD base yield | Short-term Treasuries & money-market funds | Interest-rate changes |
| Liquidity-pool income | Deployed borrowed USDC | Pool performance & fees |
| Net leveraged return | Combined streams minus borrow cost | Utilization & rate spikes |
Who This Product Seems Built For
FLEX & FINO is not aimed at the average retail trader chasing the next meme coin. The settlement cycles, the institutional language, and the focus on risk controls point toward more sophisticated participants—family offices, crypto-native funds, and perhaps traditional allocators who already understand fixed-income products and want on-chain exposure with a yield kicker.
That said, the barrier to entry is not as high as some structured products. Anyone holding FUSD can theoretically participate, provided they accept the leverage risk and the longer settlement windows. Whether that accessibility turns into meaningful adoption remains to be seen. FinChain has not disclosed an initial total value locked figure, which is understandable at launch but leaves the early scale question open.
The Bigger Picture for Tokenized Yield
What I find most useful about this launch is the direction of travel. For years the RWA conversation stayed stuck on issuance—how many billions of Treasuries or real estate could be tokenized. The harder and more valuable step is turning those tokens into active financial tools. Borrowing against them, deploying them into liquidity strategies, and composing them with other DeFi primitives is where the real utility appears.
Plume’s stated goal of moving from asset issuance to genuinely usable applications lines up with that shift. FinChain’s decision to start with a leveraged Treasury product rather than another static vault suggests they see the same opportunity. Whether 7.2% becomes a reliable long-term figure or simply a starting point will depend on execution, market conditions, and how carefully the risk parameters are managed once real capital starts flowing.
In the end, FLEX & FINO is a practical experiment in bringing traditional yield-enhancement techniques onto blockchain rails. The underlying assets are familiar. The leverage structure is familiar. The combination, delivered through a partnership focused on institutional-grade infrastructure, is what makes the announcement worth watching. Returns will vary. Risks are real. But the attempt to turn tokenized Treasuries into an active, yield-generating building block feels like a step the market has been waiting for.
Anyone considering the product should treat the 7.2% number as a reference point rather than a target, study the utilization rules carefully, and size positions according to their own risk tolerance. The machinery is in place. Now the market gets to test how well it runs.