
Have you noticed how quickly the conversation around artificial intelligence has shifted from software models to the physical machines that actually run them? I keep coming back to that thought whenever another major hardware player steps forward with ambitious targets. Right now one of the biggest electronics manufacturers on the planet is openly stating it wants half of the worldwide AI server market in just a couple of years. That kind of claim forces you to pause and look closer at what is really happening beneath the surface of the current technology boom.
Foxconn Pushes Toward Dominant Position In AI Servers
The company, long known for assembling consumer devices, has been steadily redirecting its focus. Its current share of the global AI server market sits near 40 percent. Leadership believes that figure can climb to roughly 45 percent next year and reach 50 percent within a couple of years. Those numbers are not casual projections. They come from a clear reading of order books that are already full for the next eighteen months at minimum.
In my view this is one of the more revealing signals about where real money is flowing. Model developers and large cloud providers continue to place heavy orders. Governments and traditional enterprises have still not fully entered the picture. That unfinished demand suggests the growth runway remains longer than many casual observers assume.
Production Capacity Fully Booked For Extended Period
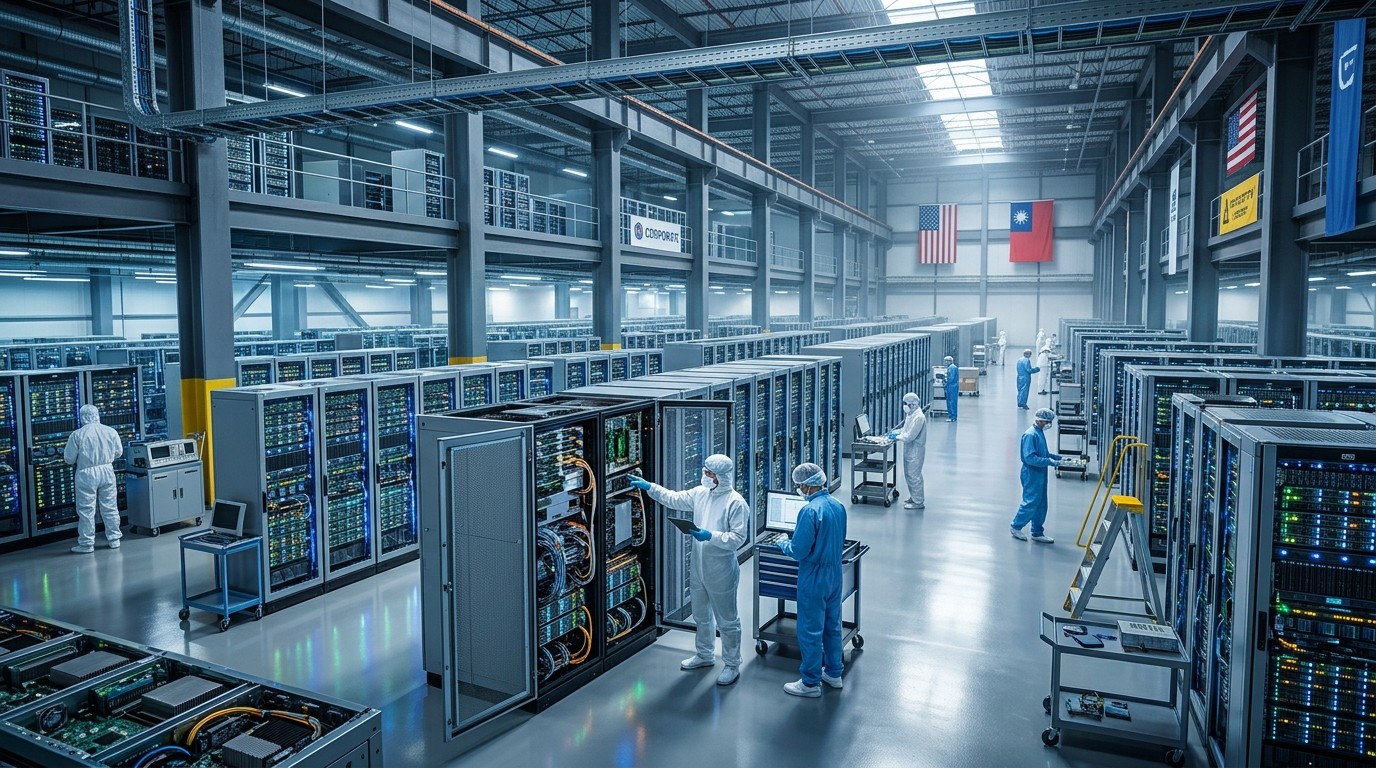
Factories are running at full tilt. Capacity is locked in for at least a year and a half. That reality leaves little room for sudden slowdowns in the near term. AI infrastructure is expected to generate more than 60 percent of total revenue within three to five years, once edge devices are set aside. The shift is structural rather than temporary.
I find it striking how quickly the revenue mix is changing. A business that once depended heavily on consumer electronics is now leaning hard into data center hardware. Server racks, high-density computing units, and related equipment are becoming the core. The transition feels deliberate and well measured.
Moving Upstream In The Supply Chain
Expansion plans in the United States form another important piece of the strategy. The company intends to move further upstream so it can respond faster to local demand. Higher costs in American facilities mean the initial focus stays on higher-margin products such as complete AI server racks and specialized data center gear.
Greater scale over time should help bring those costs down. That is the classic manufacturing logic, and it appears to be the path being followed. Serving the American market more directly also reduces certain logistical frictions that have grown more complicated in recent years.
What we are going to do is we are going to move up the supply chain.
That single statement captures the direction clearly. Instead of remaining a pure assembler, the organization wants deeper control over more stages of production. Vertical integration becomes both a competitive advantage and a risk management tool.
Careful Approach To Capital Spending
Even with strong order books, leadership keeps repeating a cautionary note. Overinvestment can destroy a company. Planned annual spending on AI related projects sits between three and five billion dollars, yet that figure could rise if vertical integration expands further. The message is consistent: growth must stay disciplined.
I have watched enough technology cycles to know that warning is worth taking seriously. When demand feels unstoppable, the temptation to build far ahead of actual needs becomes powerful. The current management tone suggests they are trying to avoid that classic trap.
If one major customer reduces spending, other customers can often fill the gap. An industry-wide pause, however, would create a much harder problem for the entire supply chain. That distinction matters. Diversification of the customer base provides some protection, but it is not absolute.
Why Demand Still Looks Robust
Most of the current volume comes from organizations training large models and operating massive cloud platforms. Enterprises and public sector buyers have only begun to explore full scale deployments. That lag creates a second wave of potential orders that has not yet arrived.
Perhaps the most interesting aspect is how uneven the adoption curve remains. Early movers have already locked in capacity. Later arrivals will face longer lead times and higher prices unless new factories come online quickly. The scarcity itself becomes a reinforcing factor for the companies that already hold strong positions.
- Model training clusters continue to expand rapidly
- Cloud service providers keep adding specialized AI instances
- Edge deployments are still in early stages
- Government and traditional enterprise projects remain underdeveloped
Each of those layers adds another potential source of future volume. The combination explains why production schedules look so full for such an extended period.
Implications For The Broader Technology Landscape
A single manufacturer aiming for half the global market naturally concentrates risk and opportunity in one place. Customers gain a highly capable partner with enormous scale. At the same time they become more dependent on that partner’s ability to execute. Competition among suppliers remains intense, yet the gap between the top tier and everyone else appears to be widening.
United States manufacturing expansion carries political and economic weight as well. Local production of critical infrastructure components reduces certain supply chain vulnerabilities. Higher labor and operating costs are the clear trade-off. Whether those costs can be offset through automation and volume remains an open question that will play out over the next several years.
I keep wondering how other established electronics firms will respond. Some will accelerate their own AI server programs. Others may choose to specialize in narrower segments. A few might exit the more capital intensive parts of the business altogether. The competitive map is being redrawn in real time.
Balancing Ambition With Prudence
The leadership message walks a careful line. Growth targets are aggressive. Capital discipline is repeatedly emphasized. That combination is harder to maintain than it sounds. When every competitor is racing to claim share, the pressure to overbuild becomes intense.
In my experience the companies that survive technology transitions are usually the ones that expand capacity slightly behind demand rather than far ahead of it. The current stance seems closer to that philosophy. Whether the organization can stick to it when orders keep pouring in will be one of the more important tests ahead.
Looking At The Revenue Transformation
Three to five years from now AI related infrastructure could represent 60 to 65 percent of total sales if current trends hold. That would represent a fundamental change in the business profile. Consumer electronics would still matter, yet the growth engine and the profit engine would sit elsewhere.
Such a shift also changes how the company is valued by the market. Hardware suppliers tied to secular technology waves often trade at different multiples than pure consumer electronics assemblers. The transition is already visible in the strategic language coming from the top.
Edge AI devices sit outside those core projections. Local inference hardware will grow as well, yet the company is treating it as a separate category for now. That separation helps keep the main infrastructure numbers cleaner and more focused.
Practical Challenges Of American Expansion
Building meaningful production capacity in the United States is never simple. Labor availability, permitting timelines, energy costs, and supplier ecosystems all differ from established Asian manufacturing hubs. The decision to start with higher margin products is a pragmatic response to those realities.
Over time the hope is that larger volumes will create economies of scale that offset the cost gap. Automation will almost certainly play a larger role than it does in lower cost regions. The exact mix of human labor and advanced robotics will evolve as facilities mature.
Customers based in North America stand to benefit from shorter lead times and reduced exposure to long distance logistics. Those advantages matter more when demand is rising quickly and every month of delay carries opportunity cost.
Customer Concentration And Risk Management
A handful of very large buyers currently drive most of the AI server volume. That concentration creates both opportunity and vulnerability. Strong relationships with the biggest spenders deliver visibility into future demand. They also mean that any change in spending plans at those organizations can ripple outward quickly.
The stated view is that weakness at one customer can usually be offset by strength at another. That works as long as the overall market keeps expanding. A synchronized slowdown across the major cloud and model training players would test the entire ecosystem at once.
Diversifying into government and enterprise projects over the coming years would reduce that concentration risk. Those segments tend to move more slowly, yet they also tend to be more stable once they commit.
The Role Of Vertical Integration
Controlling more stages of the value chain offers several advantages. Design decisions can be made faster. Quality issues can be addressed earlier. Margins can improve when intermediate markups disappear. The trade-off is higher capital intensity and greater operational complexity.
Leadership has signaled willingness to increase spending beyond the baseline range if deeper integration makes strategic sense. That flexibility is useful, provided the additional investment is tied to clear customer demand rather than speculative capacity.
I have seen vertical integration strategies succeed and fail in equal measure across different industries. Success usually depends on maintaining clear visibility into end demand and refusing to build inventory that has no near term home.
What Sustained Demand Really Means
When production lines are booked eighteen months out, the practical effect is that new customers face long waits or must pay premiums for priority access. That dynamic tends to favor incumbents who already hold capacity. It also encourages some buyers to place larger orders earlier than they otherwise might, simply to secure supply.
The risk of double ordering exists in every tight market. If several large customers have placed overlapping reservations, eventual cancellations or delays could free up capacity faster than currently expected. Monitoring order quality therefore becomes as important as monitoring order quantity.
So far the signals remain constructive. Demand from the core AI training and inference community continues to look solid. The second wave of enterprise and public sector adoption has not yet fully arrived, which leaves additional upside if that wave materializes on schedule.
Longer Term Industry Structure
If one manufacturer approaches 50 percent global share, the competitive landscape becomes more polarized. A small number of large players will handle the bulk of high volume production. Smaller specialists may thrive in niche configurations or rapid prototyping, yet the mainstream volume business will concentrate further.
That concentration can drive efficiency and standardization. It can also reduce the diversity of supply options available to customers. Buyers will need to decide how much concentration risk they are willing to accept in exchange for scale advantages and technical capability.
New entrants face high barriers. Capital requirements are substantial. Existing relationships and process know-how take years to replicate. The window for meaningful share gains by outsiders appears to be narrowing rather than widening.
Human Judgment Inside The Numbers
Behind every capacity plan and market share target sit human decisions about risk tolerance. The repeated emphasis on avoiding overinvestment reveals an awareness of past industry cycles. Memory of previous boom and bust patterns in electronics manufacturing still influences current thinking.
That institutional memory is valuable. Technology markets have a habit of overshooting in both directions. The companies that navigate those swings most successfully tend to be the ones that keep their balance sheets and their factory footprints somewhat conservative even when demand feels endless.
Whether the present leadership can maintain that discipline while pursuing aggressive share gains will be one of the more interesting stories to watch over the next few years. Ambition and caution rarely sit comfortably together for long.
Practical Takeaways For Observers
Several points stand out clearly. First, the physical infrastructure layer of artificial intelligence remains supply constrained. Second, the largest manufacturers are responding by expanding capacity and moving closer to key end markets. Third, capital discipline is being treated as a strategic priority rather than an afterthought.
Those three observations together paint a picture of an industry that is still early in its infrastructure build out phase. The software side of AI receives most of the public attention. The hardware side is where the more immediate bottlenecks and opportunities currently reside.
- Capacity remains tight for the next eighteen months at least
- Market share concentration among top suppliers is likely to increase
- United States production will grow but start with higher margin products
- Overinvestment risk is acknowledged at the highest levels
- Enterprise and government demand has yet to fully materialize
Each of those points carries implications for customers, competitors, and investors who follow the sector. The next couple of years will show whether the 50 percent target proves realistic and whether the caution around capital spending holds under continued pressure to grow.
Final Thoughts On The Road Ahead
The scale of ambition on display is hard to ignore. Claiming half the global market for AI servers is not a minor adjustment. It is a declaration of intent to become the dominant industrial backbone of the current technology wave.
At the same time the repeated warnings about overinvestment provide a useful counterweight. Growth without discipline has ended badly for many manufacturers in earlier cycles. The ability to hold both ideas in mind at once may prove to be the real competitive advantage.
I will be watching the actual capacity additions, the mix of products coming out of American facilities, and the evolution of the customer base. Those concrete details will tell us more than any single market share projection. The infrastructure phase of artificial intelligence is still young. How the leading manufacturers navigate the next few years will shape the cost, availability, and reliability of computing power for a long time to come.
The story is far from finished. Order books are full, expansion plans are moving forward, and the tension between aggressive growth and careful spending remains unresolved. That combination alone makes the coming period worth close attention.