
Watching the numbers flash across the screen early Monday morning, I could not help thinking how quickly calm can turn into caution. French government bond yields jumped, the euro lost ground against both the dollar and the pound, and Paris-listed shares opened lower. What looked like another weekend of street demonstrations suddenly carried real weight for anyone holding French assets.
Why Markets Reacted So Sharply To The Latest Unrest
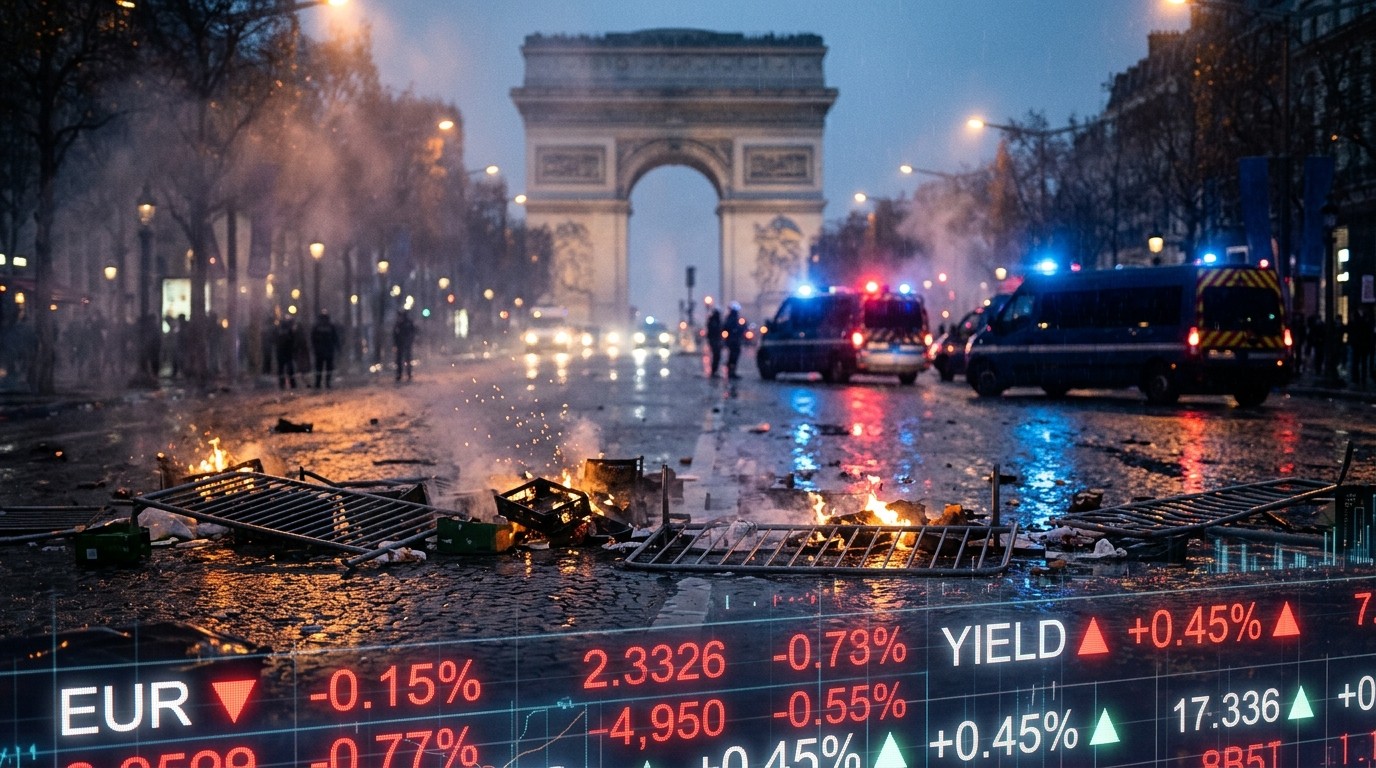
Hundreds of thousands of people took to the streets across the country over the weekend. The marches focused on political paralysis, the cost of living, and the quality of public services such as schools and healthcare. In several cities the gatherings turned chaotic. Cars and buildings were set alight, clashes with police left more than two thousand people under arrest, and the images traveled fast.
Investors did not need those pictures to feel uneasy. France already carries a heavy public debt load and a deficit that refuses to shrink at the pace many in the markets would like. The weekend events simply reminded everyone how fragile the political backdrop remains. The ten-year French government bond yield rose seven basis points. Two-year and thirty-year yields also moved higher, though by smaller amounts. Higher yields mean higher borrowing costs for the state, and that is never a comfortable message.
The euro slipped roughly 0.15 percent against the dollar and a similar amount against the pound. The CAC 40 index lost close to one percent in early trading. None of these moves were dramatic on their own, yet together they painted a clear picture of caution. I have watched these patterns before. When political noise meets fiscal stress, French assets tend to feel the pressure first and recover only when a credible path forward appears.
The OAT-Bund Spread And Why It Matters
Perhaps the most closely watched indicator sits in the difference between French and German bond yields. That premium, often called the OAT-Bund spread, climbed toward levels last seen during the euro-area debt crisis of the early 2010s. When the extra yield France must pay over Germany widens, it signals that investors are demanding greater compensation for perceived risk.
Why does this matter beyond the bond market itself? A wider spread raises the cost of capital for French companies. It also feeds concerns about possible higher taxes or tighter regulation down the road. Banks, which remain sensitive to sovereign risk, often feel the effect quickly. Even though only a modest share of CAC 40 revenues comes from the domestic economy, the index has lagged many of its European peers for years. Part of that underperformance traces back to repeated episodes of political uncertainty.
In my view the spread acts like a daily referendum on confidence. When it stays elevated, it keeps a lid on how far equity valuations can expand. When it narrows, the relief can be swift. Right now the market is telling us that confidence remains fragile.
Budget Uncertainty And The Minority Government Challenge
At the heart of the current nervousness sits the 2027 budget. The minority government led by Prime Minister Sébastien Lecornu must still navigate the parliamentary process. Budget talks have already toppled two previous prime ministers in recent years. That history alone keeps investors on edge.
Analysts keep stressing the same point: lenders want to see a clear program of fiscal consolidation. France’s deficit-to-GDP ratio stays stubbornly high while economic growth remains modest. Without either lower spending or higher revenue, the debt trajectory looks uncomfortable. One senior strategist noted that taxes could well rise for businesses and that broader tax increases cannot be ruled out. Those words land heavily in a country where the tax burden is already among the highest in Europe.
It will be difficult to see the budget deficit come down without painful measures. Fiscal consolidation means you need to either spend less or tax more. Those things are very tricky.
The political calendar adds another layer. The next presidential election is approaching, and polls currently favor a candidate from the far right. Markets hate uncertainty about future policy direction. Even if a “golden budget rule” has been mentioned in campaign talk, the lack of detailed plans leaves many fund managers skeptical that meaningful deficit reduction will arrive soon.
How Luxury Stocks And Broader Sentiment Fit In
French luxury names face a double headwind. Domestic political noise is one problem. A broader slowdown in high-end consumer spending in China is another. When both pressures hit at the same time, share prices tend to lag. I have noticed that global investors often use French luxury stocks as a barometer for risk appetite toward the entire French market. When those names underperform, the rest of the index usually feels the chill.
Risk perception of French assets has clearly shifted higher. International buyers of government bonds already demanded higher yields earlier this year, pushing the ten-year rate to its highest level since 2002. The latest unrest makes those buyers even more cautious. Comfort is hard to find when headlines mix street clashes with questions about fiscal credibility.
Could The European Central Bank Step In?
Talk of emergency tools naturally surfaces whenever spreads widen. The Transmission Protection Instrument exists precisely for moments when market dysfunction threatens the transmission of monetary policy. Yet most observers do not see current conditions as severe enough to trigger that mechanism.
The central bank prefers to keep such tools in reserve. Using them would likely come with strict conditions and a demand for even tougher fiscal reforms over a long period. History shows that countries which received support during the last sovereign debt crisis had to accept years of difficult adjustment. France is much larger, and the political sensitivity around any external oversight would be intense.
Still, the possibility cannot be dismissed entirely. If spreads begin to disrupt liquidity or if selling pressure intensifies, the conversation would change quickly. For now the market is applying pressure in its own way. Sometimes that pressure is exactly what forces governments to confront hard choices.
What History Teaches About French Market Episodes
This is not the first time French assets have faced a confidence test. Looking back over the past decade and a half, several periods of political turbulence produced similar patterns: rising yields, a softer euro, and equity underperformance. In most cases the reaction proved temporary once a clearer policy path emerged. The difference this time lies in the starting point. Debt levels are higher, growth is softer, and the political landscape appears more fragmented than before.
I keep returning to one simple observation. Markets can tolerate high debt if they believe the government has both the will and the ability to stabilize it. When that belief weakens, the cost of funding rises almost automatically. France still benefits from deep domestic savings and a large investor base that prefers home assets. Those factors provide a cushion. They do not, however, eliminate the need for credible medium-term plans.
Practical Implications For Investors Right Now
Anyone holding French government bonds is already seeing mark-to-market pressure from higher yields. Equity investors in banks and domestically focused companies feel the same caution. Global investors with broader European exposure are watching the OAT-Bund spread as a daily signal of regional risk appetite.
Several practical points stand out:
- Duration risk in French fixed income remains elevated while political headlines stay noisy.
- Bank shares often act as a leveraged play on sovereign confidence and deserve close monitoring.
- Currency exposure to the euro carries an extra layer of French-specific political risk at the moment.
- Any concrete progress on the budget could reverse some of the recent yield increases surprisingly quickly.
None of this means French assets should be abandoned. It does mean position sizing and risk management matter more than usual. I have found that periods of elevated political noise often create opportunities later, once the worst fears fade. Timing those moments is never easy, but understanding the underlying drivers helps.
The Broader European Context
France does not exist in isolation. Other large European economies face their own fiscal challenges. Yet the size of the French economy and its role inside the euro area give its problems special weight. A prolonged rise in French borrowing costs would eventually feed into wider market conditions. That is why the current episode draws attention far beyond Paris.
Some observers have even floated the uncomfortable idea that France could become “too big to save” in a hypothetical extreme scenario. While that language feels exaggerated today, it underlines how important a return to fiscal discipline remains. The European framework for fiscal rules has evolved, but political will inside each country still decides whether those rules produce results.
Looking Ahead To The Coming Weeks
The immediate focus stays on the budget negotiations. Any sign that a workable compromise is taking shape would likely ease some of the pressure on yields. Conversely, further delays or political accidents could keep the OAT-Bund spread elevated. Street protests may continue, yet markets usually care more about institutional outcomes than daily images of unrest.
Investors will also watch economic data for clues about growth and inflation. Soft growth makes deficit reduction harder. Sticky inflation would complicate the European Central Bank’s room for maneuver. The interplay between politics, growth, and monetary policy will shape the next chapter.
In my experience these episodes rarely resolve in a straight line. Progress often comes in fits and starts. The key is whether the overall direction eventually points toward greater fiscal credibility. Until that becomes clearer, French assets are likely to trade with a risk premium attached.
A Personal Note On Navigating Uncertainty
I have covered enough market storms to know that the loudest headlines rarely last forever. What lasts is the underlying arithmetic of debt, growth, and political capacity. France still possesses significant strengths: a diversified economy, strong institutions, and a history of eventual adaptation. Those strengths can reassert themselves once the current political fog lifts.
For the moment the message from the bond market is straightforward. Investors want to see a plan they can believe in. Higher yields and a softer euro are simply the market’s way of saying the plan is not yet convincing enough. How quickly that changes will determine whether this week’s moves prove temporary or the start of a longer adjustment.
The coming months will test both the government’s ability to pass a credible budget and the market’s patience. I will be watching the spread, the euro, and the tone of budget discussions closely. Those three signals usually tell the real story long before the next set of protest images appears.
Key Takeaways For Market Participants
Let me try to distill the situation into a few clear points that matter for anyone managing money or simply trying to understand the noise.
- Political unrest has reinforced existing worries about France’s fiscal path rather than creating an entirely new problem.
- The OAT-Bund spread remains the single most useful real-time gauge of investor confidence.
- Budget negotiations carry high stakes because previous attempts have already cost two prime ministers their jobs.
- Luxury and banking stocks tend to amplify the broader French risk premium.
- Central bank intervention is not the base case, yet the tools exist if market functioning deteriorates.
None of these points is particularly new. What feels different is the combination of elevated debt, a minority government, an approaching presidential contest, and visible public discontent. That mix keeps risk premiums higher than they would otherwise be.
Markets can live with political drama. They struggle more with the absence of a believable medium-term fiscal story. Until that story becomes clearer, French assets are likely to remain more volatile than those of their more fiscally stable neighbors. The weekend protests simply reminded everyone of that reality in vivid fashion.
The weeks ahead will show whether the pressure produces constructive policy movement or further delay. Either outcome will leave its mark on yields, the euro, and equity valuations. For now the direction of travel still leans toward caution, and that is exactly how the market is pricing the situation.