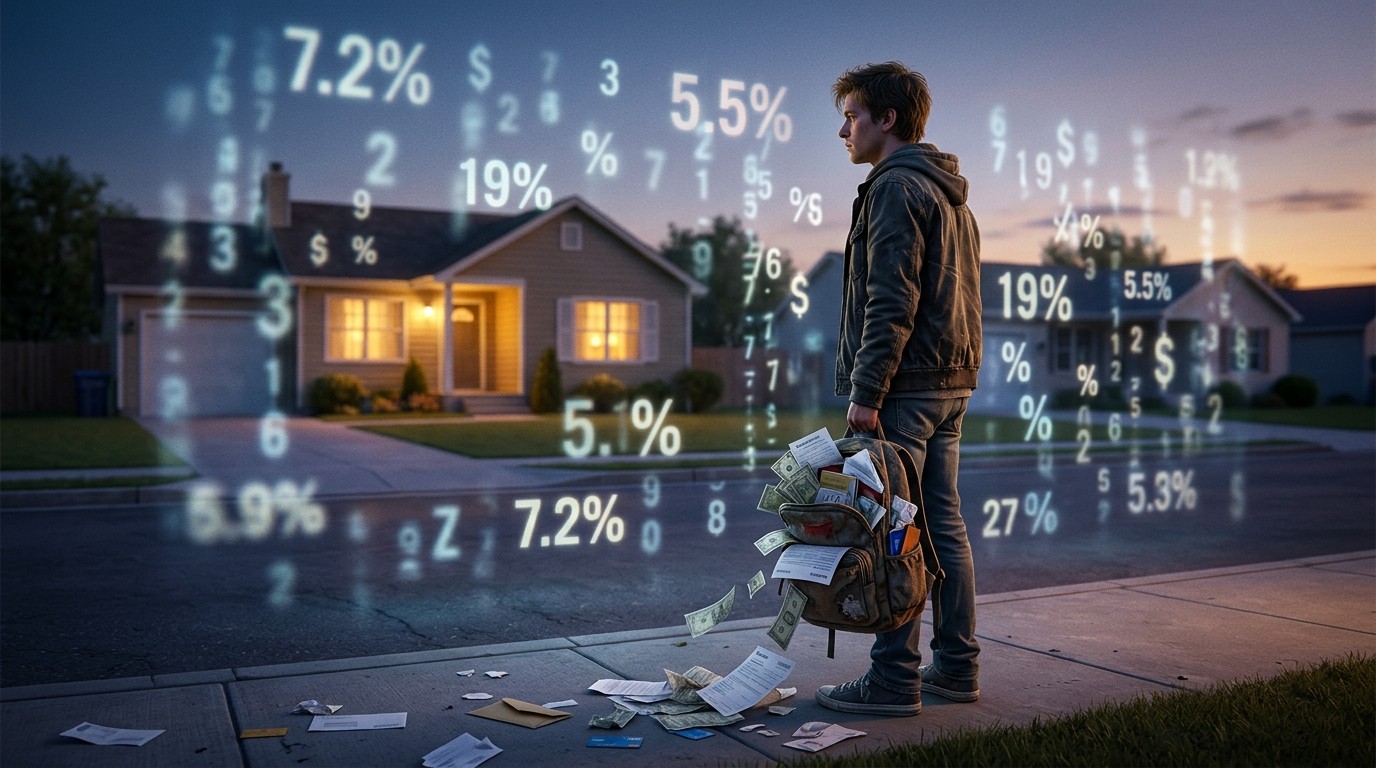

Almost four in ten people in their late teens and twenties say the weight of what they owe is the main reason they cannot save for a house or even start looking. That number landed harder than I expected when I first saw it. It is not just a statistic. It feels like a quiet shift in how an entire generation approaches the idea of putting down roots.
Why Debt Hits Gen Z Harder Than Earlier Groups
Debt has always shaped choices, yet the version facing people between 18 and 29 carries a different texture. Nearly half of them report that their total balances grew over the past year, more than any other age group in the same survey of adults who carried debt recently. Close to six out of ten also describe frequent or constant stress about money obligations. Those figures sit against a backdrop of higher relative housing costs and student loan totals that have climbed in proportion to income for many.
Starting adult life often means covering setup expenses while still climbing the earnings ladder. Rent, transportation, basic furniture, and the leftovers from education all stack at once. I have watched friends in this age range juggle exactly that combination and still feel behind. The math is simply tighter when mortgage rates sit well above the historic lows that locked many older homeowners into cheaper payments.
One financial education advisor put it plainly: the pressures are stacked against you in your twenties. Startup costs arrive before peak earning years. Student loan balances have grown proportionally. Mortgage rates on a relative basis are much higher. Plenty of people still sit in homes financed at three percent while current rates hover above seven. That gap is pure arithmetic, not attitude.
The Emotional Side of Carrying Balances
Optimism about paying everything off remains low. Fewer than three in ten in this age range feel confident they will clear their debt. That sense of stuckness can quietly shape decisions far beyond money. It influences whether someone feels ready for bigger commitments, including the practical steps toward owning a place.
I have found that the stress itself becomes its own obstacle. When obligations feel constant, the mental energy needed to plan a budget or research options gets drained. People cut back where they can, yet the overall load still grows. In the same survey, more than half said they reduced spending on eating out, and over forty percent spent less on clothing and personal care. Those cuts help at the margins, but they rarely reverse the broader trend alone.
Rethinking the Homeownership Path
For a long time, buying a house stood as a clear marker of financial progress. That view still holds power, yet it may not fit every situation right now. Renting can offer flexibility that ownership does not, especially when debt already limits cash flow. The key is treating the choice as deliberate rather than a default failure.
One practical approach is to calculate what a mortgage payment plus related costs would look like today, then redirect a realistic portion of that amount into investments or high-yield savings instead. Over time that habit can build a different kind of security. It is perfectly acceptable to change direction later. Goals evolve. What matters is identifying what you actually want rather than measuring against someone else’s timeline.
The important thing is to help people identify what they want and not worry so much about what other people say. And by the way, it is okay to change your mind.
That perspective removes some of the shame that often travels with debt conversations. Shame rarely improves decision-making. Clarity does.
Building a Clearer Picture of Your Money
A budget does not have to feel like deprivation. Think of it more as a map. Once you see where the money actually goes each month, choices become clearer. Some people discover small leaks that add up. Others realize certain categories matter more than they thought and decide to protect them while trimming elsewhere.
Tracking for even one full month often surprises people. Subscription services, impulse deliveries, and automatic renewals tend to hide in plain sight. After that first look, you can decide what stays and what goes without guessing. The process itself reduces the fog that keeps stress high.
In my experience, the most useful budgets stay simple enough to revisit without dread. Complicated spreadsheets get abandoned. A short list of categories and actual numbers works better for most. Adjust as life changes. The goal is awareness, not perfection.
Guarding Against Lifestyle Creep
Social platforms make polished versions of other people’s lives easy to see. That visibility can create quiet pressure to match a certain standard of living, even when the images show rented or staged moments. The gap between what appears and what is affordable widens faster than many realize.
Resisting that pull takes deliberate practice. One useful habit is pausing before any non-essential purchase and asking whether it moves a longer-term goal forward or simply fills a short-term feeling. The answer is often obvious once the question is asked out loud. Over time the pause becomes automatic.
I have noticed that people who keep a short written list of their actual priorities find it easier to say no. The list does not need to be formal. Three or four sentences on a phone note can be enough. When a tempting expense appears, the list provides a quick filter.
Two Proven Ways to Attack Balances
When minimum payments are manageable, two structured approaches stand out. The avalanche method focuses extra money on the highest interest rate first while keeping every other account current. Once that balance reaches zero, the freed payment rolls to the next highest rate. Mathematically this path usually costs less in interest and shortens the overall timeline.
The snowball method takes the opposite order. Extra funds go toward the smallest balance first. Early wins arrive faster, and those visible progress points help many people stay motivated through the longer middle stretch. The trade-off is slightly higher total interest and a bit more time. For some, the psychological boost outweighs the pure numbers.
Neither method is wrong. The better choice depends on whether motivation or pure efficiency feels more important in your specific situation. Plenty of people start with snowball to build momentum and switch later. The only requirement is consistency once a method is chosen.
- List every balance, interest rate, and minimum payment in one place
- Decide whether early wins or lowest total cost matter more right now
- Automate the minimums so nothing falls behind
- Direct every extra dollar to the chosen target account
- Celebrate each zero balance without restarting lifestyle spending
When Consolidation Makes Sense
A single loan that replaces several higher-rate balances can simplify payments and lower the overall interest rate. Some lenders even handle the payoff process directly with the original creditors. The new payment arrives once a month at a fixed rate, which removes the juggling act.
Qualification usually depends on credit history, income stability, and the total amount requested. Rates and terms vary widely. Looking at the full cost over the life of the loan, not just the monthly number, prevents surprises. A lower payment that stretches far longer can cost more in the end.
This route works best when the new rate is meaningfully lower and the borrower commits to not running up the old cards again. Closing or freezing those accounts after transfer often helps. Without that discipline the problem simply resets under a new name.
Considering Settlement When Payments Feel Impossible
Sometimes the monthly minimums themselves have become unreachable. In those cases a settlement approach can reduce the total owed on unsecured balances such as credit cards and personal loans. Secured debts like mortgages or auto loans generally cannot be included.
Companies that handle these negotiations typically charge a fee based on a percentage of the enrolled amount, often in the range of fifteen to twenty-five percent depending on location and the final outcome. Clients who complete a program frequently see their eligible monthly obligations drop by around forty percent. The process is not instant and requires careful attention to credit impact and tax considerations.
This path is rarely the first choice. It tends to suit situations where the alternative is prolonged default. Working with a reputable organization that explains every step in plain language reduces the chance of unpleasant surprises later.
Small Habits That Compound Over Time
Progress rarely arrives in dramatic leaps. More often it shows up as a series of quiet decisions repeated week after week. Automating a small transfer into savings the same day as a paycheck removes the decision fatigue. Rounding up purchases and sweeping the difference into a separate account creates another gentle flow.
Reviewing statements once a month without judgment keeps awareness high. Looking for patterns rather than individual mistakes turns the exercise into useful information instead of self-criticism. Over several months those patterns usually reveal one or two high-impact adjustments that free meaningful cash.
Perhaps the most interesting aspect is how quickly mental bandwidth returns once a few balances start moving downward. Decisions that once felt overwhelming become ordinary again. That shift alone can change the trajectory more than any single technique.
Balancing Present Needs and Future Goals
It is easy to swing between extremes. Some people slash every discretionary expense and burn out. Others decide the situation is hopeless and stop trying. A middle path that protects a modest amount of enjoyment while still directing surplus toward debt or savings tends to last longer.
One practical test is to ask whether a given expense buys temporary relief or lasting improvement. A meal with friends after a hard week can restore energy that makes the next workday more productive. A subscription that goes unused month after month usually fails that test. The distinction is personal and shifts over time.
I have seen people succeed by treating debt reduction as one important goal among several rather than the only goal. Room for rest, relationships, and occasional small pleasures keeps the larger plan sustainable. Burnout helps no one reach zero balances faster.
Practical First Steps Anyone Can Take This Week
Gather every statement or app balance into a single list. Write down the current amount, the interest rate if known, and the minimum due. Seeing the full picture on one page often reduces the vague dread that accompanies scattered accounts.
Next, open the budgeting tool or simple spreadsheet you already have and enter the last thirty days of actual spending. No need for categories yet. Just the total outflow. That number alone can clarify how much room exists for extra payments.
Choose one method, avalanche or snowball, and set an automatic extra payment for the chosen account. Even a modest amount begins the process. Momentum builds from action, not from waiting for perfect conditions.
- Create a complete list of current balances and rates
- Track actual spending for one full month
- Select either the highest-rate or lowest-balance target
- Automate the extra payment on payday
- Review progress every four weeks and adjust if needed
When Professional Guidance Adds Value
Some situations benefit from an outside perspective. A neutral advisor can spot options that feel invisible when stress is high. The conversation itself often lowers the emotional temperature enough to make clearer choices possible.
Look for someone who explains fees, timelines, and likely outcomes in straightforward language before any commitment. Questions about average results, common obstacles, and what happens if circumstances change are fair and useful. Transparency at the start prevents frustration later.
Not every person needs formal help. Many make solid progress with free tools and consistent habits. The decision depends on the complexity of the balances and the amount of mental energy available. There is no universal rule, only the specific mix of numbers and capacity in front of you.
Looking Ahead Without Constant Pressure
Homeownership remains a meaningful goal for many, yet it does not have to define every decision in the meantime. Building savings, reducing high-interest balances, and protecting a basic emergency cushion create options that did not exist before. Those options matter whether the next step is a down payment or continued renting with stronger financial footing.
The generation currently in their twenties faces a tougher starting line in some respects. Higher relative education costs and elevated borrowing rates for housing form real constraints. At the same time, tools for tracking, automating, and negotiating have never been more accessible. Using them steadily tends to produce results that surprise even the people doing the work.
Progress rarely looks dramatic from the inside. Month to month the numbers move slowly. Then one day a balance hits zero, or a savings account reaches a level that once felt distant. Those moments accumulate. They change the range of possible next moves.
Debt does not have to remain the dominant feature of early adulthood. With a clear view of the numbers, a chosen repayment approach, and permission to adjust the larger timeline, the weight begins to lift. The path is rarely linear. It is still walkable.
Take the next small action this week. List the balances. Track the spending. Send one extra payment. Those steps are ordinary and powerful at the same time. Over months they rewrite the story that currently feels stuck. The house, the freedom, or whatever goal sits further down the road becomes more reachable with each quiet decision that moves the numbers in the right direction.
Financial pressure in the twenties is common and often temporary when addressed with steady attention. The nearly forty percent figure that opens this discussion does not have to become a permanent barrier. It can instead serve as a signal to examine the load, choose practical tools, and begin shifting the balance one payment at a time. That shift is already underway for many. It can begin for anyone willing to start with the numbers in front of them today.