
I still remember the afternoon a close friend called me, voice tight with stress, after her father died without leaving clear instructions. The bank accounts were frozen, the pension nomination was years out of date, and nobody knew whether he wanted to be buried or cremated. What should have been a time of quiet grief turned into weeks of detective work and family tension. That experience stuck with me. Getting your finances in order before you die is not morbid. It is one of the most considerate things you can do for the people you care about.
The good news is that the process does not have to be complicated or expensive. A few deliberate steps taken while you are still healthy can prevent years of administrative headaches and unexpected tax bills. In this guide I will walk through the practical actions that actually matter, based on what financial planners and families deal with every day.
Why Sorting Your Affairs Early Makes a Real Difference
Most of us assume we have plenty of time. Then life intervenes. A sudden illness or accident leaves loved ones scrambling through drawers and email inboxes trying to piece together a financial picture that only you fully understood. The emotional cost is high. So is the financial one. Without clear directions, assets can be distributed in ways you never intended, and the taxman may take a larger share than necessary.
I have seen families spend months arguing over jewellery or who should receive a modest savings account simply because nothing was written down. The opposite is also true. When someone leaves a clear will, updated pension forms and a simple fact file, the process becomes calmer and faster. Executors can act with confidence instead of guesswork.
Perhaps the most interesting aspect is how much peace of mind the process gives the person doing the planning. Once the paperwork is sorted, many people report a quiet sense of relief. They know their wishes are recorded and their family will not be left in the dark.
Start With a Legally Valid Will
Writing a will is the foundation of everything else. Without one, the law decides who inherits your property, money and personal belongings. Those rules often surprise people. An unmarried partner may receive nothing. Children from a previous relationship might be overlooked. Charities you supported for years receive no gift.
A proper will lets you state exactly how you want your estate divided. You can name guardians for children under eighteen, appoint an executor you trust, and leave specific items to particular people. Jewellery, family heirlooms or even a favourite watch can be directed to the person who will value them most.
You do not always need a solicitor, but if your situation involves a blended family, property abroad or complicated assets, professional advice is worth the cost. The will must be signed and witnessed correctly to be valid. Store it somewhere safe and tell your executor or a trusted relative where to find it. Review the document every few years or after major life events such as marriage, divorce or the birth of a grandchild.
The first thing is for people to get comfortable with the idea of having those conversations. Going in, you need to understand that your children will have opinions but that is okay because the final decision is still yours.
Those early conversations matter more than most people realise. Talking openly about your plans reduces the chance of hurt feelings later. It also gives you useful feedback. Sometimes adult children have practical reasons for preferring certain arrangements.
Update Your Pension Beneficiaries Properly
Here is a detail many people miss. You cannot leave your pension in your will. The money follows the nomination form you completed with the pension provider. That form, often called an expression of wish or nomination of beneficiary, is the document that matters.
Most schemes operate under discretion. The trustees look at your form as strong guidance, but they can choose differently if circumstances have clearly changed. A minority of schemes pay exactly according to the form, known as direction. In those cases an outdated nomination can send money to an ex-partner or someone you no longer wish to benefit.
I always recommend reviewing these forms whenever you review your will. Marriage, divorce, the death of a beneficiary or the birth of a new family member should all trigger an update. Keep a note of every pension scheme you belong to and the date you last checked the nomination.
Annuities need separate attention. A single-life annuity usually stops when you die. A joint-life version continues paying a surviving partner, though the amount may reduce. Check the exact terms before you buy or if you already hold one.
Plan Ahead for Inheritance Tax
In the UK, inheritance tax applies when an estate exceeds the available allowances and is left to someone other than a spouse or civil partner. The basic nil-rate band sits at £325,000. An additional residence nil-rate band of £175,000 can apply when you leave your home to direct descendants, bringing the total to £500,000 for many people. Anything above the threshold is taxed at 40 percent, or 36 percent if you leave at least 10 percent of the net estate to charity.
The simplest and often most effective strategy is lifetime gifting. Under the seven-year rule, gifts made more than seven years before death fall outside the estate for inheritance tax purposes. Smaller annual allowances also exist that can be used every year without starting the seven-year clock.
Financial planners often point out that many people overcomplicate the process. Trusts have their place, especially with blended families or when you want to retain some control over timing. For most households, however, a straightforward conversation with adult children about gifting while you are still alive achieves more than complex structures.
One important caution: never give away so much that you struggle to fund your own retirement. Keep enough to cover care costs and a comfortable lifestyle. Only gift what you are confident you will not need.
Record Your Funeral Wishes Clearly
Funeral arrangements sit at the intersection of practical and emotional decisions. Some people have strong preferences about burial or cremation, the type of service, music or whether organs should be donated. Writing those wishes down removes uncertainty for the family at a difficult time.
You can include them in your will, though they are not legally binding. A separate letter or document kept with your other papers works just as well. Tell at least one trusted person where the document lives.
Think about payment too. Some life insurance policies include funeral cover. Pre-paid funeral plans lock in today’s prices. Even without those arrangements, funeral directors can usually access funds from a frozen bank account to cover reasonable costs.
Create a Simple Financial Fact File
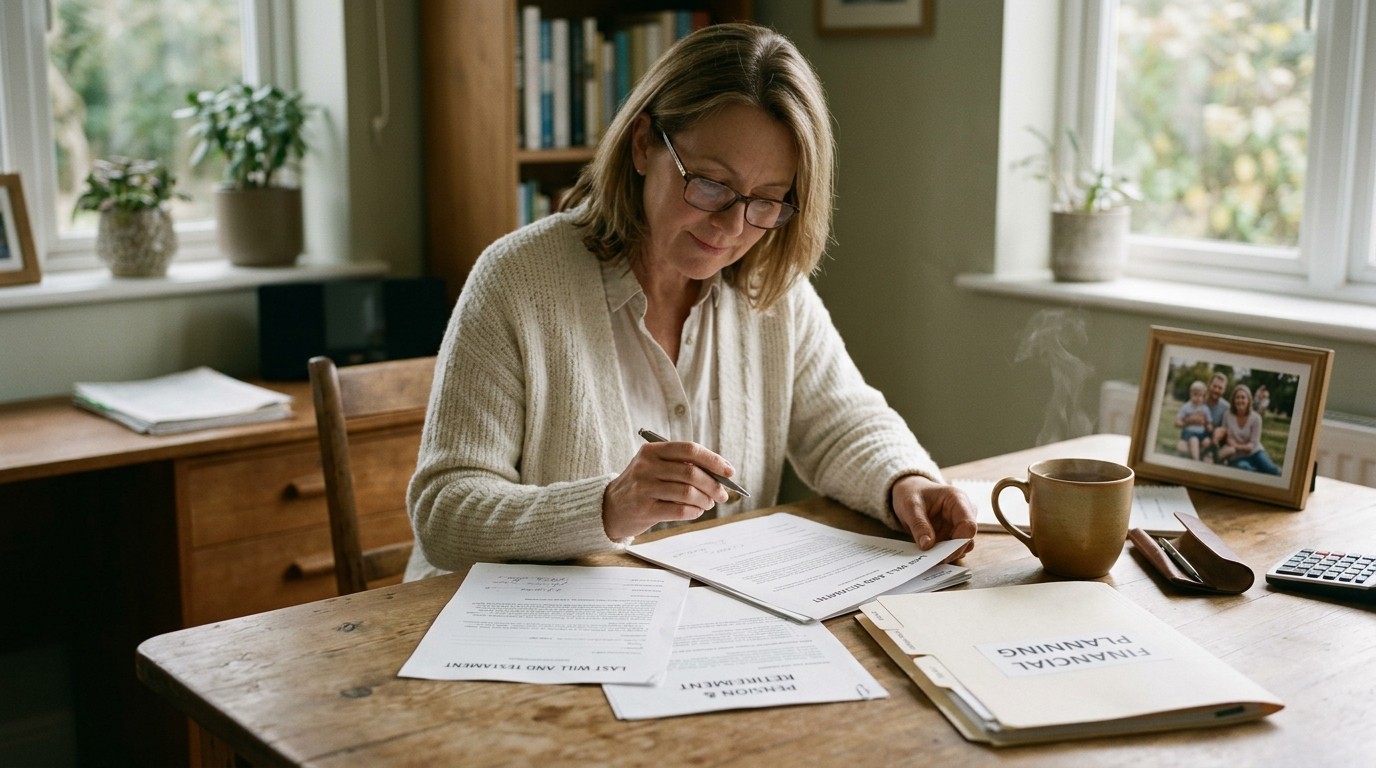
This is the step that saves families the most time and stress. A single document listing every bank account, credit card, mortgage, pension, insurance policy and important online account gives executors a clear starting point. Include the name of the provider, a short description and contact details. Never write passwords or PINs in the file.
Keep the document in a secure but accessible place, ideally the same location as the will. A locked filing cabinet at home or a solicitor’s office both work. Update it whenever something changes.
Digital accounts deserve a mention. Social media profiles, email and cloud storage often contain photos and messages that family members want to preserve or close. Listing the main accounts and noting your preferences makes that process far smoother.
Practical Steps You Can Take This Month
Feeling overwhelmed is normal. Break the work into small actions. Start with the will if you do not have one. Then locate every pension statement and check the nomination forms. Draft a short funeral preference note. Finally, begin the fact file by listing bank accounts and insurance policies.
- Book a conversation with a solicitor or use a reputable will-writing service if your affairs are straightforward
- Contact each pension provider and request the current beneficiary form
- Write down funeral wishes in plain language and share the location with one person
- Create a simple spreadsheet or notebook of financial accounts
- Review the whole package every three to five years or after major life changes
In my experience the families who handle bereavement with the least additional stress are those where the deceased took these steps. The paperwork does not remove grief, but it removes a layer of chaos that nobody needs.
Common Mistakes Worth Avoiding
Leaving the will unsigned or improperly witnessed is surprisingly common. Another frequent error is forgetting to update pension nominations after a divorce. People also sometimes gift large sums without considering their own future care needs, only to regret it later.
Assuming that “everyone knows what I want” is risky. Memories fade and family members may interpret past conversations differently. Written instructions remove that ambiguity.
Finally, do not put everything off until a major health scare. By then energy and mental clarity may be lower. Completing the work while you feel well is kinder to yourself and everyone around you.
How Conversations Help More Than Documents Alone
Documents are essential, yet they work best when supported by open discussion. Adult children sometimes worry about appearing greedy if they ask questions. Parents sometimes fear causing offence by stating their plans. A calm, planned conversation removes both barriers.
You might say you are reviewing your will and would value their thoughts on certain items. Or explain that you have updated pension nominations and want them to know roughly how things stand. The exact words matter less than the willingness to talk.
These discussions often reveal practical issues you had not considered. One child may live far away and prefer not to act as executor. Another may have strong feelings about a family home. Better to discover those points while you can still adjust the plans.
Keeping Everything Up to Date Over Time
Life rarely stands still. A new grandchild, a house move, a change in relationship status or a significant shift in assets can all make previous arrangements outdated. Set a simple reminder every few years to review the will, pension forms, fact file and funeral wishes together.
Some people choose a specific date, such as their birthday or the start of the tax year, as an annual check-in point. Others review after any major family event. Consistency matters more than the exact schedule.
When you do update documents, destroy older versions or clearly mark them as superseded. Multiple conflicting wills or nomination forms create exactly the confusion you are trying to avoid.
The Quiet Benefit Nobody Talks About Enough
Beyond the practical advantages sits something softer. Completing this work often changes how people feel about the future. Instead of a vague sense of unfinished business, there is a clearer mental picture. You know the important decisions have been made and recorded.
That clarity frees mental energy. You can focus on living rather than worrying about what might happen if something unexpected occurs. Families notice the difference too. They sense that the person has taken responsibility and made thoughtful arrangements.
I have spoken with people who finished the process and immediately felt lighter. The paperwork itself is rarely enjoyable, but the result is worth the effort many times over.
Putting It All Together Without Overwhelm
Begin with the single most important document you currently lack. For many that is a will. For others it is an updated pension nomination. Tackle one item thoroughly before moving to the next. Celebrate small progress rather than waiting for everything to be perfect.
If the scale feels large, consider professional help for the legal and tax elements while handling the personal fact file and funeral wishes yourself. Many people find that combination works well.
Remember that perfection is not required. A clear, reasonably up-to-date set of instructions is vastly better than none at all. Your family will be grateful for whatever level of organisation you manage to achieve.
Sorting your finances before you die is ultimately an act of care. It reduces the administrative burden at a time when emotional energy is already low. It increases the chance that your actual wishes are followed. And it leaves a quieter, more orderly legacy than chaos and unanswered questions.
Start with one conversation or one form this week. The rest becomes easier once the first step is behind you. Your future self, and the people who matter most to you, will thank you for it.