

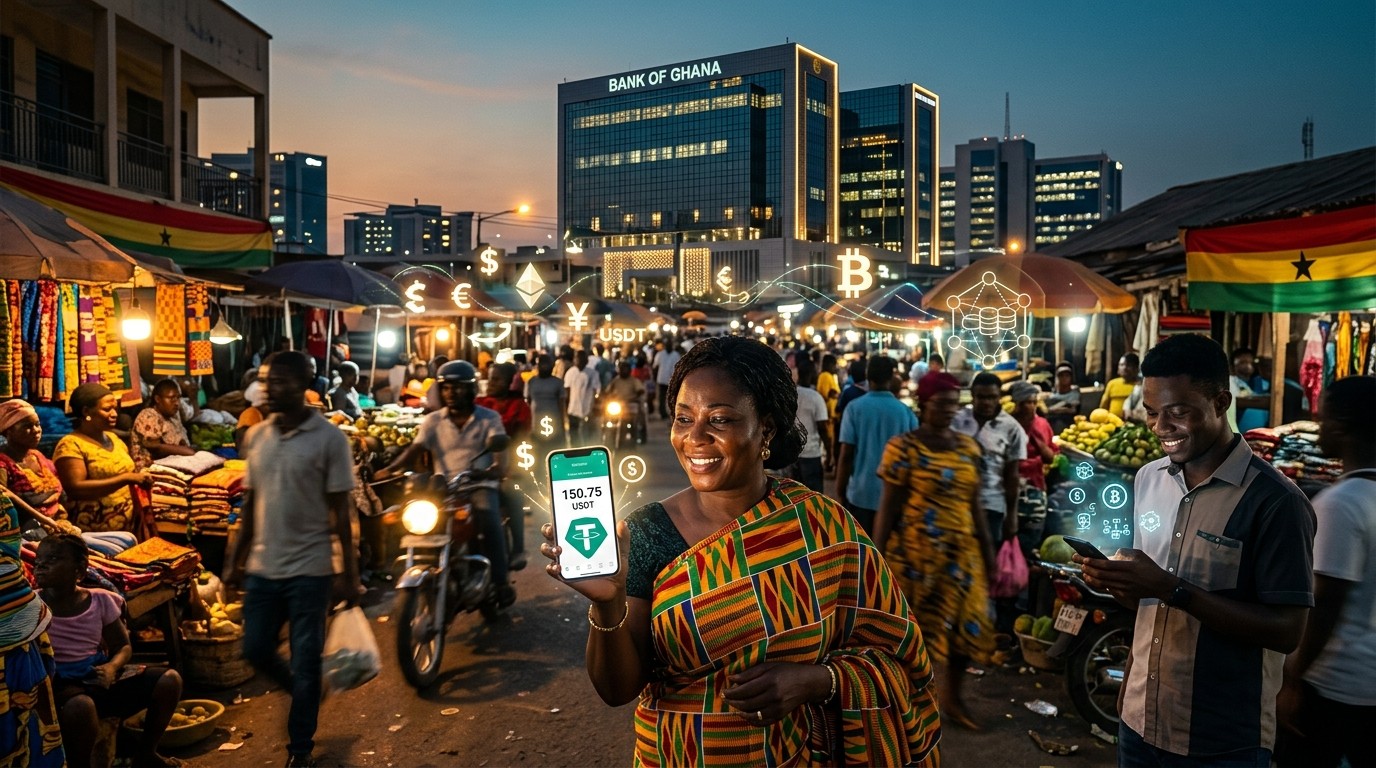

Twenty-one billion dollars is not a rounding error. When a market that size shows up in a country still building formal digital-asset rules, people notice. Ghana has now been placed fifth among crypto markets in sub-Saharan Africa, and the figure that keeps circulating is roughly $21 billion in estimated annual transaction activity. That number does not mean $21 billion of fresh cash walked through the front door. It does mean the traffic is large enough that ignoring it is no longer a serious option.
Ghana Joins Africa’s Top Crypto Markets
I’ve been watching African digital-asset stories for a while, and this one feels different from the usual hype cycle. The estimate sits beside another striking range: somewhere between 8% and 17% of Ghanaians have bought or sold crypto assets. Even if you take the low end, that is a lot of households with at least one experiment in digital value. At the high end, it starts looking like a social habit, not a niche hobby.
The ranking is based on reviewed activity, not a public audit of every wallet. That matters. Crypto volume can double-count the same coins as they hop from exchange to personal wallet to another counterparty. Still, fifth place in the region is not a vanity stat. It tells you Ghana is no longer on the sidelines of African crypto use. Trading, hedging, and informal settlement have piled up faster than the paperwork.
A market can look small on paper until you count how often value actually moves.
Local authorities now put the user base above three million. That is the kind of figure that changes a policy meeting. You can debate the methodology. You cannot pretend three million people are waiting politely for a perfect rulebook.
Why The $21 Billion Figure Needs A Closer Look
Transaction estimates in crypto are messy by design. One dollar of stablecoin can travel through several venues in a single afternoon. An exchange transfer, a peer payment, and a later conversion can all show up as activity. So the $21 billion should be read as intensity, not as a clean inflow of new savings.
That still leaves a serious conclusion. If the measured flow is this large after you accept the double-counting problem, the underlying use is not tiny. People are moving value because the rails they already have are slow, expensive, or unreliable. In my experience, that is when markets jump the queue and force regulators to catch up.
Perhaps the most interesting aspect is how ordinary the use cases sound. This is not only about speculative charts. A shop owner settling a supplier. A trader parking value overnight. A family trying to keep purchasing power when the local currency wobbles. Those stories add up.
How Widespread Crypto Use Has Become
An 8% to 17% participation band is wide on purpose. Surveys and technical estimates rarely agree on exact ownership. Some people try crypto once and leave. Others keep a small balance for transfers. A smaller group trades actively. The range still tells a policy story: crypto is no longer confined to a handful of Accra tech circles.
- Retail users testing exchanges and peer transfers
- Traders using dollar-linked tokens as a hedge
- Informal businesses settling across borders
- A smaller group experimenting with tokenized assets
Those layers do not grow at the same speed. Trading and hedging appear to be out in front. Tokenization is smaller but no longer theoretical. Remittances through crypto remain limited, which surprises people who assume every African crypto story is a remittance story. Ghana’s pattern looks more like domestic trading plus informal commercial settlement.
Stablecoins Are Doing The Heavy Lifting
If one product family is carrying this market, it is stablecoins. Dollar-linked tokens are easier to explain than volatile coins. They also map onto a very practical problem: how to hold value that does not slide every month. Trading desks like them because they are liquid. Households like them because they feel closer to cash than to a lottery ticket.
Inflation hedging is the quiet driver. When prices at the market stall keep jumping, a token that aims to stay near one dollar becomes a tool, not a slogan. I have found that this is where adoption gets sticky. People may not care about consensus algorithms. They care whether last month’s savings still buy the same bag of rice.
Cross-border settlement is the second engine. Formal banking rails can be slow for small commercial transfers. Informal networks fill the gap, and stablecoins fit those networks surprisingly well. Retail remittance use is still described as modest. That gap is worth watching. The technology can move money. Habit, trust, and last-mile cash-out still decide whether families actually use it.
Stablecoins spread first where people need a dollar they can send at midnight.
What Tokenization Looks Like On The Ground
Asset tokenization is the smaller subplot, but it keeps showing up in regulatory conversations. Gold, securities, Treasury bills, bonds, and trade finance have all been mentioned as test cases. That mix is revealing. It is not only about meme coins or high-beta tokens. Some teams are trying to put familiar Ghanaian instruments onto digital rails.
Does that mean tokenized Treasury bills will become mainstream next year? Probably not. Sandbox pilots are not the same thing as mass adoption. Still, the fact that these products are being tested inside a supervised environment says the market is broader than spot trading.
I’ve always thought tokenization only becomes interesting when it solves a local friction. If a gold token makes custody simpler, or a bill product shortens settlement, users will care. If it is just a wrapper with extra steps, they will not.
A New Law Split Oversight In Two
Ghana already has a legal base. Parliament passed a virtual asset service providers law in late 2025. The resulting act gives the central bank and the securities regulator shared but distinct jobs. That split is common around the world, and it is also where coordination problems usually start.
The securities side handles activities that look like investment products. The central bank watches payments, stability, and anything that behaves like money. In theory the map is clean. In practice a single firm can run an exchange, a wallet, a brokerage desk, and a token project. One license conversation becomes two. Maybe three if financial-crime reporting is counted separately.
The covered list is long: exchanges, wallets, token issuance, stablecoins, lending, brokerage, and asset tokenization. That breadth is ambitious. It is also why supervisors are being told to finish missing guidelines before the queue gets crowded.
Where The Rulebook Still Has Gaps
International reviewers have said Ghana’s direction of travel looks familiar: prudential rules, conduct rules, licensing, reporting. The unfinished work sits in the details. Trading, brokerage, and crypto lending need tighter activity-based standards. Stablecoin arrangements need clearer answers on reserves, liquidity, and redemption.
Those three words sound dull until something breaks. Reserve quality decides whether a token is a cash substitute or a promise. Liquidity decides whether redemptions survive a bad week. Redemption rights decide whether users can actually exit. If those pieces stay vague, a $21 billion market can create a $21 billion argument.
- Finish the missing activity guidelines
- Align licensing outcomes across agencies
- Standardize reporting templates
- Build supervisory capacity before the rush
There is also a volume problem. Once formal licensing opens fully, a large number of firms may apply at once. If two agencies give different answers to the same business model, the market will shop for the easier door. Aligned outcomes are not a nicety. They are how you keep the framework from splitting in half.
Twenty Firms Are Already In The Sandbox
Ghana is not waiting for a perfect statute before it watches real products. The securities regulator opened a virtual-asset sandbox, started with a smaller group, and later published a list of twenty participants. That is a meaningful sample. It includes exchanges, trading platforms, brokerage experiments, and tokenization pilots.
The pilot was designed as a twelve-month process, with an earlier off-ramp after six months for firms that are market-ready and compliant. That structure is practical. Supervisors get live data. Firms get a path that is not endless theater. Users get a slightly clearer signal about who is at least willing to sit in a supervised room.
Names in the sandbox cover exchange services, gold tokenization, securities tokenization, and a Treasury-bill product. I like that mix more than a list of twenty identical trading apps. Diversity in the test bed makes the eventual license categories less abstract.
| Activity Cluster | What Is Being Tested | Regulatory Tension |
| Exchanges and trading | Onboarding, order flow, custody | Consumer protection and market integrity |
| Brokerage | Intermediation and advice-like services | Conduct and disclosure |
| Stablecoin arrangements | Issuance, reserves, redemption | Money-like risk |
| Tokenization | Gold, securities, bills, trade finance | Securities perimeter |
Advertising Rules Arrived Before Full Licenses
One early enforcement choice stands out. Authorities have warned virtual-asset businesses against unauthorized advertising of crypto and stablecoin products. Promotion now needs approval. That is a classic sequencing move. If you cannot finish every prudential chapter tomorrow, you can at least stop unfiltered marketing from running ahead of the facts.
Is that popular with growth teams? Of course not. It still makes sense in a market where millions of people are already reachable on their phones. A polished ad can outrun a user’s understanding in about fifteen seconds. Slowing that down is not anti-innovation. It is damage control.
The central bank has also stood up a dedicated virtual assets unit. Licensing, compliance, consumer safeguards, cybersecurity, and financial-crime risk all sit in that mandate, coordinated with the securities regulator and the financial intelligence body. On paper, that is the right triangle. The test is staffing and tools, not org charts.
Why Licensing Could Get Crowded Fast
Technical assistance work produced licensing checklists, risk-assessment tables, and reporting templates. That sounds bureaucratic until you imagine twenty, then fifty, then more applicants arriving with different business models and the same urgent timeline. Checklists are how a small team avoids improvising a different standard for every file.
The timetable is tight because the market is already large. That is the awkward part. Regulators usually prefer to write rules while activity is still small. Ghana is doing the opposite. The activity arrived first. The law arrived next. The detailed manuals are still being finished. I’ve found that this sequence is common in emerging digital-asset markets. It is also the sequence that produces the most political heat.
Will every applicant look like a clean exchange? Unlikely. Some will blend payments and securities. Some will look like lenders. Some will issue tokens that behave like deposits on busy days and like risk assets on quiet ones. Activity-based rules are supposed to handle that. They only work if the definitions are sharp.
Consumer Risk Is Not A Side Issue
A market with millions of users and incomplete conduct rules is a consumer-protection problem waiting for a headline. People will confuse a stablecoin with a bank deposit. They will confuse a tokenized bill with a government guarantee. They will confuse a sandbox participant with a fully licensed institution. Those confusions are predictable. That means they are preventable, at least in part.
Cybersecurity and financial-crime controls sit right next to that. High transaction intensity attracts both innovation and abuse. If supervision is thin, the same rails that help a trader hedge can help someone move value that should have been stopped. The public will not parse those distinctions after a scandal. They will ask why the state waited.
Speed without safeguards is not inclusion. It is just a faster way to lose trust.
What This Means For The Wider Region
Ghana’s fifth-place ranking is a regional signal. Neighboring markets will compare notes. Some will copy the dual-regulator model. Some will push stablecoin rules first. Some will keep waiting and watch Ghana’s licensing queue as a live case study. That is useful. Policy in this space travels by imitation as much as by theory.
There is also a competitive angle. If Ghana can make licensing predictable, serious firms may prefer a clear process over a quieter market with no process at all. If the process is slow or contradictory, activity will stay informal. Informal activity does not disappear. It just becomes harder to see and harder to protect.
I keep coming back to that point. The choice is not “crypto or no crypto.” The choice is supervised rails versus shadow rails. A $21 billion estimate makes that choice urgent.
The Practical Questions Firms Should Ask Now
If you run a virtual-asset business aimed at Ghana, the next twelve months are less about slogans and more about files. Can you explain your activity in the language of the statute? Can you show reserve, custody, and redemption mechanics without hand-waving? Can you map which agency owns which piece of your stack?
- Separate payments-like functions from securities-like functions
- Document stablecoin reserve quality and liquidity backstops
- Prepare consumer disclosures that a non-trader can actually read
- Treat advertising as a regulated act, not a growth hack
- Assume reporting will be requested in more than one format
None of that is glamorous. It is how you stay in the market after the sandbox photos are done.
Users Should Slow Down Before They Scale Up
For individuals, the headline number can create false comfort. A large market is not the same thing as a safe product. Ask where tokens are held. Ask how redemptions work. Ask whether a platform is in a pilot or claiming a finished license. If the answer is a shrug, that is your answer.
Stablecoins can be useful hedges. They can also fail in ways that look boring until they are not. Tokenized assets can be innovative. They can also be old risk in a new wrapper. A little skepticism is not anti-progress. It is how you keep the useful parts of this market from being defined by the worst parts.
The Story Is Bigger Than A Ranking
Fifth in sub-Saharan Africa sounds like a trophy. It is really a warning light. Ghana has the users, the transaction intensity, a legal foundation, a sandbox full of live firms, and a list of unfinished rules. That combination can produce a durable market. It can also produce a messy rush.
The next phase will be less about whether crypto exists in Ghana. It already does. The next phase is whether stablecoin reserves are solid, whether dual oversight stays coordinated, and whether three million users get clearer protections before the next wave of applications lands. That is the unglamorous work. It is also the work that decides if $21 billion becomes a development story or just another noisy cycle.
If regulators finish the guidelines and firms treat licensing as more than a badge, Ghana could show the region how a fast market gets brought indoors without being smothered. If they do not, the activity will keep moving anyway. It always does. The only question is whether it moves in daylight.



