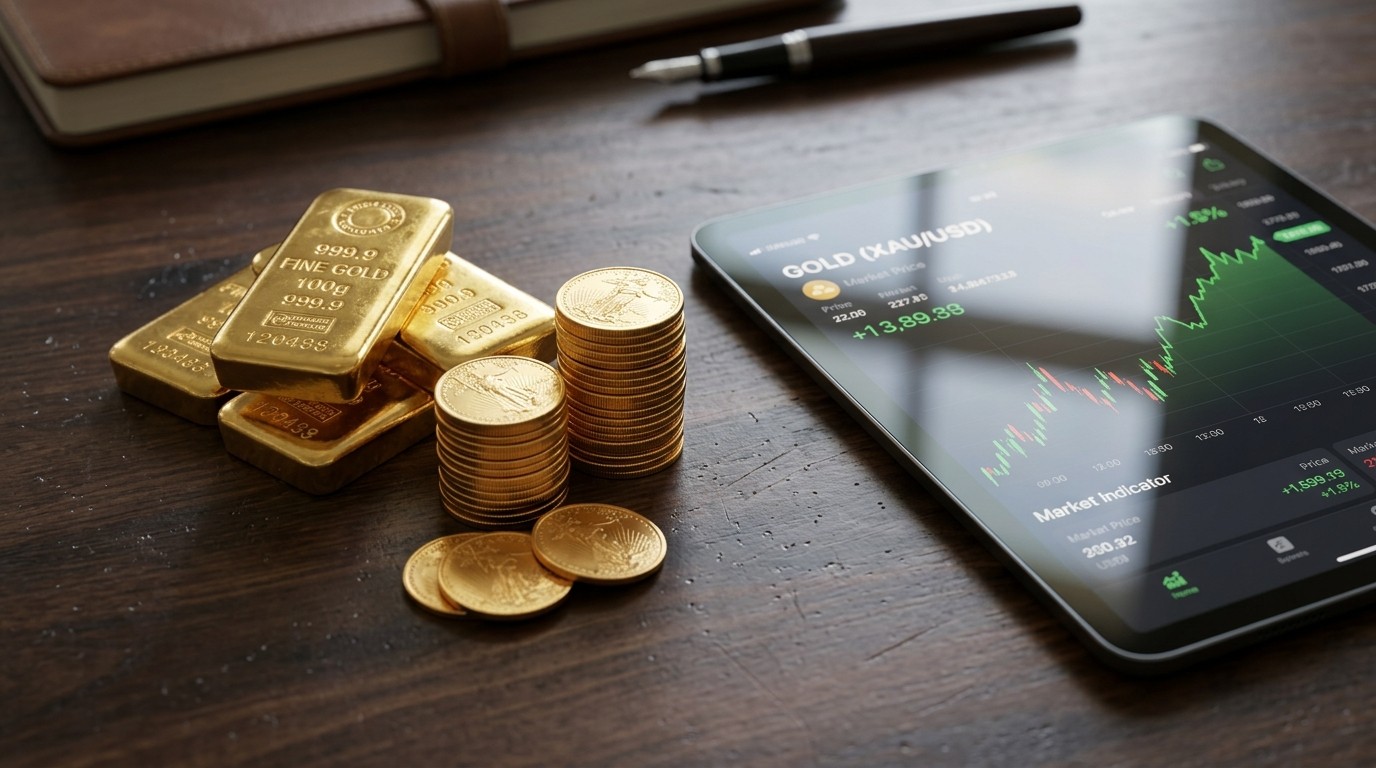

I checked the numbers this morning and had to look twice. Gold’s spot price sat at $4,095.81 per ounce as of 9:00 a.m. ET on October 14, 2026. That is a noticeable step down from the $4,179.27 it was trading at the same time yesterday. Still, those figures remain far above levels most of us remember from even a few years ago. When markets feel shaky or inflation starts whispering again, people almost instinctively turn toward this metal. I have watched that pattern repeat enough times to know it is not random.
Why Gold Still Matters In Uncertain Times
Gold does not pay dividends. It does not throw off interest. On paper it looks almost boring next to a stock that keeps climbing or a bond that delivers steady income. Yet its reputation as a safe-haven asset has held for generations. When political headlines turn noisy or economic data surprises to the downside, capital tends to flow toward something tangible. Gold has filled that role for centuries, and the recent price action shows the pattern continues.
In my experience, the metal works best as a portfolio stabilizer rather than a pure growth engine. It often moves in the opposite direction of risk assets during stress periods. That negative correlation is the main reason many long-term investors keep a small allocation. The inability to generate cash flow is real, of course. You only make money if the price rises or if you eventually sell. That single limitation is why the way you hold gold matters just as much as the decision to own it at all.
Three practical routes stand out for most people: buying physical metal, opening a specialized retirement account, or using exchange-traded funds. Each path carries its own costs, convenience factors, and tax implications. Choosing the wrong one can quietly erode returns over time. Let’s walk through them without the usual marketing gloss.
Buying Physical Gold Bars And Coins
Holding actual gold in your hands still appeals to a certain type of investor. There is something reassuring about knowing the metal sits in a safe rather than existing only as a line on a brokerage statement. Bars and high-purity bullion remain the most straightforward form. Coins often carry extra premiums because of design, rarity, or collector demand, so pure investment purchases usually favor bars or standard bullion coins.
Several established dealers specialize in this market. Some have operated online for decades and offer both buying and selling services. Free shipping on larger domestic orders is common once you clear a certain threshold. Payment method can change the final price you pay, which is worth checking carefully before you commit. Cancelled orders sometimes trigger fees, so double-check the details.
Everyday retailers have also entered the space. You can occasionally find gold products on the shelves of major warehouse clubs or large online marketplaces. The convenience is attractive, yet availability fluctuates and premiums can vary widely. I have found that comparing the dealer’s spot-plus-premium figure against the current market price is the only reliable way to know whether a deal is competitive.
Storage is the part most people underestimate. Once the gold is yours, you become responsible for keeping it secure. A home safe works for smaller amounts, but larger holdings often push people toward professional vault services. Insurance becomes another line item. Liquidity is slower than selling a stock. You need a willing buyer, and the bid-ask spread can be wider than you expect during calm markets.
Physical ownership gives psychological comfort that paper claims never quite match, yet it demands more ongoing attention than most other investments.
For beginners with modest capital, starting with a few smaller coins or bars can feel less intimidating. Larger investors sometimes prefer one-kilogram bars to reduce the premium per ounce. Either way, plan the exit strategy before you buy. Knowing who will buy the metal back and under what conditions removes a surprising amount of future stress.
Opening A Gold IRA For Tax Advantages
A self-directed IRA that holds physical precious metals solves several headaches at once. The gold must come from an IRS-approved refinery, and a qualified custodian takes care of storage. You never see the bars, yet they remain allocated to your account. The tax treatment mirrors traditional or Roth IRAs, depending on the structure you choose. Contributions may be deductible, or growth can be tax-free in the Roth version.
Fees are the trade-off. Most providers charge an account setup fee, annual administration fees, and storage costs. Those numbers add up, especially on smaller balances. Some companies waive the first year’s fees once the account reaches a certain size, which can help. Minimum initial purchases often start around ten thousand dollars, and account balance requirements can be higher.
I have noticed that investors who already have substantial retirement savings find this route more appealing. Rolling over an existing traditional IRA or 401(k) can fund the purchase without triggering immediate taxes. The process takes time—sometimes several weeks—so patience is required. Once established, the account grows only when the metal’s price rises. No dividends, no interest, just pure price appreciation.
Several providers stand out for transparent fee schedules and strong customer service ratings. Look for clear disclosure of storage options (segregated versus non-segregated) and any buyback policies. A few companies guarantee they will repurchase your metal at competitive rates when you decide to sell, which can simplify the exit.
- Setup fees are usually modest but still worth budgeting
- Annual storage and administration costs vary by provider and account size
- Minimum purchase thresholds can exclude smaller investors
- Transfer timelines from existing retirement accounts often stretch longer than expected
The biggest advantage remains the tax shelter. For someone in a high tax bracket who wants gold exposure inside a retirement wrapper, this structure can make sense. Just run the numbers carefully. High fees on a modest account can offset much of the potential gain.
Investing Through Gold ETFs
Exchange-traded funds offer the simplest entry point for most people. You buy shares the same way you buy any other stock or fund. Some ETFs hold physical gold in vaults and track the spot price closely. Others invest in mining companies, which adds operational risk and potential leverage to gold’s moves. The pure bullion funds tend to behave more predictably as a hedge.
Liquidity is excellent during market hours. You can enter or exit in seconds. Expense ratios are generally low, especially compared with the ongoing costs of a gold IRA. No storage worries, no insurance decisions, and no minimum purchase beyond the price of a single share or fractional share if your broker allows it.
Major brokerage platforms make the process straightforward. Commission-free trading on ETFs is now standard at many firms. Research tools and educational resources are usually solid. For investors who already hold stocks and bonds in a regular brokerage account, adding a gold ETF takes almost no extra effort.
The downside is that you never own the metal itself. You own a claim on it through the fund structure. For pureists who want the tangible asset, this feels incomplete. Tax treatment also differs. Gains in a taxable account are subject to capital gains rates, and the IRS currently treats certain gold ETFs as collectibles, which can mean a higher long-term rate. Inside an IRA the tax issue largely disappears.
In my view, ETFs work best for the portion of a portfolio that needs quick adjustability. If you want the option to increase or decrease exposure within a single trading day, this is the cleanest route. Physical metal and gold IRAs lock you in more tightly.
Comparing The Three Main Approaches
Choosing among physical metal, a gold IRA, and ETFs depends on your priorities. Here is a quick side-by-side look at the practical differences.
| Method | Liquidity | Storage Responsibility | Tax Treatment | Ongoing Costs |
| Physical Gold | Moderate | High – you handle it | Capital gains on sale | Insurance, possible vault fees |
| Gold IRA | Lower | None – custodian handles | IRA rules apply | Setup, annual admin, storage |
| Gold ETF | High | None | Capital gains or IRA rules | Low expense ratio |
No single option wins for everyone. Someone who values the feeling of ownership and has secure storage may prefer physical bars. An investor focused on retirement tax advantages often leans toward the IRA. The majority of people who simply want gold exposure without complications usually end up with an ETF.
Practical Tips For Beginners
Start by deciding how much of your overall portfolio you want in gold. Many advisors suggest a range between five and ten percent, though the right number depends on your risk tolerance and existing assets. Going all-in rarely makes sense because the metal can stay flat for long stretches.
If capital is limited, small physical coins or a low-cost ETF share can get you started without large commitments. Larger balances open the door to gold IRAs and bulk bar purchases where premiums shrink. Always calculate the total cost of ownership, not just the headline price.
Watch the premium over spot carefully. During periods of high demand those markups can widen significantly. Waiting for calmer markets sometimes saves more money than trying to time the exact bottom.
Document everything. Keep receipts, serial numbers for bars, and account statements. When the time comes to sell or transfer, clear records make the process far smoother.
Common Questions Investors Ask
How should a complete beginner approach gold? Match the method to the size of the intended investment. Modest amounts usually fit best with coins, small bars, or ETF shares. Larger transfers often work more efficiently inside a gold IRA.
What are the main advantages? Diversification, a historical inflation hedge, and potential outperformance during equity market stress. Those qualities have kept gold relevant across decades of changing economic conditions.
And the drawbacks? No income generation, storage or fee costs, and sometimes slower liquidity compared with stocks. Understanding those limitations up front prevents later disappointment.
Is now a good time? Prices sit at elevated levels by historical standards, yet the same was true at previous peaks that later proved temporary. Focus more on your personal allocation plan than on trying to call the exact top or bottom.
Putting It All Together
Gold’s role in a modern portfolio remains straightforward. It is not a growth engine and it will not generate cash flow. What it can do is provide ballast when other assets hit rough water. The price movement over the past day shows that even strong trends experience pullbacks. That reality is healthy. It creates room for thoughtful buyers rather than pure momentum chasers.
I have found that the investors who sleep best are the ones who choose a method matching their lifestyle and then stick with a modest allocation. Physical metal for those who want something they can touch. A gold IRA for tax-conscious retirement savers. ETFs for everyone who values simplicity and speed. Mixing approaches is possible too, though it adds complexity.
Whatever route you take, treat gold as insurance rather than a speculative bet. Check the total costs, understand the liquidity path, and size the position so that a multi-year flat period would not disrupt your broader plans. That mindset has served long-term holders well through many market cycles.
The numbers this morning may have pulled back a bit, yet the underlying reasons people buy gold have not disappeared. Economic uncertainty, currency concerns, and the desire for something tangible continue to support demand. By matching the ownership method to your own circumstances, you can participate without unnecessary friction.
Take the time to compare the real costs and practical requirements of each path. The difference between a smooth experience and a frustrating one often comes down to those details rather than the exact entry price. Once the structure is right, the metal can do its quiet work in the background while the rest of the portfolio focuses on growth.
Markets will keep moving. Gold will keep responding in its own way. Having a clear plan for how you hold it turns an emotional decision into a deliberate one. That shift alone can make the difference between owning an asset and merely reacting to its price.