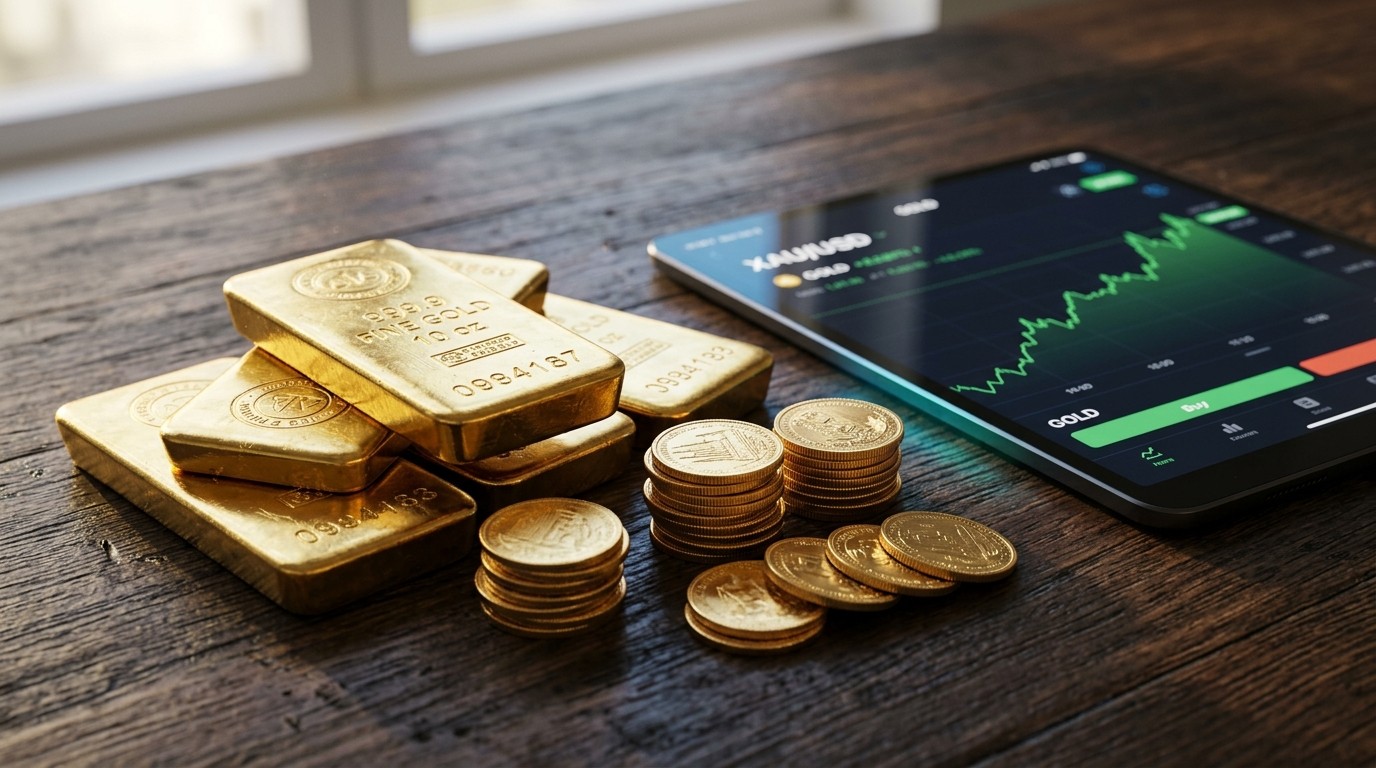

I checked the numbers first thing this morning and, once again, gold refused to sit still. As of 9:00 a.m. ET on October 19, 2026, the spot price sits at $4,161.54 per ounce. That’s a modest dip from Friday’s $4,165.55 reading, yet the metal remains near the elevated levels that have defined much of this year. Markets keep swinging between cautious optimism and outright nervousness, and gold continues to act like the quiet friend who shows up whenever the room gets tense.
Understanding Today’s Gold Price And Why It Still Matters
Gold does not pay dividends. It does not throw off quarterly earnings calls. Yet investors keep returning to it for a simple reason: when inflation creeps higher or geopolitical headlines turn sharp, the metal tends to hold its ground better than most paper assets. That reliability is why the current price still draws attention even after a small overnight pullback.
In my experience, the real question is rarely “Is gold expensive right now?” The better question is “Does a slice of gold still make sense inside a broader portfolio?” For many people the answer remains yes, provided they choose the right vehicle and understand the trade-offs.
What the Latest Spot Price Actually Tells Us
A move of four dollars per ounce is noise in the bigger picture. Gold has spent recent months trading in a relatively elevated band, reflecting ongoing demand for assets that sit outside the usual stock-and-bond correlation. Central bank buying, retail interest in physical metal, and periodic risk-off flows all play a part. The modest decline from Friday does not erase the longer-term trend that has kept prices historically high.
Perhaps the most interesting aspect is how steadily the metal has absorbed economic surprises this year. Rate expectations shift, equity markets wobble, and gold simply digests the news. That calm is exactly why many long-term investors treat it as portfolio insurance rather than a pure speculation.
Three Practical Routes Into Gold Ownership
You can own gold in several distinct ways, each with its own personality. Some people want the satisfaction of holding actual metal. Others prefer the tax advantages of a retirement account. Still others want the liquidity of an exchange-traded fund. None is universally better; the right choice depends on your timeline, tax situation, and tolerance for storage headaches.
Buying Physical Gold: Bars, Coins, And Everyday Retailers
Physical gold remains the purest form of ownership. You purchase high-purity bars or widely recognized coins and take possession. Dealers specializing in precious metals have offered this route for decades, and larger retailers have joined the space in recent years, making small purchases more accessible.
Bars, often called bullion, appeal to those focused strictly on metal content. Coins add another layer: some carry historical or collectible premiums that can move independently of the spot price. Both formats require you to think carefully about storage. A home safe works for modest amounts; larger holdings usually belong in a professional vault or bank safe-deposit box.
One practical reality many first-time buyers overlook is liquidity. Turning physical gold back into cash means finding a reputable buyer and accepting the current bid price, which includes dealer margins. It is not as instant as selling a stock. Still, the psychological comfort of holding something tangible keeps this route popular.
- Research current premiums over spot before placing an order
- Compare shipping and insurance costs carefully
- Plan secure storage from day one
- Keep detailed purchase records for tax purposes
I’ve found that people who start small—perhaps a single one-ounce coin—often feel more comfortable scaling up later. The learning curve around authenticity, packaging, and resale is gentler when the first transaction is modest.
Opening a Gold IRA: Tax Advantages With Built-In Storage
A gold IRA lets you hold IRS-approved gold inside a self-directed retirement account. A custodian handles the paperwork and arranges secure storage at an approved depository. You never take physical delivery while the metal remains inside the account, which removes the home-storage problem.
The tax treatment mirrors other IRAs: contributions may be deductible in a traditional account, and growth compounds tax-deferred. Roth versions offer tax-free qualified withdrawals. Those benefits come with fees—setup, annual administration, and storage—that can add up, especially on smaller balances.
Minimum purchase and account-balance requirements often start around the ten-thousand-dollar mark. Some providers will waive the first year’s fees once the account reaches a higher threshold. Transferring existing retirement assets into a gold IRA is possible, though the process can take several weeks.
Gold IRAs work best for investors who already have a solid retirement foundation and want a modest allocation to precious metals without handling the metal themselves.
In my view, the key is transparency. Look for providers that publish fee schedules clearly and maintain strong ratings from independent business bureaus. Avoid any firm that pressures you into large minimums or downplays ongoing costs.
Investing Through Gold ETFs: Simplicity And Daily Liquidity
Exchange-traded funds that track the gold price offer the easiest entry point for most brokerage accounts. Some funds hold physical bullion in vaults; others hold shares of mining companies whose fortunes roughly follow the metal. Either way, you buy and sell shares the same way you would any stock or ordinary ETF.
The advantages are obvious: no storage concerns, low expense ratios at many large providers, and the ability to rebalance with a few clicks. The main drawback is that you own a claim on gold rather than the metal itself. For pure price exposure that distinction rarely matters day to day.
Major brokerage platforms make these funds available with zero commission trades in many cases. That accessibility has turned gold ETFs into a favorite tool for both tactical traders and long-term allocators who simply want a 5 or 10 percent portfolio sleeve in the metal.
Comparing the Three Approaches Side by Side
| Method | Ownership Type | Liquidity | Ongoing Costs | Best For |
| Physical Gold | Direct metal | Moderate | Storage & insurance | Hands-on investors |
| Gold IRA | Custodied metal | Lower | Setup + annual fees | Retirement accounts |
| Gold ETF | Fund shares | High | Expense ratio | Everyday brokerage users |
Looking at the table, the pattern becomes clear. Physical gold maximizes control and tangibility. A gold IRA layers on tax advantages at the cost of flexibility. ETFs win on convenience and low friction. Many investors eventually combine two of the three rather than choosing only one.
Practical Considerations Before You Commit Capital
Position size matters more than perfect timing. A 5 to 15 percent allocation to gold has historically been enough to provide meaningful diversification without dominating returns. Going all-in rarely ends well; the metal can spend long stretches moving sideways while stocks climb.
Taxes also deserve attention. Physical sales can trigger capital-gains reporting. IRA distributions follow ordinary retirement rules. ETF shares are taxed like other securities held in taxable accounts. Keeping records organized from the first purchase saves headaches later.
Storage security is non-negotiable with physical metal. Insurance policies, home-safe ratings, and depository audits all factor into the real cost of ownership. Underestimating those expenses is a common beginner mistake.
How Beginners Can Start Without Overcomplicating Things
If your budget is limited, small physical coins or a modest ETF purchase often make the cleanest entry. Larger sums can justify exploring a gold IRA once you understand the fee structure. The goal is to learn the mechanics with an amount you can afford to leave alone for years.
I’ve watched too many people chase the exact bottom tick and end up never buying at all. Dollar-cost averaging into any of the three methods removes much of that pressure. Consistency beats perfection here.
- Decide your target allocation percentage
- Choose the ownership method that fits your lifestyle
- Compare all-in costs, not just the headline premium
- Set up secure storage or choose a reputable custodian
- Review the position annually rather than daily
Pros And Cons Worth Weighing Carefully
On the positive side, gold has a long track record as a diversifier and inflation hedge. It tends to move differently from stocks and bonds, which can smooth overall portfolio volatility. During periods of genuine market stress it often attracts fresh capital.
The drawbacks are equally real. Gold generates no income. Storage and insurance cost money. Physical metal can be slow to sell at full value. Mining-related ETFs introduce company-specific risks that pure bullion avoids. Understanding both sides keeps expectations realistic.
Gold works best as a quiet insurance policy, not as the star of the portfolio.
Common Questions New Gold Investors Keep Asking
How much should a beginner put into gold? Most balanced portfolios allocate a single-digit to low-double-digit percentage. Starting smaller and adding over time reduces the emotional weight of any single purchase.
Is physical gold better than an ETF? It depends on whether you value tangible ownership or daily liquidity more highly. Both can track the spot price effectively when structured properly.
What about storage risks? Professional depositories and high-quality home safes mitigate most practical concerns, provided you verify insurance coverage and audit practices.
Can gold lose value for long stretches? Absolutely. Multi-year sideways or declining periods have occurred before. That history is why allocation size and time horizon matter so much.
Looking Ahead: Why the Conversation Around Gold Keeps Evolving
Monetary policy, fiscal deficits, and shifting geopolitical alliances all influence demand for monetary metals. None of those factors disappears overnight. As long as uncertainty remains part of the economic landscape, gold will likely keep a place in thoughtful portfolios.
The current price of $4,161.54 per ounce simply reflects the latest balance of those forces. Whether that number looks high or low depends entirely on your personal starting point and investment horizon. What matters more is choosing a method of ownership that you can maintain comfortably through the next market cycle.
In the end, gold is not magic. It is a tool. Used with clear eyes and realistic expectations, it can still do the quiet work of portfolio ballast that generations of investors have asked of it. The modest dip from Friday does not change that fundamental role. It simply offers another moment to decide how—or whether—to include the metal in your own plan.
Take the time to match the vehicle to your circumstances. Compare total costs rather than focusing solely on the headline spot price. And remember that the strongest portfolios usually blend several asset classes rather than relying on any single one to carry the load. Gold can be a valuable piece of that blend when approached with patience and practicality.