
Have you ever watched the markets react in a way that seems to defy pure logic? One day inflation numbers come in hotter than anyone expected, traders start pricing in another rate hike with near certainty, and yet the 10-year Treasury yield decides to slide lower. That exact puzzle played out overnight, and it left more than a few seasoned investors scratching their heads. In my experience following these cycles, these moments of disconnect often reveal the real undercurrents moving capital right now.
Why The Latest Inflation Readings Changed The Game
The Producer Price Index, or PPI, measures price changes for goods and services sold by producers. It offers one of the clearest early windows into upstream cost pressures before they fully hit consumers. The most recent figures arrived hotter than expected, and they pointed to something important: inflationary heat is no longer confined mainly to the energy sector. Those higher costs are beginning to spread into the broader real economy.
At the same time, another key gauge closely watched by policymakers is also flashing warning signs. Consensus forecasts from major institutions suggest the core Personal Consumption Expenditures price index, better known as core PCE, is expected to climb 0.32 percent month over month for September. That would mark a clear acceleration from the previous 0.25 percent reading. When both the published PPI numbers and the upcoming PCE estimates point in the same direction, market conviction hardens quickly.
I’ve found that traders rarely need much encouragement once two major inflation metrics start aligning. The result this time? The probability of at least one more Federal Reserve rate increase before year-end has climbed above 90 percent according to market pricing tools. Some economists even believe the next policy meeting could already be live for action.
The numbers just cry out for them taking action. I think the current meeting window should stay firmly on the table.
– Former regional Federal Reserve bank president
Another global chief economist echoed a similar view, noting that political calendars such as midterms rarely remove genuine inflation concerns from the decision-making process. When data speaks this loudly, policymakers tend to listen.
The Strange Behavior Of Treasury Yields
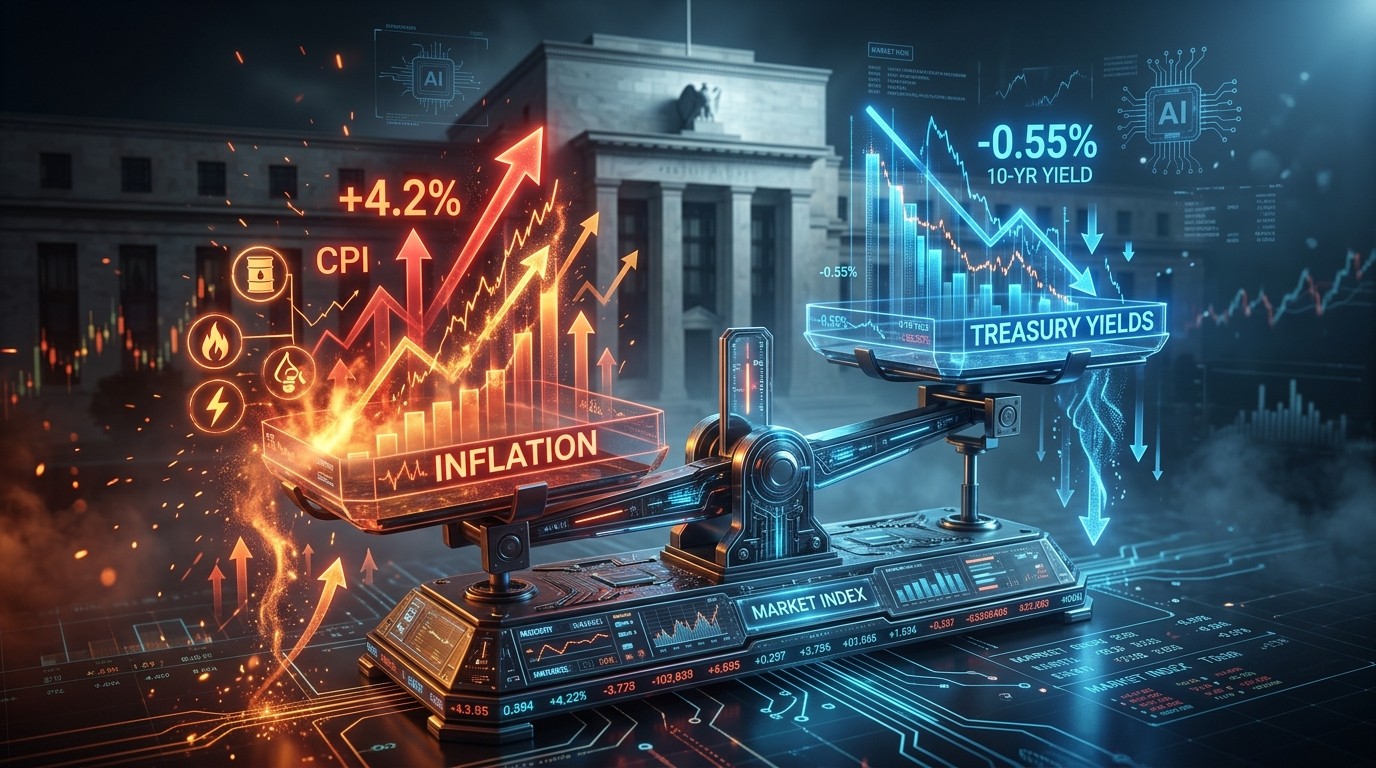
Normally, rising expectations for higher policy rates push short-term interest rate forecasts upward and drag the benchmark 10-year Treasury yield higher as well. Overnight, the opposite occurred. The 10-year yield slipped to 5.04 percent, its lowest point in three weeks, before settling near 5.09 percent. That kind of reverse move rarely happens by accident.
Analysts point to growing unease around financing risks for companies heavily involved in artificial intelligence development. Investors appear to be reassessing how sustained higher borrowing costs might affect both overall economic growth and the ability of firms to service expanding debt loads. In that environment, safe-haven demand temporarily outweighed pure inflation fears. Capital rotated out of riskier assets and into Treasuries, pulling yields lower even as rate-hike odds stayed elevated.
You get a very significant dependency in the GDP data on AI at the moment, and that is likely why rates are going down. If the AI trade slows, growth expectations soften too.
– Chief economist at a major global investment firm
Perhaps the most interesting aspect is how concentrated some recent growth contributions have become. When one sector carries outsized weight in the expansion narrative, any hint of slowdown can shift rate expectations faster than traditional inflation data alone would suggest.
The Widening Scissors Gap And Corporate Earnings Risk
Another development worth close attention is the expanding gap between year-over-year PPI and CPI growth rates. Right now that difference sits at roughly 2.6 percentage points, with producer prices rising meaningfully faster than consumer prices. Industry observers warn that if companies cannot pass higher input costs through to end customers in a timely way, profit margins face real pressure.
Energy-intensive industries and transportation-related sectors look particularly exposed. Higher producer costs that stay stuck upstream eventually show up in earnings reports, and markets have a habit of punishing those surprises. In my view, this scissors gap deserves more attention than it sometimes receives because it can act as an early signal of margin compression long before it appears in aggregate profit numbers.
Let me break down a few practical implications investors might want to keep in mind:
- Companies with limited pricing power may struggle first when input costs rise faster than selling prices.
- Sectors that rely heavily on energy or logistics inputs face the most immediate margin risk.
- Firms that have already locked in longer-term supply contracts may enjoy temporary protection.
- Any further widening of the PPI-CPI gap could force more aggressive cost-cutting or delayed investment plans.
These dynamics do not guarantee negative outcomes, but they do raise the stakes for careful stock selection in the months ahead.
How Markets Are Pricing The Next Policy Move
With the probability of another rate increase before year-end now above 90 percent, short-term rate expectations have adjusted accordingly. Yet the bond market’s recent preference for safety shows that growth concerns can still dominate pure inflation arithmetic on any given day. That tension creates both risk and opportunity.
I’ve watched similar episodes in previous cycles. When inflation data and growth worries pull in opposite directions, volatility often rises while directional conviction temporarily softens. Traders who stay flexible tend to navigate these stretches more successfully than those locked into a single narrative.
Consider the practical sequence many participants are now weighing:
- Confirm whether the hotter PPI reading proves to be a one-off or the start of a broader second-wave pressure.
- Watch the upcoming core PCE print for confirmation or contradiction of the current forecasts.
- Monitor credit spreads and equity valuations in AI-related names for signs of financing stress.
- Track the 10-year yield’s ability to hold or break recent ranges as a signal of shifting safe-haven demand.
None of these steps is particularly glamorous, yet they form the core of disciplined risk management when data and market pricing start to diverge.
Broader Implications For Growth And Investment Strategy
The current environment forces a more nuanced conversation about growth sustainability. Heavy reliance on one high-profile sector can deliver strong headline GDP numbers, but it also concentrates risk. If financing conditions tighten further or investor appetite for large capital projects cools, the knock-on effects could extend well beyond the technology complex.
At the same time, higher policy rates for longer would continue to reshape the relative attractiveness of different asset classes. Cash and short-duration fixed income have already regained appeal for many portfolios. Longer-duration bonds, by contrast, remain more sensitive to both inflation surprises and growth disappointments.
One angle I keep returning to is the potential impact on corporate capital allocation. When borrowing costs stay elevated and margin pressure builds, management teams often slow hiring, delay expansion, or prioritize balance-sheet strength over growth initiatives. Those decisions feed back into the broader economy with a lag, which is why the current data mix feels particularly consequential.
What History Suggests About Similar Setups
Previous periods that combined sticky upstream inflation with concentrated growth drivers often produced choppy markets rather than clean trends. Investors who waited for perfect clarity frequently missed the more gradual shifts already underway. Those who treated the data as evolving rather than definitive tended to adjust portfolios more smoothly.
That does not mean abandoning risk assets entirely. It does mean paying closer attention to balance-sheet quality, pricing power, and the ability of individual companies to absorb higher input costs without sacrificing too much margin. In other words, selectivity matters more than broad market exposure when the scissors gap between producer and consumer prices remains wide.
A simple framework many experienced managers use looks something like this:
| Factor | Favorable Signal | Caution Signal |
| PPI trend | Moderating sequential gains | Persistent acceleration |
| Core PCE | In line or cooler than expected | Clear acceleration |
| Treasury yields | Stable or gently rising with growth | Sharp drops driven by risk aversion |
| Sector leadership | Broadening participation | Heavy concentration in one theme |
Keeping an eye on these four columns helps cut through the daily noise and focus on the variables that actually drive medium-term outcomes.
Practical Considerations For Portfolio Positioning
So where does that leave everyday investors and professional allocators alike? First, acknowledge that the probability of another rate move before year-end has become the base case for markets. Fighting that consensus requires a strong contrary data catalyst that has not yet appeared. Second, recognize that growth concerns, especially those tied to financing conditions in high-profile sectors, can still exert downward pressure on yields even when inflation remains uncomfortable.
I’ve found it useful to think in terms of scenarios rather than single-point forecasts. One plausible path involves a further policy tightening followed by gradual cooling in both inflation and growth. Another involves sticky costs that force rates higher while growth disappoints more sharply, producing a more challenging environment for risk assets. Preparing for both possibilities usually means maintaining some dry powder and avoiding excessive leverage.
Liquidity management also takes on greater importance. When markets swing between inflation fear and growth fear within the same week, the ability to adjust positions without large transaction costs becomes a genuine advantage. That favors higher-quality holdings and more liquid markets over obscure corners of the investment universe.
Looking Ahead To The Next Data Releases
The immediate calendar will remain data-dependent. The forthcoming core PCE reading will either reinforce the current hawkish tilt or introduce fresh doubt. Any meaningful downside surprise could quickly recalibrate rate-hike odds, while confirmation of the hotter forecast would likely solidify expectations further. Beyond that single print, markets will continue monitoring corporate commentary for early signs of margin pressure or financing caution.
Energy prices and logistics costs will also stay in focus. Because the latest PPI strength appeared to broaden beyond pure energy, follow-through in those categories would strengthen the case that upstream pressures are becoming more entrenched. Conversely, any rapid cooling would ease some of the current tension.
Ultimately, the interplay between inflation persistence, policy responsiveness, and growth concentration will shape market direction in the coming weeks. The overnight drop in Treasury yields despite elevated rate-hike probabilities already shows how quickly sentiment can pivot when growth concerns surface. Staying alert to both sides of that equation remains essential.
In the end, these moments of apparent contradiction often prove more informative than periods of clean consensus. They force investors to confront the real trade-offs embedded in the current economic backdrop. Hotter producer prices, rising core PCE forecasts, near-certain expectations of another policy move, and simultaneous safe-haven demand for Treasuries all coexist right now. Sorting through that mix requires patience, flexibility, and a willingness to update views as fresh evidence arrives. That approach has served careful market participants well across many previous cycles, and it remains equally relevant today.
The path forward will not be linear. Inflation metrics can surprise in either direction, growth contributions from leading sectors can shift, and policy makers will respond to the evolving picture rather than any single data point. Keeping perspective on the broader narrative while remaining responsive to the latest numbers offers the most practical way to navigate what comes next. For now, the message from the latest producer price figures is clear enough: upstream cost pressures have not disappeared, and markets are adjusting accordingly, even if the adjustment process itself continues to produce occasional surprises.