
Have you noticed how quiet some neighborhoods have become lately? Fewer open-house signs, slower traffic on weekends that used to buzz with potential buyers, and conversations at dinner parties that keep circling back to the same uneasy topic. The housing market is sending some unmistakable signals right now, and they arrive at a particularly awkward moment. Just as policymakers debate whether another round of interest-rate increases is necessary, fresh numbers paint a picture of cooling demand, stalled construction, and affordability pressures that refuse to ease.
A Market Under Pressure While Policy Debates Heat Up
Recent figures for September delivered a series of disappointments that went well beyond what most analysts had anticipated. Pending sales, housing starts, and building permits all moved in the wrong direction, some by wide margins. These are not isolated soft spots. They form a pattern that suggests deeper challenges ahead, especially if borrowing costs climb further.
I have been following housing cycles for a long time, and the current combination feels different. We have elevated mortgage rates sitting above seven percent, a persistent shortage of available homes, and an inflation fight that shows little sign of wrapping up cleanly. The tension between supporting a weakening sector and keeping broader price pressures in check is becoming harder to ignore.
Pending Sales Hit Historic Lows
One of the clearest red flags came from the forward-looking measure of homes under contract. The index dropped more than seven percent in a single month and now stands more than eleven percent below the level recorded a year earlier. That reading marks the weakest point in records stretching back more than two decades. Market expectations had called for only a modest pullback. The actual shortfall was dramatic.
Pending sales matter because they preview future closed transactions. When that pipeline shrinks this sharply, it usually means fewer completed deals in the months ahead. Buyers appear to be stepping back, either because monthly payments no longer fit their budgets or because they simply prefer to wait for clearer signals on rates.
Market conditions weakened in September due to fast-rising mortgage rates. Although job growth and income gains can support home purchases, housing affordability is more affected by changes in mortgage rates.
That observation captures the core issue. Income growth has not kept pace with the jump in borrowing costs. A rate that sat near three percent not long ago now sits more than double that level for many new loans. The difference in monthly payments is large enough to push a substantial share of would-be buyers to the sidelines.
Housing Starts and Permits Tell a Similar Story
Construction activity also slowed more than expected. Privately owned housing starts fell over five percent on a seasonally adjusted annual basis, far steeper than the near-flat reading many had forecast. Building permits, which offer an early glimpse of future construction, edged lower instead of rising. Single-family permits reached their lowest point in several years.
Builders are responding rationally to the environment they face. Higher financing costs raise the expense of holding land and materials. Softer buyer traffic reduces the incentive to break ground on speculative projects. Sentiment among builders has already sunk to levels not seen in more than a decade. That mood rarely improves until rates or demand show clearer signs of relief.
In my view, the permit numbers deserve special attention. They tend to lead actual starts by a few months. A continued slide here would point to even softer construction numbers later this year and into next. Residential investment, already expected to contract in coming quarters, could weaken further if the current trajectory holds.
Why Mortgage Rates Matter More Than Ever
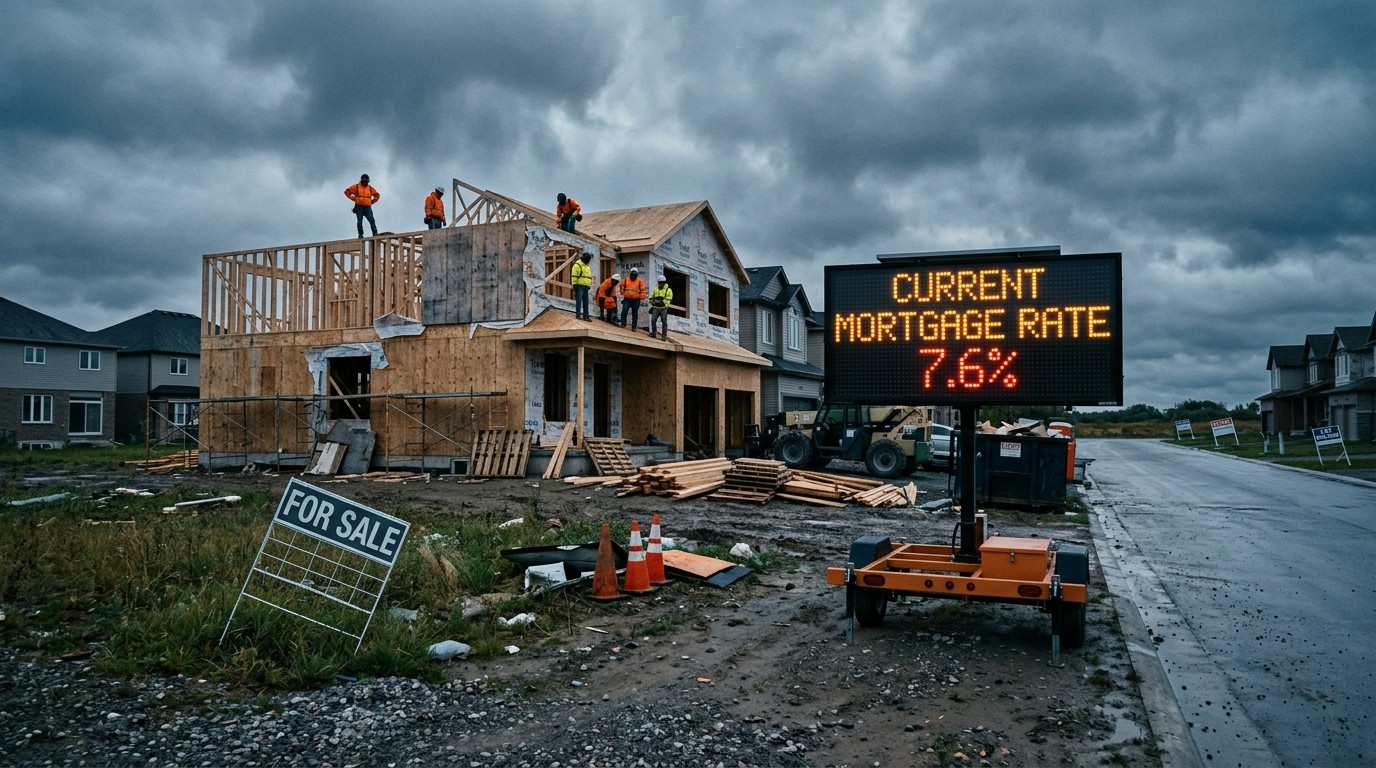
The average rate on a thirty-year fixed mortgage spent most of September above seven percent and finished the month near seven and a half. Five years earlier the same loan cost roughly half as much. That shift has rewritten the math for almost every household considering a purchase.
Consider a simple example. On a median-priced home, the difference between a three-percent rate and a seven-and-a-half-percent rate can add hundreds of dollars to the monthly payment. For many families the higher figure simply does not fit. Some stretch and accept the cost. Others postpone or drop out of the market entirely.
There is also a powerful lock-in effect at work. The vast majority of existing mortgage holders enjoy rates well below today’s levels. More than nine out of ten borrowers sit below the current market rate, and a large share enjoy rates two full percentage points lower. Moving would mean giving up that advantage and taking on a much higher payment. As a result, inventory stays tight even as demand softens. Sellers stay put. Buyers face limited choices and elevated prices relative to incomes.
The Policy Dilemma Facing Decision Makers
Under ordinary circumstances a cooling housing sector might prompt easier monetary policy. Lower rates reduce borrowing costs and usually revive demand. The present situation is different. Inflation readings remain sticky in several categories, and officials continue to emphasize the need to keep price pressures contained.
Recent wholesale price data showed goods costs accelerating at the fastest pace in years. Investment related to artificial intelligence is also pushing up demand for specialized equipment and components. Policymakers appear to believe that strength in those areas can offset weakness elsewhere, including housing. Whether that calculation proves correct remains an open question.
Markets currently price a high probability of additional rate increases in the months ahead. If those moves materialize, mortgage rates could climb further still. Affordability would deteriorate another notch. Activity that is already soft could slow even more.
I find this trade-off particularly delicate. Housing has long served as both a critical economic engine and a major source of household wealth. Prolonged weakness here tends to ripple outward into related industries, from furniture and appliances to local services. At the same time, allowing inflation to reaccelerate carries its own set of risks that no one wants to revisit.
What the Numbers Suggest for the Year Ahead
Analysts who track these trends closely expect residential investment to decline over the next several quarters. Single-family starts may remain roughly flat near current subdued levels. Existing home sales are projected to stay well below the pace seen before the pandemic, perhaps more than twenty-five percent lower than the 2019 benchmark.
The combination of high rates and the lock-in effect creates a range-bound market. Affordability caps the upside. The long-standing shortage of homes provides a floor that prevents a complete collapse. In the coming year, however, the affordability constraint is expected to dominate. Turnover is likely to stay low. New construction will struggle to gain meaningful momentum.
- Existing homeowners remain reluctant to sell and lose their low rates
- Prospective buyers face monthly payments that strain household budgets
- Builders limit new projects until clearer demand signals appear
- Inventory stays tight even as transaction volumes fall
- Price growth slows but absolute levels remain elevated relative to incomes
One modest source of optimism comes from the observation that mortgage rates have already risen more than the short-term policy rate in recent months. Some market participants believe this overshoot could mean rates are nearing a peak. If that view proves accurate, buyers and sellers who have been waiting might gradually return. History shows that sentiment can shift once people sense that the worst of the rate climb has passed.
Broader Implications Beyond the Housing Sector
Housing does not exist in isolation. When activity slows, the effects spread. Construction employment can soften. Demand for building materials eases. Local governments that rely on property-related fees and transfer taxes feel the pinch. Consumer spending on big-ticket items often linked to moving also tends to cool.
At the same time, the shortage of homes remains a structural reality. Years of underbuilding relative to household formation have left many markets with insufficient supply. That imbalance has helped support prices even as volumes decline. The current environment may prolong the shortage by discouraging new construction precisely when more units are needed.
Perhaps the most interesting aspect is how different segments of the market are responding. Entry-level buyers face the steepest hurdles. Higher-income households still have more options, including the ability to put larger down payments or absorb higher monthly costs. Regional differences also matter. Areas that saw the sharpest price run-ups during the low-rate years are now experiencing more pronounced cooling.
Practical Considerations for Buyers and Sellers
For anyone thinking about a purchase, the current landscape requires careful arithmetic. Running the numbers with today’s rates is essential. Stress-testing the payment against possible further increases makes sense. Some buyers are exploring adjustable-rate options or shorter loan terms, though those choices carry their own risks.
Sellers confront a different set of calculations. Pricing aggressively may be necessary in markets where inventory is starting to accumulate. Offering rate buydowns or other concessions can help bridge the gap for hesitant buyers. Timing also matters. Waiting for a meaningful drop in rates could take longer than many hope.
In my experience, the households that navigate these periods most successfully tend to focus on long-term fit rather than short-term rate timing. A home that works for the next decade or more retains its value even if the purchase moment is less than ideal. Still, stretching the budget to the breaking point rarely ends well.
Looking Further Ahead
The next several quarters will test whether the current softness remains contained or deepens into something more pronounced. Much depends on the path of inflation and the corresponding policy response. If price pressures ease more convincingly, the pressure for additional rate hikes could diminish. Mortgage rates might then stabilize or even edge lower, giving the market room to breathe.
Conversely, if inflation remains stubborn, further policy tightening becomes more likely. In that scenario the housing sector would face additional headwinds. Activity could stay subdued for longer, and the adjustment in prices and volumes might become more noticeable.
Builders and developers will watch the data closely. Many have already scaled back plans. A sustained period of weak permits and starts would reinforce that caution. At the same time, the underlying need for more housing has not disappeared. Any eventual easing in rates could unlock a meaningful rebound once confidence returns.
I keep returning to the idea that housing markets rarely move in straight lines. Periods of excess give way to periods of restraint. The current environment feels like a restraint phase driven primarily by the cost of credit. How long it lasts will shape the opportunities available to the next generation of buyers and the health of the broader economy.
Key Takeaways From the Latest Data
Several points stand out clearly. Pending sales have reached an all-time low in the modern data series. Housing starts and permits both disappointed by wide margins. Mortgage rates remain elevated and continue to weigh heavily on affordability. The majority of existing borrowers are locked into far lower rates, limiting the flow of inventory. Policymakers face a genuine conflict between supporting a soft sector and containing inflation. Outlooks for the year ahead point to continued soft activity rather than a quick rebound.
None of these developments exists in a vacuum. They interact with employment trends, wage growth, consumer confidence, and the broader cost of living. The housing market has always been sensitive to interest rates, but the magnitude of the recent rate climb has amplified that sensitivity.
| Indicator | Recent Change | Implication |
| Pending Sales | Sharp monthly drop, record low | Weaker closed sales ahead |
| Housing Starts | Decline well beyond expectations | Softer construction pipeline |
| Building Permits | Slight decline versus expected gain | Limited near-term recovery |
| Mortgage Rates | Above 7 percent for most of month | Affordability under pressure |
| Builder Sentiment | Multi-year lows | Cautious approach to new projects |
The table above summarizes the main signals. Each one points in a similar direction. Taken together they suggest a market that is adjusting to a higher cost of capital and is likely to remain under pressure until that cost moderates or incomes catch up more meaningfully.
Why This Moment Feels Different
Previous housing slowdowns often followed periods of overbuilding or speculative excess. The current episode arrives after years of underbuilding in many regions. Inventory remains historically tight in a large number of markets. That structural shortage provides a cushion that was missing in earlier cycles. Prices may soften in some areas, yet a broad collapse appears less probable than a prolonged period of low transaction volumes.
Another distinguishing feature is the speed of the rate rise. Households had grown accustomed to historically low borrowing costs. The adjustment to a higher plateau has been abrupt. Psychological factors play a role. Many buyers simply refuse to accept payments that feel double what their friends or relatives paid only a few years earlier.
Technology and remote-work patterns have also reshaped demand in subtle ways. Some households still enjoy greater geographic flexibility. Others have returned to office-centric lifestyles that prioritize specific locations. These shifts interact with the rate environment in ways that are still playing out.
A Cautious Path Forward
For now the most realistic expectation is continued caution. Buyers will remain selective. Sellers will need to be realistic about pricing and concessions. Builders will keep a tight rein on new starts until demand stabilizes. Policymakers will continue to weigh housing weakness against the broader inflation picture.
The data released this week do not signal an immediate crisis. They do, however, flash clear warning signs that the adjustment process is still underway. Ignoring those signals would be unwise. Paying close attention to the next several months of reports will offer the best guide to whether the market finds a bottom or faces further deterioration.
Housing has always reflected the intersection of policy, credit conditions, and household finances. Right now that intersection looks particularly complicated. The coming period will reveal whether the current pressures remain manageable or whether they begin to feed more noticeably into the wider economy. Either way, the latest numbers have made one point unmistakable: the housing market is no longer operating under the conditions that supported the previous boom, and the transition is proving more challenging than many had hoped.
Staying informed, running the numbers carefully, and maintaining realistic expectations remain the most practical approaches for anyone with a stake in the outcome. The warning signs are flashing. How the market and policymakers respond will shape the next chapter for homebuyers, homeowners, and the communities that depend on a healthy flow of housing activity.