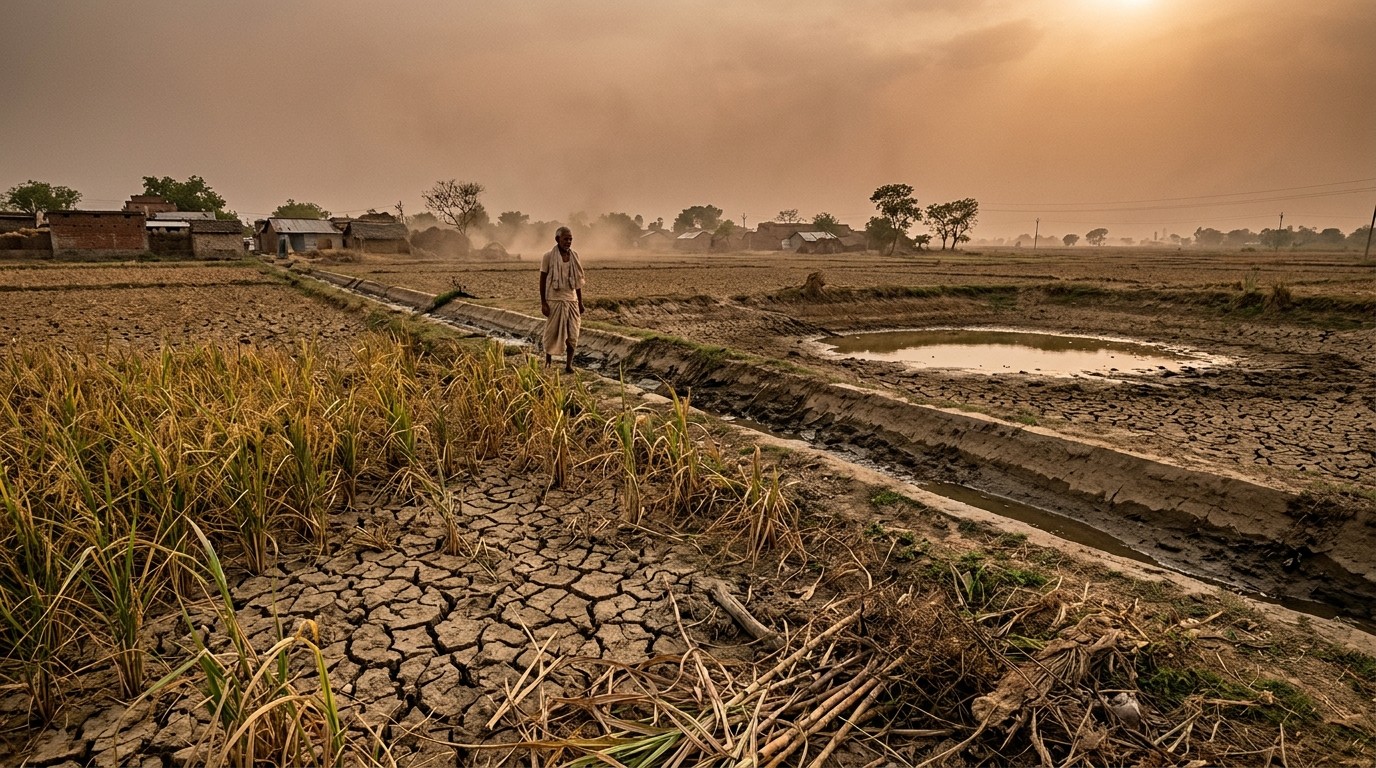

I keep coming back to a number that does not look dramatic until you sit with it. Between June and September, the stretch that decides whether much of India’s food system eats well or merely scrapes by, rainfall landed at its weakest level in more than a decade. Fourth-lowest since 2001. Thirteenth-driest since 1901, if the national weather office is reading the gauges correctly. That is not a bad week. That is a season. And seasons, in a country where nearly half the workforce still draws a living from the land, have a way of showing up later in grocery bills, tractor yards and election rallies.
Perhaps the most interesting aspect is how quietly this arrived. Growth still looks sturdy on the headline charts. Foreign money has already been walking out of equities for other reasons. Energy prices are jumpy. Trade talks with Washington have gone flat. Then the weather turned, and a foreign minister stood in New York and said the quiet part out loud: put a super El Niño next to fertilizer shortages tied to wars, and a major food crunch is not a hypothetical. It is a calendar item.
I have found that markets are slow to price a drought until the second harvest fails. The first one gets explained away as a regional hiccup. The second one rewrites inflation prints. India is somewhere between those two moments right now.
Why This Monsoon Is Not Just Another Dry Spell
India feeds close to 1.5 billion people from its own fields and still ranks among the world’s heavy exporters of rice and sugar. Farms are only about 17 percent of output, which tempts city analysts to shrug. They should not. Those same farms support roughly 46.1 percent of the workforce. They also hold down supply-side inflation and bankroll a huge slice of everyday spending. When the rain fails, the shock does not stay rural. It migrates.
A super El Niño is the Pacific’s way of rearranging who gets the clouds. Warm water piles up in the eastern Pacific, the usual monsoon engine over the Indian Ocean sputters, and the subcontinent can end up with patchy, late, or simply insufficient rain. This year the pattern did not tease. It delivered a deficit large enough that several research desks revised their farm assumptions after the season closed, not before.
In my experience, the phrase “below normal” gets used so often that readers stop hearing it. This time the deficit looks wider than early forecasts suggested. A multilateral lender said as much this week: agricultural output and rural demand are likely to take a hit, while food inflation adds to pressure already coming from energy. That is three problems sharing one cause.
A weak monsoon does not announce itself in the growth print. It shows up first in empty canals, then in thinner pay packets, then in the price of the evening meal.
Field note from a season that refused to cooperate
Political opponents have already blamed the government for moving too slowly. That argument will run for months. What matters for households and investors is narrower. Did the water arrive where the crops needed it, and is there enough left in storage for the cooler months? On both counts, the early answers are uncomfortable.
The Rainfall Record, Without The Spin
Local reporting put the June-to-September total at the lowest in more than ten years. Official climatology placed it among the driest stretches since records began in 1901. Either framing is enough. A rain-fed farm system does not get a do-over in October. The kharif season, the big summer planting window, is already written.
Key farm states did not share the pain evenly, which is how these stories always go. Maharashtra, Andhra Pradesh, Punjab and Haryana have pockets that analysts described as extreme drought conditions. A national average can hide a ruined district. A ruined district can still move a national price if it grows something the rest of the country eats every day.
Think of the monsoon as a single paycheck for millions of small plots. Miss it, and there is no overtime shift in November that makes the family whole. Irrigation helps on paper. In practice, a large share of acreage still waits on the sky. When the sky shrugs, wells drop, pumps run longer, diesel bills climb, and the margin on a bag of grain disappears before it reaches the mandi.
- Lowest June-September rainfall in more than a decade, by local tallies
- Fourth-lowest seasonal total since 2001
- Thirteenth-driest since 1901, on the meteorological record
- Deficit wider than many early-season models had penciled in
- Uneven pain, with severe dry pockets in major producing states
Short version: the rain did not fail everywhere, but it failed in enough places that pretending this is a normal wobble feels like wishful accounting.
Reservoirs And The Winter Crop Gamble
By the end of September, reservoirs sat about 28 percent short of full capacity, according to a note from a major brokerage. That gap is the quiet part of the drought. Summer crops drink what falls. Winter crops, the rabi season, drink what was stored. If the tanks are low in October, wheat, mustard, chickpea and a long list of vegetables start the season already behind.
I have watched this movie in other years. Officials talk up groundwater. Farmers talk about the canal that did not fill. Both can be true. A 28 percent shortfall is not a rounding error. It is a constraint on how much acreage gets a second chance.
Hydropower feels it too, though that rarely makes the food headlines. Lower reservoir levels mean less cheap electricity in some regions and more reliance on coal or imported fuel just as global energy markets are already twitchy. The drought tax shows up on the power bill and the food bill at the same time. Households do not experience those as separate stories.
Winter sowing decisions get made in a narrow window. Delay the planting because the soil is still dust, and yields slip even if late rain arrives. Plant anyway and pray, and input costs are sunk before the crop has a chance. Either path squeezes farm incomes. That is the channel that later shows up in soap, two-wheelers and entry-level cars.
Sugar, Rice And The Export Lever
India is the world’s second-largest producer of sugarcane. The industry is not a side plot. It supports something on the order of five crore farmers and about five lakh factory workers, a web of livelihoods that runs from the field to the crushing mill to the truck that hauls bagasse. Cane likes water. A weak monsoon and dry spells cut yields and sucrose recovery, which is the unglamorous metric that decides how much sugar comes out of a ton of stalk.
Rice sits in a similar political category. India is a top exporter. When domestic prices twitch, export curbs appear with very little ceremony. That protects the home plate and annoys buyers from West Africa to Southeast Asia. It also tells you the government is already nervous. Export policy is a pressure gauge. When it tightens, the domestic market is not as calm as the press notes suggest.
Here is the awkward trade-off. Hold supply at home and you cap local food prices for a while. You also shrink farmer realizations if procurement does not fully replace the export bid. Release supply and urban inflation cools while rural cash flow improves, until stocks look thin and the cycle reverses. Neither choice is free. A dry year just makes the menu shorter.
Sugar has an extra wrinkle. Mills, ethanol blending targets and state-advised cane prices all pull on the same stalk. A poor recovery rate means more cane is needed for the same sugar, which raises costs just as global prices may or may not cooperate. Mills that were comfortable last season can look stretched this one. Farmers waiting on arrears notice before economists do.
| Pressure point | What a dry year does | Who feels it first |
| Rice | Tighter domestic balance, export curbs more likely | Urban buyers and overseas importers |
| Sugarcane | Lower yields and weaker sucrose recovery | Mill workers and cane growers |
| Reservoirs | Less water for rabi sowing and power | Winter-crop farmers, some grids |
| Fertilizer | Scarcer supply and higher delivered cost | Smallholders with thin cash buffers |
| Rural cash | Slower wage growth and weaker crop sales | FMCG, two-wheelers, entry cars |
Fertilizer Shortages Piled On Dry Soil
Weather would be enough. It is not arriving alone. India’s foreign minister warned that significant fertilizer shortages are already in play because key producers in the Middle East and Russia have been knocked around by conflict. Add a super El Niño, he said, and a major food crisis is coming in the months ahead. Energy shocks and the rush of money into safe harbors have been, in his words, very stressful for economies of the Global South.
Fertilizer is not a luxury input. Skip a dose of urea or potash and the plant does not negotiate. Yields drop. Protein content can drop. The farmer who already spent on seed and diesel eats the loss. Subsidy schemes cushion the sticker price in normal years. They do not conjure tons that were never shipped. A shortage is a physical problem wearing a policy costume.
I’ve found that people outside agriculture treat fertilizer as a line item. On a two-acre plot it is a decision between this season’s crop and next month’s school fees. When global supply tightens, the queue at the cooperative society gets longer, the black-market premium appears, and the farmer who arrives late plants anyway and hopes. Hope is not a nutrient.
The combination matters more than either shock alone. Dry soil needs careful nutrition to produce anything decent. Missing nutrients on dry soil is how a mediocre year becomes a bad one. That is the stack India is looking at: thin rain, thin tanks, thin fertilizer bags.
Inflation That Has Already Been Climbing
Consumer inflation has been rising for ten straight months. It crossed the central bank’s medium-term target of 4 percent in August, even while growth still looked resilient. That sequence is familiar and unpleasant. The economy can post a decent GDP number while the household basket gets heavier. Statisticians call that a divergence. Families call it the weekly shop.
Food is the volatile piece. A spike in vegetables can fade in six weeks. A short cereal or pulse crop does not. Once the rabi window is compromised, the inflation impulse lasts into the following summer. Energy prices sit on top of that, so the central bank is not dealing with a single naughty category. It is dealing with a stack.
On Wednesday the Reserve Bank of India raised interest rates for the first time since 2023. The benchmark repo rate moved up 25 basis points to 5.50 percent, a one-year high. Several major central banks have been tightening for the same reason: inflation that refuses to drift back to target on its own. India joined that club later than some, which tells you how long policymakers hoped the food spike would cool by itself.
A quarter-point hike will not make it rain. It can keep expectations from unanchoring, and it can lean against a weaker currency that would make imported fuel and fertilizer even dearer. The cost is real. Dearer credit lands on small businesses and on rural borrowers who were already watching crop cash shrink. Policy is choosing the smaller bruise. There is no bruise-free option this season.
Rate hikes do not fill a reservoir. They only stop the price shock from becoming a habit.
The Rural Engine That City Balance Sheets Forget
Rural India is not a sentiment. It is a sales channel. Consultancy data puts rural areas at nearly 40 percent of fast-moving consumer goods sales. That is soap, tea, biscuits, detergent, the unglamorous stuff that multinationals love because it repeats. When farm cash slows, those repeats slow with it. Not always in the same month. Usually within two quarters, once savings and informal credit run thin.
An Asia-Pacific economist at a large data firm put it bluntly. The rural economy is likely to slow materially through 2026 and 2027 as drought conditions, below-normal monsoon rain and depleted reservoirs cut crop yields and farm incomes. Broader indicators still look resilient. Early stress is already visible: tractor sales have cooled, and demand for rural employment support programs has started to rise.
That second signal is the one I watch. Workfare schemes are a pressure valve. When more people show up asking for a public shift, private farm work is not paying enough, or is not there. It is not a collapse. It is a tell. Collapses get the headlines. Tells get ignored until the FMCG earnings call.
Morgan Stanley’s desk sees agricultural gross value added growing about 1.6 percent in the financial year ending March 2027, well under the 3.5 percent pace of the prior three years. Another forecast house sees something closer to 1.9 percent. Either way, the farm sector stops being a quiet support and becomes a drag. For an economy sold to the world as the fastest-growing large one, a drag in the sector that employs nearly half the workforce is not a footnote.
Companies That Live On Village Spending
Rural demand is not abstract for Hindustan Unilever, Colgate-Palmolive’s India arm, Nestle’s local listed business, or automakers such as Maruti Suzuki and Hyundai’s India operation. Annual reports and earnings calls have said this for years. Volume growth in the hinterland is the swing factor when urban demand is already mature. A dry year does not zero those businesses out. It changes the slope.
Staples usually hold up better than discretion. People still buy the small pack of detergent. They skip the larger pack, trade down a brand, or delay the motorcycle. Entry-level cars feel it later than tractors, but they feel it. Dealers in district towns notice the footfall before the national sales chart does.
What I keep telling anyone who asks is this: do not read a single strong urban mall weekend as proof the consumer is fine. India has two consumers. One is salaried, city-based, and mostly insulated from a failed monsoon. The other is paid in crop cycles and daily wages. The second one is larger than the marketing decks admit, and this year the second one is the one under strain.
- Watch tractor and two-wheeler registrations in deficit districts, not national averages alone
- Listen for volume, not just price-mix, on staples earnings calls
- Track rural wage data against food inflation, because real pay is the spending fuel
- Note any rise in demand for public rural employment schemes
- Check whether companies start guiding to a slower second half rather than a rebound
None of those are dramatic. Together they describe a slowdown you can still get ahead of, if you are willing to look past the national GDP headline.
Growth That Still Looks Fine, Until It Does Not
This year was already crowded with headwinds before the clouds failed to show. Global energy shocks. Trade uncertainty with the United States. Record-scale exits by foreign investors from local equities. The super El Niño is the latest item on a list that did not need another item.
Resilience so far is real. Services, public capex and urban consumption have carried a lot of the load. The risk is composition. An economy can grow while its largest employer stagnates, and the political and inflation consequences arrive on a delay. Analysts who mark India as relatively sheltered in Asia are not wrong about buffers. They may be early in assuming those buffers are costless.
Policy buffers exist. Grain stocks, subsidized food distribution, fuel tax tweaks, and the ability to restrict exports all give New Delhi tools that poorer neighbors lack. Using them has a price. Export curbs annoy partners. Subsidy bills widen the fiscal gap. Rate hikes cool the very investment story foreign money was buying. Buffers are not free inventory. They are choices with receipts.
A simple way to hold the year in your head:
  Rain shortfall  ->  thinner harvest
  Thin harvest    ->  higher food prices
  Higher prices   ->  tighter policy
  Tighter policy  ->  slower rural cash
  Slower cash     ->  softer volume growth
That chain is not destiny. A surprise burst of late rain, a smooth fertilizer delivery, or a sharp drop in global energy prices could interrupt it. Betting the year on an interruption is a different kind of forecast. It is hope with a spreadsheet.
The Rate Move And What It Cannot Fix
The repo rate at 5.50 percent is not tight by the standards of 2022. It is a signal. The monetary authority has decided that waiting for food inflation to mean-revert is no longer the base case. Markets that had priced a long pause will need to redraw the path. Borrowers who had assumed the easing cycle was merely paused will feel the difference in the next reset.
Food-heavy inflation is a nasty target for a central bank. Higher rates do little for onion prices and a lot for mortgage demand. The defense is indirect: a firmer currency, anchored expectations, and less room for a wage-price loop if urban services start chasing food. It is a blunt tool used because the precise tool, rain, is not on the policy menu.
Fiscal policy will be asked to do the rest. Higher food subsidies, faster release of stocks, and maybe support for fodder and diesel in the hardest districts. Those measures help. They also land in a year when other claims on the budget have not gone away. Infrastructure, defense, and the interest bill do not shrink because the monsoon misbehaved.
If I had to rank the responses, I would put physical supply management above rhetoric. Opening procurement centers on time, moving fertilizer to deficit blocks before sowing, and keeping the public distribution system stocked will matter more than any speech about resilience. Households do not eat narratives.
Trade Talks That Are Going Nowhere Fast
External pressure is not taking a season off. The U.S. trade representative signaled that a deal with India is not imminent, even after a call between the two leaders. Washington and New Delhi are still haggling over the finer points of an agreement that markets have been waiting on for months. India’s finance minister has been plain: talks have reached a plateau, and there is little room for giving and taking.
A stalled trade file is not the drought. It is the backdrop that makes the drought more expensive. If tariff uncertainty lingers, exporters in textiles, gems, engineering goods and farm products plan smaller. Foreign investors who were already leaving equities get one more reason to wait. A food shock plus a trade impasse is how a domestic weather event becomes a balance-of-payments mood.
Currency is the hinge. A softer rupee raises the local cost of oil and fertilizer just as domestic food supply is tight. The rate hike leans against that. It does not erase it. Importers of pulses and edible oil, categories India does not fully cover at home, will pass costs through if the exchange rate slips. That is another path from a dry field to a city kitchen.
Food Security And The Unrest Question
A global risk advisory, in a mid-September note, argued that food security risks across South and Southeast Asia are set to rise, and with them the potential for unrest in some of the region’s most exposed economies. India, Indonesia, Pakistan, Bangladesh and the Philippines were named among countries that combine high exposure to a super El Niño with a higher risk that rising prices spill into civil tension.
I am wary of straight lines from onion prices to street protests. India has absorbed ugly food spikes before without the political system coming apart. It has also seen local anger flare when a staple doubles and the local official looks absent. Both histories are true. The useful point is narrower. Food inflation is politically loud in a way that services inflation is not. Governments notice. Opponents notice. That attention can produce useful supply measures or wasteful price controls. Sometimes both in the same month.
The foreign minister’s warning was not aimed only at India. He was describing a Global South problem: energy stress, safe-haven flows, fertilizer disruption, and a climate pattern that does not respect borders. India’s scale makes it both more resilient and more consequential. A supply squeeze here moves world rice trade. A supply squeeze in a smaller neighbor mostly moves that neighbor’s politics. The feedback can still reach Indian markets through migration, sentiment and regional risk premia.
Perhaps the honest read is this. Unrest is not the base case. Complacency is not either. Price spikes in food have a social speed that equity drawdowns do not. Anyone underwriting India risk for the next four quarters should at least write the scenario down.
What The Next Data Prints Can Tell You
Two releases sit close on the calendar. Consumer price data for September arrives around October 12. Wholesale prices for September follow around October 14. Neither will capture the full rabi story. Both will show whether the food impulse is still accelerating or merely sticky. Markets will overreact to the decimal. The trend of ten rising months matters more than one print.
After that, watch sowing progress, reservoir bulletins and fertilizer offtake. Those are not glamorous series. They are closer to the ground than a revised GDP nowcast. If sowing lags in wheat belts and offtake of nutrients stays weak, the 1.6 to 1.9 percent farm-growth forecasts start to look optimistic rather than cautious.
Company commentary will lag the weather by a quarter. That lag is useful. It gives anyone paying attention a window to adjust before the earnings miss is consensus. Rural volume, not urban premiumization, is the line to underline.
A pocket checklist for the next 90 days:
CPI food  |  reservoir fill  |  rabi sowing pace  |  fertilizer arrivals  |  rural wages  |  tractor sales
Households, Farmers And The Narrow Set Of Levers
None of this is advice in the licensed sense. It is pattern recognition. Households in cities can shift a bit of the basket toward items the public system still covers, and they can treat vegetable spikes as temporary until the cereal and pulse numbers confirm otherwise. Rural households have fewer substitutions. A failed plot does not come with a side of remote work.
Farmers who still have a choice on rabi acreage will lean toward crops that tolerate less water, if seed and buyers are available. That shift helps survival and can worsen shortages in the thirstier crops everyone else wanted. Markets then do what markets do. The scarce item gets expensive. The abundant item gets cheap at the farm gate. Income does not automatically heal.
State governments will be tempted to announce loan waivers or bonus payments. Some of that relief is justified. Some of it arrives too late for the sowing window and too broadly to fix the districts that actually dried out. Targeted fodder, timely fertilizer and functioning procurement beat a blanket announcement. I have yet to see a slogan irrigate a field.
How Investors Tend To Misread A Farm Shock
The standard error is to call agriculture 17 percent of GDP and move on. The standard correction is to remember the 46 percent of workers, the 40 percent of staples volumes, and the outsized role of food in the inflation basket the central bank actually reacts to. A small sector in the output tables can be a large sector in the policy reaction function.
Another error is to treat every El Niño as identical. Some fade. Some line up with fertilizer shocks and an already rising inflation trend. This one is lining up. The rate hike is evidence that people inside the system agree, even if they would not put it in those words.
Foreign investors leaving equities are a separate story, driven by valuations, global yields and the trade file. A food-inflation scare can accelerate the exit or, oddly, support domestic defensives if local money rotates into staples. Both can happen. The index will not tell you which. The sector tape will.
For anyone allocating to Indian assets, the practical question is not whether the country “handles” El Niño. It has handled worse. The question is the cost of handling it, and who pays. Exporters pay if curbs return. Borrowers pay if rates stay higher for longer. Rural consumers pay if the harvest is thin. Urban consumers pay at the shop. Shareholders pay if volume growth was the reason they owned the stock.
A Longer Shadow Than One Season
Forecasts already stretch the rural slowdown into 2026 and 2027. That is the part that should bother anyone who thought this was a one-quarter weather trade. Soil moisture, livestock condition, and household savings do not reset on April 1. A bad year leaves less seed money for the next. Debt taken to survive a failed kharif becomes a claim on the following rabi. The drag compounds quietly.
There is a climate-pattern debate underneath the seasonal one. If strong El Niño episodes grow more frequent, the old assumption that a poor monsoon is a rare drawdown stops holding. Insurers, lenders and state budgets built for a one-in-ten event will look undercapitalized for a one-in-four. India has spent heavily on irrigation and rural roads. Those assets help. They do not repeal the Pacific.
I do not think the right conclusion is fatalism. The right conclusion is respect for the channel. Food, fertilizer, reservoirs, rural cash, inflation, rates. Skip a link and the story looks manageable. Keep the links and the year looks tighter than the growth slogan suggests.
What Would Actually Change The Story
A few developments would make this essay age badly, and I would happily take that. Widespread late rain that refills the tanks before peak rabi sowing. A diplomatic pause that loosens fertilizer flows out of the disrupted producing regions. A clear drop in global energy prices that offsets the food impulse. A trade understanding with Washington that steadies the currency and the export mood. Any two of those would turn a material slowdown into a manageable soft patch.
What would make it worse is easier to sketch. Another dry spell in the winter wheat belt. A further jump in oil. Export partners retaliating against food curbs. Local protests that push states into poorly targeted price controls, which then empty the shops. None of that is the base case. All of it has happened somewhere in the region within living memory.
Between those poles sits the dull middle, which is where most years live. Patchy harvest. Sticky food inflation. One more rate move or a long hold. Rural volumes that grow, just not at the rate the models wanted. Companies that talk about “calibrated optimism” on calls. That middle is still a downgrade from the path priced three months ago.
Reading The Season Without The Slogan
India remains a vast producer and a pivotal exporter. That has not changed in one dry monsoon. What has changed is the margin of comfort. Reservoirs a quarter below full, a fertilizer channel snarled by wars, inflation already above target for a stretch, and a central bank that has started hiking again. Add a trade file that the finance minister herself describes as stuck, and the external backdrop is not a cushion. It is another weight.
The rural economy is the transmission belt. When it slows, staples volumes slow, vehicle showrooms in small towns go quiet, and the inflation basket gets harder to steer. Analysts can still be right that policy buffers prevent a crisis in the dramatic sense. Buffers preventing a crisis is not the same as buffers preventing a shock. The foreign minister used the word crisis. The data, so far, supports at least the word stress.
If you are a household, the next few monthly bills are the scoreboard. If you are a farmer, the canal and the fertilizer queue are the scoreboard. If you allocate capital, the scoreboard is a cluster of unfashionable series that will not trend on social media. Rainfall is done talking. The harvest, the tanks and the price index are about to answer.
I keep returning to that seasonal total, the one that does not look dramatic until you place it next to 1.5 billion plates and a workforce that is still, almost half of it, out in the fields. A super El Niño does not need to break India to matter. It only needs to make food dearer, rural cash thinner, and policy tighter at the same time. On the evidence of this monsoon, that is no longer a distant risk. It is the weather we already had.