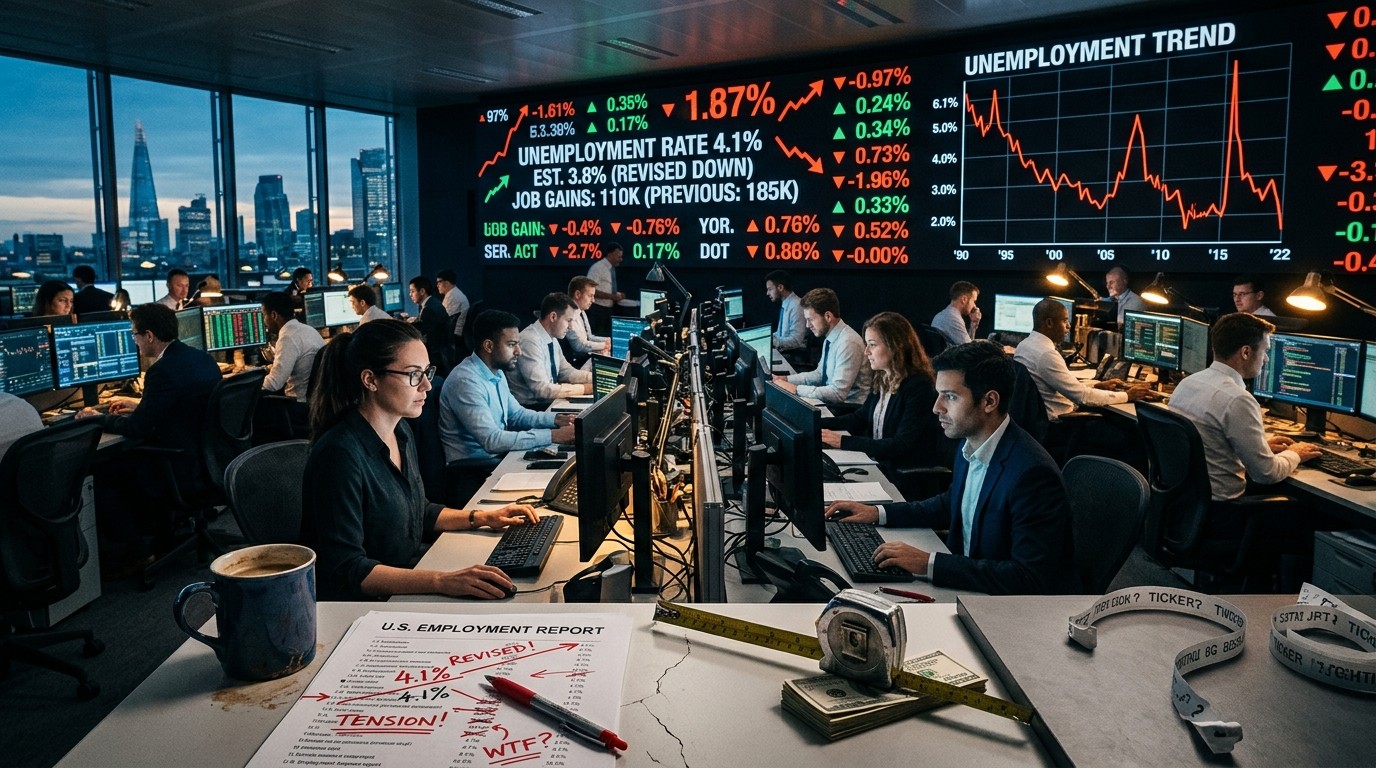

I still remember the first time I sat through a jobs morning with people who actually had money on the line. Nobody was scrolling a feed for fun. The room went quiet in that odd, slightly ridiculous way, as if a single government table could decide whether bonds deserved a rally and whether equities were allowed to breathe. Screens filled. A number landed. Someone swore. Someone else said the revision mattered more than the headline. Both of them were probably right, which is the part that still bothers me.
Can we admit, at least for a minute, that this ritual has become absurd? Highly trained people, desks stacked with models, billions poised to shuffle between cash, bonds, and stocks, all waiting on a release that often arrives looking nothing like the forecast. Then, a month later, a chunk of it gets rewritten. Sometimes the rewrite is larger than the original surprise. We nod, we trade it, and we come back next month as if the instrument had been sharpened overnight.
The Morning That Still Moves Real Money
The monthly employment release is not a curiosity. It is a traffic light for rates, for risk appetite, and for the stories people tell themselves about the economy. A soft print can pull yields lower and give equities an excuse to bounce. A hot print can do the opposite, especially when wage growth looks sticky. The problem is not that markets react. Markets always react to incomplete information. The problem is how much confidence we pretend the incomplete information deserves.
In my experience, the first fifteen minutes after the print are theater. Algorithms fire. Headlines lock in a narrative. Then the humans start arguing about seasonal factors, the household survey, and whether the participation rate did the heavy lifting. By lunch, half the room has already moved on to something less official and, frankly, more useful. Energy prices. Credit. Whatever geopolitical mess is pricing into diesel and shipping. The jobs number lingers mostly as a talking point.
A Print That Missed, Then Got Smaller
Take a recent release that landed well under the street’s guess. Consensus sat near 90,000. The headline came in around 29,000. That gap alone is enough to jolt rates. Then the prior month was marked down by roughly 60,000 after an initial reading near 55,000. Private payrolls told a similar story: about 46,000 this time, with the previous estimate cut from something like 127,000 down toward 89,000. You can call that a cooling labor market. You can also call it a measurement system that keeps handing out drafts.
The three-month average ended up near 51,000, roughly where it had been. That is the kind of line people grab when they want calm. Averages smooth noise. They also hide the fact that each building block was shaky. If every brick in the wall has been recut, the wall can still look straight from the sidewalk. I would not lean on it.
A jobs headline is a first sketch. Treating it like a finished portrait is how desks get surprised twice.
Hourly earnings eased, which soothes anyone watching wage-driven inflation and frustrates anyone trying to cover rent. The unemployment rate ticked up a tenth, helped along by a two-tenths rise in participation. Underemployment actually slipped. On paper, that mix is not a disaster. More people looking, a slightly higher jobless rate, a bit less hidden slack. The catch is the source. Much of that color comes from the household survey, which in the same month suggested something on the order of 406,000 jobs added. One survey whispers. The other shouts. We are asked to average the whisper and the shout and call it truth.
Two Surveys, Two Economies
The establishment survey counts payrolls at firms. The household survey calls people and asks about work. They are built differently, sampled differently, and revised on different clocks. Gaps between them are normal. Gaps this wide are a warning label. When one series says the month was soft and the other says hundreds of thousands of jobs appeared, the honest sentence is not “the labor market is fine” or “the labor market is breaking.” The honest sentence is “we do not know yet.”
Perhaps the most interesting aspect is how rarely that sentence survives contact with a trading screen. A desk needs a number. A commentator needs a plot. A model needs an input. So the messy middle gets compressed into a single arrow: risk-on or risk-off. I have found that the compression is where most of the later embarrassment lives.
- The payroll survey is broad, but early readings are provisional and often revised.
- The household survey drives the unemployment rate, yet its monthly swings can be wild.
- Participation can lift the jobless rate even when hiring is not collapsing.
- Underemployment can improve while the headline rate worsens, or the reverse.
- A three-month average looks stable only if you ignore how each month was rebuilt.
None of those points is exotic. They are in the footnotes, the methodology notes, the quiet paragraphs that do not fit a chyron. The absurdity is not that the statistics exist. Countries need a labor picture. The absurdity is the amount of capital that treats the first cut as if it were an audited count of every paycheck in the country.
The Plug That Rivals the Number Itself
Then there is the birth-death adjustment, the model’s attempt to guess jobs created by new firms and lost by firms that disappear before surveys catch them. In the month in question, that adjustment showed losses around 190,000 on a not-seasonally-adjusted basis. Whether it subtracted or added to the headline after seasonal factors is a technical argument. The scale is the point. A plug sitting in the same neighborhood as the number it is supposed to tidy up should make anyone pause.
Statistical offices are not inventing malice here. New businesses really do open. Old ones really do close. Survey frames lag real life. A model is a reasonable patch. What feels off, at least to me, is the confidence with which markets quote the patched figure down to the thousand. If the patch is huge, the precision is costume jewelry.
Imagine a classroom exercise. Billions can be made or lost on a figure that the people publishing it describe, in careful language, as subject to revision. The methods have aged. Response rates are not what they were. Administrative records exist that did not exist when the survey architecture was designed. You would expect the class to laugh, not to open a futures ticket. Yet that is the monthly habit. Not for a season. For years.
Why Electronic Paychecks Still Are Not the Headline
Here is the question I cannot shake. Why are we not closer to a paycheck-based count for the large slice of the workforce that actually receives a payment? Tax filings, payroll processors, and bank flows already touch a vast share of formal employment. A series built on those records would miss informal work, some gig arrangements, and people paid in cash. It would still cover enough of the economy to be a spine. Direction, level, and change could be tracked with less theater.
Private payroll processors already publish their own reads. One recent pair of prints, something like 36,000 one month and 90,000 the next, sat in a different neighborhood from the official first estimate. That does not make the private series gospel. Coverage differs. Small firms differ. But the disagreement is useful. When two thermometers disagree by that much, you do not average them and declare the room temperature settled. You ask which sensor is closer to the window.
A practical upgrade would not need to be perfect. It would need to be harder to miss by a hundred thousand jobs and then quietly fix later. Real-time administrative data, published with a clear coverage rate, plus a smaller survey for the edges, would beat the current mash of early guesses. I am not claiming the politics of that change are simple. Agencies guard methods. Firms guard data. Still, the status quo looks more like inertia than design.
A cleaner labor stack, in plain language:
  Core: paycheck and tax records for formal employment
  Edge: surveys for informal and new-firm activity
  Check: openings, quits, and hires that are harder to costume
  Rule: do not trade the first draft as if it were the audit
Signals That Are Harder to Dress Up
Not every labor series is equally slippery. Openings, hires, and quits come with their own flaws, but they describe behavior rather than a single constructed total. The quit rate sitting near 1.9 percent is one of those quieter tells. People leave jobs when they believe the next one is easy to find, or when the current one has become intolerable. A low quit rate can mean loyalty. More often, in a soft patch, it means caution. The “take this job and shove it” mood fades when the hallway outside looks empty.
The hires rate around 3.3 percent tells a cousin of that story. Through the middle of the last decade, hires often ran closer to 3.8 percent. Stuck near the lower figure, the market looks like the phrase everyone now repeats without quite owning it: not much firing, not much hiring. Firms hold staff because replacement is annoying and demand is not dead. They do not add staff because the next order is not obvious. That stalemate can last longer than a headline jobs miss, and it usually matters more for margins than a single monthly print.
I like these series because they are awkward to fake in a useful direction for a whole cycle. A company can delay a posting. It cannot easily pretend, month after month, that workers are quitting if they are not. Surveys still have noise. Levels drift. Even so, a low quit rate plus a subdued hire rate is a more coherent picture than a payroll number that fights its own revision.
| Signal | What it roughly said | How much I trust the first cut |
| Headline payrolls | Well below the guess, then prior months cut | Low until revisions settle |
| Household survey | A much stronger job gain in the same month | Low as a monthly count |
| Unemployment rate | Up a tenth, with higher participation | Medium, read with participation |
| Hourly earnings | Softened | Medium for inflation debates |
| Quit rate | Low, near 1.9 percent | Higher for worker confidence |
| Hires rate | Stuck near 3.3 percent | Higher for the no-hire mood |
That table is a habit, not a model. Trust is not a statistic. It is a scar tissue thing. After enough mornings where the revision ate the trade, you stop giving the first payroll print the benefit of the doubt. You still watch it. You just stop kneeling.
What the Bond Market Does With a Tepid Print
A soft enough jobs number usually buys bonds a bid. Lower yields can spill into equities, especially if the miss looks like cooling without collapse. That pattern showed up again around this release. It is mechanical, and it is also fragile. The rally depends on people believing the miss is real, and on nothing louder happening in credit or overseas rates before the close.
There is a better chance of plenty of traders breaking par on a lucky round than of these early figures being truly useful as a stand-alone verdict on the economy. We use them because the calendar says so, and because “we have nothing better” has become an acceptable shrug. That shrug is wearing thin. A cop-out repeated every month starts to look like a process.
Policymakers who keep saying not to obsess over one month, or one series, are doing the grown-up thing. A single print should not set the path of rates. The initial market jump often fades once the rest of the tape reasserts itself. If you traded only the knee-jerk and ignored the fade, you have already met this movie.
The Drivers That Outlast the Print
Once the excitement leaks out of the employment release, the same larger forces tend to reclaim the day. I keep a short list, not because it is complete, but because it explains more of the week than the jobs decimal does.
- Geopolitical conflict that can reprice energy, shipping, and risk premia overnight.
- The price of diesel and related fuels, which hits freight, farms, and margins before it hits a CPI headline.
- Spending on computing infrastructure, including the threat of cheaper capacity from abroad undercutting the current build-out story.
- European government yields, where small countries’ spreads can widen fast and leak into global rates.
- Credit spreads, quiet for long stretches, then suddenly the only chart anyone wants.
Conflict is the blunt one. Markets can digest a soft payrolls number. They struggle to digest a war premium that moves with headlines rather than with seasonal adjustment factors. Diesel sits in the unglamorous middle. It is not a poster child for inflation debates, yet it is the fuel under a huge share of physical commerce. When diesel jumps, cost pressure does not wait for the next employment table.
Compute spending is the newer obsession, and it deserves the attention. A huge capex cycle can support growth, power demand, and a narrow set of equities even while ordinary hiring looks tired. The risk on the other side is straightforward. If comparable computing becomes cheaper and more available from competitors abroad, the return math on the current build changes. Labor data will not warn you about that in time. Order books and chip commentary might.
When European Yields Stop Moving Together
One of the cleaner stress tells lately has been the split inside European short rates. German two-year yields slipped from about 3.31 percent early in a week toward 2.99 percent by Friday morning. French two-year yields moved the other way, from roughly 3.62 percent to 3.77 percent. A gap that started near 31 basis points and finished near 78 basis points in a handful of sessions is not a rounding error. It is a market arguing about credit, politics, and who gets the safety bid.
You do not need a dissertation to see why that matters outside Europe. Global bond desks arb these moves. A safety bid into one sovereign and a widening penalty on another changes the tone of rates even if the domestic jobs number was the morning’s official topic. I have watched equity rallies stall because a foreign spread moved, not because payrolls were revised. The jobs print gets the headline. The spread gets the afternoon.
A week that opens on employment and closes on sovereign spreads has told you which story had the longer half-life.
A rates desk habit, not a forecast
French and German paper are not interchangeable when politics and deficits diverge. Traders know this. The public conversation often does not, because a single jobs integer is easier to broadcast than a 47-basis-point weekly gap. If you care about the cost of money, you should care about both.
Credit Spreads Waking Up
Credit had been dull enough that many macro people stopped checking it daily. That lull is ending, at least at the margin. A widely watched credit default index moving from around 50 to around 60 over two weeks is not a crisis. It is a tap on the shoulder. Spreads at those levels still say funding is open. The direction says someone is buying protection, or selling risk, a little faster than last month.
Why mention credit in an article about employment? Because a jobs miss that sparks a bond rally can coexist with a credit market that is quietly charging more for risk. Those two messages fight. Lower government yields help valuations. Wider credit spreads say the private borrower is less trusted. When they diverge, I lean toward credit as the adult in the room. Employment can be revised. A spread is a price.
Nothing here says a blow-up is scheduled. The point is narrower. After a long stretch where credit was background noise, it is foreground again. Ignoring it because the jobs number was the scheduled event is how people miss the turn.
How a Desk Should Actually Read the Morning
There is a way through this that is not cynicism and not blind faith. Treat the first payroll print as a weather report from a station with a broken vane. Note the direction. Do not remodel the house. Then stack the checks that are harder to costume.
- Compare the new payroll figure with the size of recent revisions before you call a trend.
- Look at private payrolls separately from government hiring.
- Read unemployment only next to participation and underemployment.
- Set the household survey beside the establishment survey and admit the gap.
- Check whether the birth-death adjustment is large relative to the headline.
- Cross-read quits and hires for the no-hire, no-fire pattern.
- Ask what diesel, credit, and foreign yields are doing before you trust the equity bounce.
That list will not make you early on every trade. It will keep you from marrying a number that the publisher may divorce next month. Speed still matters on the open. Judgment matters more by the close. The people who last in this game are rarely the ones who shout the headline fastest. They are the ones who know which headline to ignore by noon.
Inflation, Wages, and the Wrong Kind of Comfort
Softer hourly earnings get framed as good news for inflation and bad news for households. Both frames can be true. A cooler wage print reduces the fear that pay is chasing prices in a loop. It also means the median worker is not getting the raise that would make the grocery bill feel smaller. Markets are built to celebrate the first frame. Households live in the second.
I am wary of any story that treats weaker pay growth as an unambiguous gift. If hiring is already hesitant and quits are low, softer wages can be a symptom of bargaining power shifting back to employers, not a clean disinflation victory. The policy debate often flattens that. A tenth on the unemployment rate plus a dip in earnings becomes “room to ease.” Sometimes that reading is fair. Sometimes it is a wish wearing a spreadsheet.
The participation rise is the detail I would not throw away. If more people are entering the labor force, a small increase in the jobless rate can be healthier than a low rate achieved by people giving up. Assuming the household figures are even roughly right, that is a kinder interpretation than the headline miss alone. The assumption is the fragile part. Still, it is a better question than “did we beat 90,000?”
The No-Hire, No-Fire Stretch
Labor markets do not only boom or bust. They stall. A stall looks like firms reluctant to post roles and reluctant to run layoffs, workers reluctant to quit, and official payrolls bouncing around a modest average that revisions keep sanding down. That is close to the picture painted by a hires rate stuck below the late-2010s norm and a quit rate that refuses to lift.
Stalls are awkward for narratives. Bulls want re-acceleration. Bears want a break. A stall gives neither a clean victory, and it can last while other cycles, especially capital spending on computing, run hot. The economy is not one temperature. It is a building with rooms. The server room can be overheating while the hiring office is half empty. A single jobs integer will not map the floor plan.
For equity investors, the stall shows up in guidance more than in the monthly print. Fewer requisitions, slower revenue per head, caution on bonuses. For bond investors, it shows up as a reason not to price a wage spiral, and also as a reason not to price a sudden collapse. The middle is a boring place to put capital. Boring is often where the carry is.
What a Better Release Would Look Like
If I were sketching a replacement, I would not start with another survey layer. I would start with coverage. Tell me, every month, what share of formal paychecks you can see directly. Publish the change in that covered set with a short lag. Then publish a separate estimate for the uncovered set, with a wide error band, so nobody confuses a model with a count. Keep the unemployment rate, but stop letting it travel alone. Pair it, in the same first paragraph, with participation and with a simple hiring-and-quits snapshot.
Revisions should be displayed as loudly as the headline. A chart of the original print versus the print three months later would do more for public literacy than another round of expert panels. People can handle uncertainty if you show it. They rebel, eventually, when you hide it under a false precision.
Useful morning formula: first print + revision history + survey gap + quits/hires + credit and energy. Drop any one of those and the story gets too neat.Would that formula trend on a broadcast? Probably not. Would it lose less money over a year? I think so. The industry’s attachment to a single round number is partly technical and partly cultural. Models need a cell. Language needs a hook. Culture is the harder fix.
A Note on Seasonals and the Calendar Trick
Seasonal adjustment is necessary and also a hiding place. Hiring really does bunch around school calendars, holidays, and weather. Stripping that pattern out is fair. The danger is when the adjustment and the birth-death plug and the response-rate problem all push the same direction in a thin month. You can get a headline that is mostly machinery. Next month the machinery shifts, and the story reverses, and both months were “data.”
I do not have a cleaner seasonal model in my pocket. I have a rule. If the not-seasonally-adjusted pieces are swinging by amounts similar to the adjusted headline, I fade my conviction. That rule has saved more trades than it has cost. It will not impress anyone in the first minute. It ages well.
Positioning Versus Information
Some of the move after a jobs miss is not information at all. It is positioning. If the street is leaning toward a firm labor market, a soft print forces an unwind. Yields drop because accounts are wrong-footed, not because the economy was revalued in a lasting way. The fade later in the morning is often that unwind finishing, while the slower money decides the miss was not enough to change the quarter.
You can see the fingerprint when equities rally on “bad” news and then stall once credit or foreign yields refuse to confirm. The first move was a squeeze. The second was a judgment. Confusing the two is expensive. I have done it. The tuition was the usual kind.
A practical tell: if the bond rally is large and credit spreads are unchanged to wider, do not assume equities have a free pass into the close. The rates impulse can be real and still be the wrong friend for risk assets. Soft labor data that arrives with wider credit is not the same animal as soft labor data that arrives with calm spreads.
What This Does Not Mean
Skepticism is not the same as claiming the labor market is a fiction. People are hired and fired every day. Paychecks clear. Unemployment offices see real applicants. The direction of travel over several quarters is usually visible even when a given Friday is noise. My argument is narrower. The monthly ceremony overstates the precision of the first release, understates revisions, and crowds out signals that are sitting in plain sight.
It also does not mean private data is pure. Payroll processors miss slices of the economy. Job-posting scrapes can be gamed by ghost listings. Card spending is not employment. A stack of imperfect series, read together, still beats a single imperfect series read as scripture. That is a low bar. We fail it regularly.
Nor is this a brief for ignoring policy. Central banks watch these tables, and markets know they watch them. The correct response is to watch what policymakers say about the limits of one month, and to notice when they actually behave that way. Talk is cheap. A cut or a pause justified by a single noisy print is a choice you can price. A pause justified by quits, hires, credit, and several months of revised payrolls is a different choice.
A Working Checklist for the Next Release
Next time the clock hits the release, try reading in this order instead of the order the headlines use. It feels slower. It is faster than unwinding a bad take at 11 a.m.
- Size of the miss versus the size of the last two revisions.
- Private payrolls, not just the total.
- Household versus establishment gap, stated out loud.
- Participation beside the unemployment rate.
- Earnings, but only as a symptom, not a trophy.
- Birth-death adjustment relative to the headline.
- Quits and hires against their 2016-2019 range.
- Diesel, credit index, and the German-French two-year gap before you trust the equity reaction.
If steps one through six are messy and steps seven and eight are calm, you may have a noisy morning rather than a new regime. If steps seven and eight are deteriorating while the payroll headline looks fine, believe the deterioration. I would rather be early on credit and quits than late on a revised payroll number.
The Human Cost Behind the Decimal
It is easy, from a screen, to talk about 29,000 versus 90,000 as if the difference were a sports score. Each thousand is a cluster of households deciding whether to move, refinance, or wait. A participation increase can be people returning because they must, not because a dream job appeared. A low quit rate can be fear with a professional tone. The market’s job is to price aggregates. It does not have to be blind to what the aggregate is made of.
That is not a plea for soft analysis. It is a plea against false precision. When we say the labor market “added” a figure we may revise by more than the figure itself, we are borrowing authority the measurement has not earned. Households feel the revision later, as a changed story about whether the ground is firm. Traders feel it as a mark. Both deserve a cleaner instrument.
Until that instrument exists, the adult posture is modest. Use the release. Do not worship it. Keep a second and third series within reach. And when someone asks if the number was “good,” answer with the gap, the revision, and the quit rate before you answer with an adjective. Adjectives are how absurd routines survive.
Where the Real Bets Go After Lunch
By early afternoon, the employment excitement usually thins. What remains are the bets that were there on Monday. Conflict risk. Fuel. The computing build and the chance it gets undercut. European spreads that no longer move as a bloc. Credit that has remembered how to widen. A shaky bond tape can outvote a tepid jobs miss if those other tapes are leaning the same way.
I expect that pattern to repeat. Not because labor does not matter, but because a noisy labor print cannot hold the microphone once stronger prices start speaking. The rational response is almost dull. Fade the overconfidence. Keep the checklist. Let the slower data earn the larger position. There is nothing heroic about that. Heroic, on these mornings, is how accounts get smaller.
We can keep pretending the first jobs number is a compass. Or we can admit it is a sketch, sometimes a good one, often a draft that will be redrawn, and build the rest of the week around prices that do not apologize a month later. I know which habit I trust. The other one still fills the room at release time. That, more than any single miss, is the absurd part.