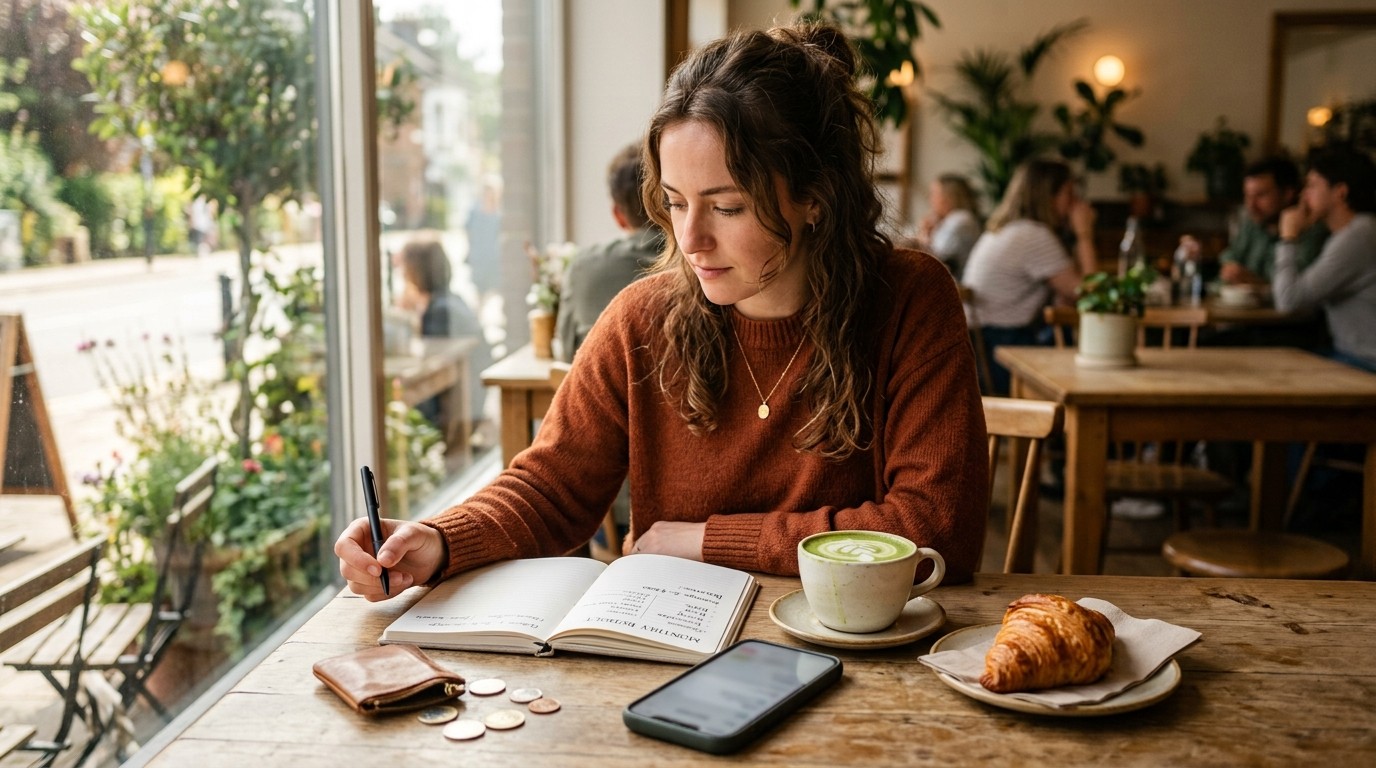

Have you ever sworn you would skip the afternoon pastry, then found yourself in line anyway because the day felt heavy and that one small purchase seemed like the only thing you could control? I have. More than once. That tug between a tiny pleasure and a larger money goal sits at the center of what people now call the little treat economy, and it is not as silly as it sounds from the outside.
Why Small Treats Feel Bigger Than They Look
Younger adults are delaying some of the classic milestones. Starting a family, moving into a place that actually feels stable, or going back to school can sit on pause when rent, bills, and student balances eat the month. That pressure does not erase the need for a lift. It often intensifies it. A warm drink, a scoop of ice cream, or a bakery bag becomes a short, affordable signal that life is not only invoices.
Recent consumer research keeps circling the same pattern. A large share of Gen Z reports putting off a major life decision because money feels tight. At the same time, an even larger share admits they still buy themselves something small to recover from a rough day or mark a good one. I do not find that contradiction hypocritical. I find it human. When the big wins feel far away, people reach for the nearest win they can actually afford today.
Affordable luxury tends to rise when household stress rises. The purchase is less about the object and more about a brief sense of agency.
Older readers may remember the so-called lipstick effect. When bigger purchases stall, smaller comforts climb. The current version just happens to look like oat milk, iced drinks, and bakery counters instead of a single cosmetic. Spending on ice cream and baked goods among younger customers has been growing faster than it has for other age groups. Visits to independent coffee shops have jumped as well. None of that means the generation is careless. It means the emotional math is different when housing takes a painful slice of income.
The Money Reality Behind The Ritual
Look at the housing numbers and the ritual starts to make more sense. Plenty of younger renters say housing is the single biggest obstacle to feeling financially successful. Many put more than half of their income toward rent, which sits well above the old thirty percent rule of thumb. When the fixed costs are that high, the leftover cash does not feel like a plan. It feels like scraps. Scraps are where treats hide.
Bill stress shows up in other ways too. A notable share of people in their late teens and twenties report not covering every bill in a recent month. Nearly half have leaned on someone outside the household for everyday costs such as a phone plan, utilities, or rent help over a twelve-month stretch. Those are not lifestyle-flex statistics. Those are survival statistics wearing a cute cup.
Here is the part that surprises people who only see the latte photos. Younger workers are often starting retirement accounts earlier than their parents did. The catch is the ratio. They still save the least relative to what they spend. Discretionary goods and services can swallow more than a fifth of household income in this group, higher than other generations. So the story is not “they refuse to plan.” The story is “the plan is competing with a daily need to feel okay.”
In my experience, shame is a terrible budgeting tool. If you tell someone their croissant is the reason they cannot buy a home, they will either hide the croissant or quit the budget. Neither outcome helps. A better question is how to keep the ritual from becoming an invisible leak.
What A Joy Budget Actually Means
A joy budget is not a permission slip to ignore rent. It is a named line in the plan that admits pleasure is going to happen, so it might as well happen on purpose. I like that framing because it removes the moral lecture. You are not “good” when you skip every treat and “bad” when you buy one. You are simply allocating a finite pile of cash.
Start with a real budget if you do not have one. Small, frequent purchases are harder to track than a single vacation. They blur. They hide inside debit notifications you swipe away. Pulling accounts into one view, including cards and savings, makes the blur visible. A solid app should let you rename categories, spot subscriptions, and, if you share a kitchen, split goals without turning dinner into a finance meeting.
Look for tools that sync with a wide range of banks, keep read-only access, and use serious encryption. Custom categories matter more than flashy dashboards. If “coffee” sits inside “food,” you will never see the pattern. Separate it. Give the treat line a number you can live with. Then treat that number like rent: it exists, it gets paid, and it does not get to raid the emergency pile.
- Name the treat category so it cannot hide inside groceries
- Set a weekly cap instead of a vague monthly hope
- Track subscriptions in the same place as the daily extras
- Review the category every Sunday, not only when panic hits
- Move unused treat money into savings before the next week starts
Building room for treats rarely happens in one heroic month. It happens in small redirects. Cancel one streaming plan you forgot. Cook two extra nights. Move the difference the same day, while the win still feels real. Waiting until the end of the month is how good intentions evaporate.
Park The Surplus Where It Works Overnight
Once a joy budget exists, the leftover cash needs a home that does more than sit. A high-yield savings account is the unglamorous hero here. Yields on competitive accounts can dwarf what a basic savings product pays. That gap compounds quietly while you are busy living.
Some online savings products advertise rates around four percent with almost no barrier to entry. A tiny opening deposit can be enough. No monthly fee. No punishment for ordinary transfers. The tradeoff is often convenience: you may not get a debit card or a checking companion from the same shop. Fine. Use it as a dedicated jar, not as your everyday wallet.
| Account Role | What It Should Do | What To Avoid |
| Everyday checking | Pay bills and the joy budget | Leaving large idle balances |
| High-yield savings | Hold emergency cash and unused treat money | Treating it like a spending account |
| Retirement account | Capture long-term contributions first | Skipping deposits to fund daily extras |
I have found that labeling the savings bucket helps more than another spreadsheet tab. “Future rent buffer” feels different from “general savings.” “Concert fund” feels different from “misc.” Language changes behavior because it makes the future feel specific.
Spend Selectively Instead Of Constantly
The little treat economy becomes a problem when frequency replaces intention. A daily automatic stop can cost more than a planned night out you would actually remember. The goal is not to ban pleasure. The goal is to stop buying on autopilot.
Ask a blunt question before you order: is this the treat, or is this just Tuesday? If it is Tuesday wearing a treat costume, walk. If it is the thing that will genuinely reset your mood, buy it and log it. That single pause sounds precious until you try it for two weeks. The pause is the whole method.
Many younger travelers still want trips even when housing is ugly. If travel sits high on your list, a mid-fee rewards card can stretch the dollars you already spend on transit, dining, and bookings. Look for flexible points, travel protections, and a credit that offsets a trusted-traveler application every few years. Transfer partners can stretch value further than a flat cash statement, provided you repay the balance in full. Interest will eat the joy faster than any pastry ever could.
If live events matter more than airports, a no-annual-fee card that pays extra on entertainment and dining can be the cleaner fit. Concerts, sports, streaming, and nights out often sit in the same emotional budget as the little treat. Earning a bit back on those categories is not a license to upgrade every ticket. It is a way to make the planned nights cheaper after the fact.
- Decide which experiences you want to remember this quarter
- Price those experiences first, before daily extras
- Shrink the daily treat line to fund the memory line
- Use rewards only on spending you already planned
- Pay the card in full so the reward stays a reward
Perhaps the most interesting aspect is how quickly habit spending loses its sparkle once you save toward something vivid. A festival weekend or a cheap flight you can actually point to on a calendar beats a blur of forgotten cups. Not always. Some weeks you still need the cup. That is allowed. The point is choice, not purity.
How Treats Interact With Retirement Timing
People love to pit lattes against compound interest. The meme is tidy and mostly unhelpful. A four-dollar drink is not the sole reason a retirement balance looks thin. Housing, wages, and inconsistent contributions do more damage. Still, frequency matters because frequency is stealth.
Run a simple picture in your head. Five small purchases a week at eight dollars each is forty dollars. Forty dollars a week is a bit more than two thousand a year. Left in a high-yield account, that pile grows. Directed into a retirement vehicle with decades ahead, it grows faster. You do not need to redirect every dollar. Redirecting two of the five purchases already changes the ending.
I would rather see someone keep two meaningful treats and automate a transfer on payday than watch them swear off joy, last eleven days, and rebound hard. Sustainability beats austerity. Retirement planning for this generation is less about perfect ratios and more about not vanishing from the plan during stressful months.
Keep a pleasure line you can defend. Then protect the future line with the same stubbornness.
– Personal finance counselor
A Practical Week That Still Feels Like Your Life
Theory is cheap. A week has weather, group chats, and a coworker who suggests “just one stop.” Here is a rhythm that has worked for people I have coached, including myself on better months.
Sunday night, glance at the treat category and the savings balance. Do not perform a forensic audit. Just look. Monday through Wednesday, default to home coffee unless the week is already on fire. Thursday, if the cap still has room, take the good version of the ritual on purpose. Friday, decide whether a social spend is the treat or an extra. Saturday, leave space for a bakery run only if the line item still has air.
That schedule is not sacred. Night-shift workers and parents will need a different map. The principle stays. Cluster the pleasure. Do not sprinkle it until it disappears and still costs the same.
Weekly cash map:
  Fixed costs first
  Automated savings second
  Named joy budget third
  Everything else waits
If a friend group treats daily cafes as the social glue, suggest a rotation. One paid outing, one park outing, one home outing. You will lose some invitations. You will also stop funding a social script you did not write.
Warning Signs The Treat Line Has Taken Over
A joy budget fails when it becomes the only flexible line and every stressor hits it. Watch for these tells. The emergency fund never grows. Credit card interest appears on ordinary weeks. You feel irritated when you skip a purchase, not disappointed, irritated. You hide transactions from a partner or roommate. Those are not personality quirks. Those are signals the category needs a smaller cap or a harder pause.
Debt counselors often describe a gap between what people think they spend on “little things” and what the statements show. The gap is rarely one luxury item. It is repetition plus optimism. Optimism says next week will be cheaper. Next week is rarely cheaper unless you change the default.
If the statements keep surprising you, go analog for fourteen days. Cash envelope or a notes app running total. Digital tools are excellent until notifications become background noise. A running total in your pocket is rude in a useful way.
Sharing Money Goals Without Policing Each Other
Roommates and partners complicate treats because one person’s harmless habit is another person’s leak. Collaboration mode in a budgeting tool can help if both people get their own login and neither treats the app like a surveillance camera. Agree on shared bills first. Then agree that personal joy lines stay personal as long as shared obligations clear.
I have watched couples fight about coffee while ignoring a car payment schedule. That is a misdirected argument. Put the large obligations on the table in plain numbers. After that, a six-dollar drink is easier to discuss without turning it into a character judgment.
If you are the higher earner, do not mock the cheaper ritual. If you are the tighter budgeter, do not narrate every receipt. Respect is a money skill. So is minding your own category.
Making Rewards Work Without Feeding The Habit
Rewards cards can support a selective-spending plan or quietly sponsor overspending. The difference is mechanical. If you only swipe for planned categories and you clear the statement, points are a discount. If the card becomes the reason you upgrade the drink size, the discount is theater.
Travel cards with a modest annual fee can make sense when you already buy flights, trains, or hotels. Entertainment-heavy cash-back cards can make sense when concerts and dining are the real luxury. Neither product fixes a missing budget. They amplify whatever system you already have, tidy or messy.
Read the fee table before the welcome bonus. A bonus that requires a sprint of spending can shove you past the joy budget and into a hole. If the required spend is higher than your normal three-month total, skip it. There will be another offer. There will not be another easy repair of a bloated balance.
The Emotional Job A Treat Is Trying To Do
This is the part personal-finance writing often skips because it feels soft. The drink is not only caffeine. It is a door you walk through between work-you and off-you. It is a five-minute conversation with a barista who is not asking about your output. It is a small ceremony that says the day had a peak.
If you remove the ceremony and leave the stress, the money saved can feel strangely empty. Replace the ceremony on purpose. A walk with headphones. A better breakfast at home plated like you are a guest. A library hour. Cheap does not have to mean bleak. Bleak is what sends you back to the counter.
I’ve found that naming the feeling before the purchase cuts the fog. Bored? Lonely? Celebrating? Avoiding an email? Each feeling deserves a different response. Only some of them deserve a transaction.
Putting The Pieces Together Without Turning Joy Into Homework
You can keep the little treat economy and still act like a person with a future. The method is almost annoyingly simple. See the spending. Name a cap. Save the unused amount the same week. Aim bigger experiences when you want a memory, not a reflex. Let retirement contributions leave the checking account before the week gets loud.
Will you overshoot some weeks? Of course. I do. The repair is the next transfer, not a personality overhaul. Progress in money looks less like a mountain pose and more like a series of slightly less sloppy months.
If you remember one idea, remember this. The treat is not the enemy. Drift is the enemy. Drift is what happens when no line item owns the purchase and no future account receives the leftover. Draw the lines. Keep the pastry when it earns its place. Send the rest where it can grow while you get on with a life that still tastes like something.