
Have you ever watched the market shift so fast that it feels like the ground moved under your feet in a single session? That is exactly what unfolded this week when a wave of political results hit the tape and traders responded with some of the most aggressive options activity we have seen in months. The standout move landed in a major mortgage lender that had spent most of the year in the penalty box, and the size of the call buying was impossible to ignore.
How Midterm Results Sparked a Broad Market Repricing
Stocks opened with real energy after the midterm results delivered a clear shift in the political landscape. By midday the broader market had climbed nearly two percent, wiping out the losses from the prior Friday and Monday in one clean sweep. What caught my eye even more than the cash market move was the speed at which options prices adjusted. The volatility gauge dropped roughly four points and settled below seventeen. That kind of one-day plunge in implied volatility does not happen every week. In fact, it ranks among the sharpest declines we have recorded since the summer.
Traders were not simply buying the rally. They were actively selling the fear that had built up over the previous sessions. I have found that when volatility collapses this quickly after a political catalyst, it often signals a broader repositioning rather than a short-lived spike. Portfolio managers and retail participants alike appeared ready to lean into the idea that uncertainty had just been reduced, at least for the near term.
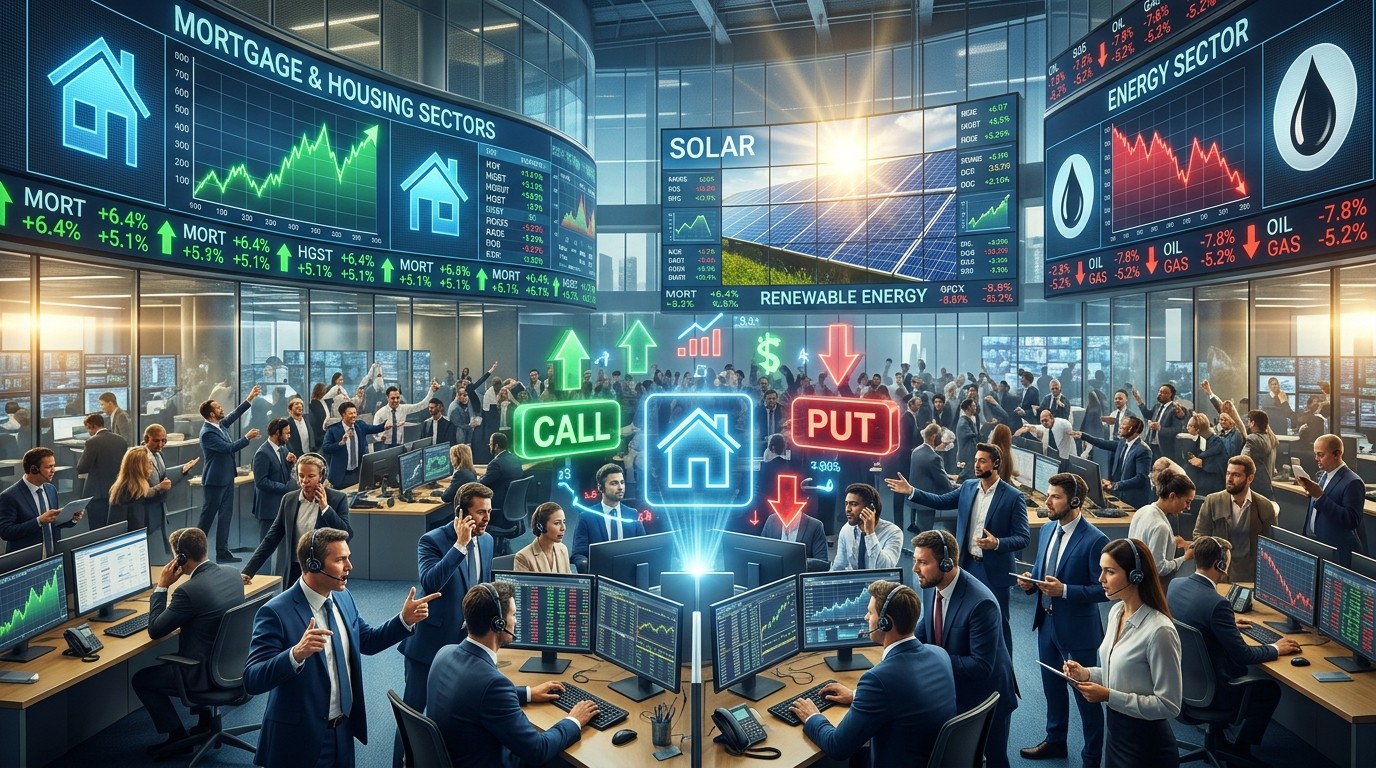
Energy stocks told a different story. Crude prices slipped and the entire sector lost more than five percent, marking its weakest performance of the day across the major indexes. Options volume on the energy sector fund exploded to more than three times its recent average. Puts dominated the flow, accounting for roughly fifty-seven percent of the contracts traded. The largest single trade focused on the January 62.5 put, a strike that suggests some larger players are positioning for a gradual rather than sudden decline in what had been one of the strongest groups earlier in the year.
The Mortgage Lender That Suddenly Became the Center of Attention
While energy sold off, housing-related names started to attract serious capital. One leading mortgage lender stood out. The company had dropped nearly fifty percent earlier in the year before staging a quiet recovery over the past several weeks. On this particular day options volume ran at double the average, and the bias was unmistakably bullish. Ninety percent of the contracts traded were calls, and the open interest data pointed to more buyers than sellers initiating the positions.
The most popular contracts were the November 14 and 16 calls. Those strikes sit close enough to the current price to deliver meaningful leverage if the shares keep climbing, yet far enough to require a real move rather than a modest bounce. In my experience this type of concentrated call buying in a name that has already begun to turn higher often reflects a belief that the worst of the rate-driven pressure has passed.
Mortgage activity tends to respond quickly to shifts in interest-rate expectations. When traders see a path toward lower rates or at least more stable rates, they often rotate capital into lenders and related housing names. The volume we witnessed looked like more than simple speculation. It had the flavor of position building by accounts that expect the sector to continue recovering through the remainder of the year.
When call volume suddenly dominates in a beaten-down financial name and the broader market is already rising, the combination frequently marks the early stage of a larger sector re-rating.
I watched the tape closely as those contracts changed hands. The urgency was clear. Liquidity was absorbed without much resistance, which usually means the buyers arrived with size and conviction. That is the kind of flow that can force market makers to hedge by buying the underlying shares, creating a short-term feedback loop that pushes the stock higher still.
Solar Names Extended an Already Strong Run
Opposite the energy decline sat another clean rotation. Solar companies continued a multi-session advance and pushed the dedicated solar fund to levels not seen since July. The fund itself gained nine percent on the day. Options volume ran more than five times the recent average, and roughly eighty percent of that activity came from calls. The single most popular contract was the November 48 call, a strike that implies traders are looking for an additional six percent move in a relatively short window.
Unusual options activity had already appeared in these names ahead of the political results. The follow-through after the votes were counted suggests that participants who positioned early are now being joined by a second wave of buyers. Solar stocks often trade as a pure expression of policy expectations around clean energy and interest rates. Lower financing costs can improve project economics, and that linkage was clearly on display.
What I find particularly interesting is the contrast with traditional energy. One group was being sold aggressively through puts while the other was being bought through calls. That kind of clean sector bifurcation rarely lasts forever, but while it is in place it creates clear relative-value opportunities for traders who can move quickly.
Semiconductor Options Flashed a More Cautious Tone
Not every area of the market participated in the optimism. The semiconductor fund dropped more than two and a half percent and touched its lowest level since May. Options volume ran at twice the average, and seventy percent of the contracts were puts. The most actively traded contract was the November 475 put. That strike sits close enough to the market to attract traders looking for near-term downside protection or outright directional bets.
Tech names had led for much of the prior period, so a period of digestion after a political catalyst is not surprising. Still, the heavy put flow stands in contrast to the call-heavy action in housing and solar. It serves as a reminder that even on a strong up day the market is rarely uniform. Some money is still looking for places to express caution.
I have seen similar patterns in the past. When volatility collapses across the broad market while certain high-beta groups continue to attract protective put buying, it often means the rally is real but selective. Traders are willing to own the names they believe benefit from the new political backdrop and are equally willing to hedge the names they believe have already run too far.
Consumer Discretionary Showed Strength but Options Stayed Quiet
Consumer discretionary stocks rallied almost five percent, yet options volume in the sector fund stayed below average and was roughly balanced between puts and calls. That divergence is worth noting. Sometimes the cash market moves hard while the options market remains subdued, which can indicate that the advance is being driven more by systematic flows or short covering than by aggressive new speculation.
In contrast, the housing-related names and the solar complex drew concentrated options interest. That concentration often proves more meaningful than a broad but quiet advance. When volume spikes and the call-put ratio tilts heavily in one direction, the message from the options market becomes clearer.
Perhaps the most interesting aspect is how cleanly the flows sorted themselves. Rate-sensitive and policy-sensitive groups attracted the bullish capital. Traditional energy and parts of the semiconductor complex absorbed the defensive capital. The rest of the market simply followed the broader index higher with less fanfare.
What the Volatility Collapse Really Means for Positioning
A four-point drop in the volatility index in a single session does more than lower the price of protection. It changes the cost of leverage. When implied volatility falls this quickly, the premium required to buy calls or puts shrinks. That lower cost can encourage additional speculative activity in the days that follow. It can also force volatility sellers who were short the market to cover, adding another layer of buying pressure to the underlying indexes.
I have watched this dynamic play out many times. The first day after a catalyst often features the sharpest volatility move. The subsequent sessions then test whether the new lower level of implied volatility can hold. If it does, the environment tends to favor trend-following strategies and longer-dated call structures. If volatility rebounds quickly, the market is telling us the initial reaction was overdone.
Right now the data lean toward the more constructive outcome. Volume in the mortgage lender and the solar fund arrived with clear directional bias. Those flows are harder to dismiss as noise.
- Heavy call buying in a recovering mortgage name signals improving rate expectations
- Explosive put volume in energy points to profit-taking after a strong year
- Solar call activity continues a pre-existing trend rather than starting a new one
- Semiconductor put buying suggests selective caution inside the broader tech complex
Reading the Housing Trade in Context
Mortgage lenders live and die by the path of interest rates and the health of the housing market. After a difficult stretch earlier in the year, the recent price recovery already hinted that some of the worst pressure had eased. The options activity we saw takes that hint a step further. When ninety percent of the contracts are calls and the preferred strikes are relatively near-term, traders are expressing a view that the next few weeks could deliver continued upside.
That view does not require a dramatic collapse in rates. Even a period of stability can improve origination volumes and refinance activity. The market appears to be pricing in that possibility. I tend to watch open interest changes in the days after a volume spike. If the calls remain open and the stock continues to climb, the initial buyers are likely still in the trade. If the open interest collapses quickly, the move was more tactical than strategic.
Either way, the appearance of size in this name on a day when the broader market was already rising adds an important data point. Housing-related equities are no longer being ignored. They are attracting real capital again.
Energy Puts and the Risk of a Slow Rollover
The energy complex had been one of the better performers for much of the year. A single session of heavy put buying does not erase that performance, yet it does raise the possibility of a change in character. The concentration in the January 62.5 put is especially telling. That expiry gives the market several weeks to work lower without requiring an immediate collapse. It is the kind of structure often used by accounts that expect a gradual rather than violent decline.
Crude prices moving below the ninety-dollar level provided the fundamental backdrop. When the commodity softens and the equity options market simultaneously leans bearish, the combination can create self-reinforcing pressure. Energy stocks frequently amplify moves in the underlying commodity, and the options market can amplify them further through dealer hedging.
I would not read this flow as a wholesale abandonment of the sector. Rather, it looks like a healthy digestion after a strong run, timed to coincide with a day when capital was clearly rotating elsewhere.
Solar Momentum and Policy Sensitivity
Solar equities have shown an ability to move independently of the broader market when policy expectations shift. The volume we observed was not a one-day wonder. Unusual activity had already been building, and the post-result session simply accelerated an existing trend. The preference for the November 48 call shows that traders are focused on a relatively tight time frame. They are not waiting for next year. They want the move now.
That urgency can work both ways. If the shares deliver the expected gain, the calls will pay off handsomely and may attract still more capital. If the move stalls, the same concentrated positioning can unwind quickly. For the moment the tape is supporting the bullish case. The fund reached levels last seen in the middle of the summer, and the options market is treating that breakout as legitimate.
In my view the solar complex remains one of the cleaner ways to express a view on the intersection of lower rates and supportive policy. The options market is currently agreeing with that assessment.
Putting the Day into a Broader Framework
One strong session does not make a lasting trend, yet the character of the options flow offers useful clues. The collapse in volatility, the rotation out of energy and into housing and solar, and the selective caution in semiconductors all paint a coherent picture. Capital is moving toward groups that stand to benefit from a more stable rate environment and a clearer policy backdrop. At the same time, groups that had already enjoyed substantial gains are seeing some of that capital leave.
This is the kind of day that rewards traders who pay attention to relative volume and directional bias rather than simply watching the headline index. The mortgage lender that attracted the heavy call buying may or may not become the next multi-month winner, but the fact that it drew that much attention on a day of broad strength is meaningful. The same can be said for the solar complex.
Looking ahead, the key question is whether the lower level of volatility can persist. If it does, the cost of expressing bullish views remains attractive and the path of least resistance for the broader market stays higher. If volatility begins to creep higher again, the same options market that fueled the current moves can just as easily reverse them.
For now the evidence leans constructive. The largest and most directional trades of the day landed in names that benefit from the new political and rate landscape. That is rarely an accident. It is the market speaking in the language it knows best, through volume, open interest, and the price of risk.
I will be watching the mortgage lender closely in the sessions ahead. The call buying was too concentrated and too one-sided to dismiss. Whether those positions continue to perform will tell us a great deal about how durable the current rotation really is. The same applies to the solar names that extended their run and the energy names that absorbed the bulk of the defensive flow.
Markets rarely move in straight lines, but they do leave footprints. The options activity we just witnessed left some of the clearest footprints of the year so far. Traders who take the time to study them will be better prepared for whatever comes next.
Practical Takeaways for Active Participants
Several practical lessons emerge from the session. First, political catalysts can compress volatility faster than almost any other event. When that compression occurs, the subsequent options activity often reveals the true preferred destinations for capital. Second, sector rotations show up more clearly in the options market than in the cash market on the first day. Volume spikes and skewed call-put ratios are the early warning system.
Third, names that have already begun to recover can still attract aggressive new buying if the fundamental backdrop improves. The mortgage lender in question had already turned higher before this volume surge. The options market simply accelerated the process. Fourth, even on a strong up day some groups will attract protective flow. Ignoring those signals can leave a portfolio exposed when the market eventually pauses.
Finally, the interaction between commodity prices and equity options remains powerful. Soft crude and heavy energy put buying arrived together. That combination is worth monitoring for follow-through.
- Watch for sustained open interest in the heavily traded call strikes
- Monitor whether volatility remains suppressed in the days after the catalyst
- Compare relative volume across sectors rather than focusing solely on the index
- Pay attention to near-term versus longer-dated expiries for clues about trader time horizons
- Treat concentrated directional flow as a higher-conviction signal than balanced volume
These observations are not predictions. They are simply the patterns that have repeated across many similar sessions. The current environment contains enough of those patterns to deserve close attention.
Why This Rotation Feels Different
Rotations happen all the time. What makes this one notable is the speed and the clarity of the options response. The mortgage lender did not simply participate in a broad advance. It became one of the focal points of the day’s directional activity. Solar names did not merely bounce. They extended an existing unusual-options trend with even greater intensity. Energy did not merely lag. It absorbed a clear wave of put buying at a time when the rest of the market was rising.
That combination of signals is rarer than a simple risk-on day. It suggests that the market is doing more than celebrating reduced political uncertainty. It is actively reallocating capital toward the groups expected to benefit most from the new environment and away from the groups that had already discounted a great deal of good news.
Whether those reallocations prove correct will be determined in the weeks ahead. For the moment the options market has cast its vote with volume and with directional bias. That vote is worth respecting even if one ultimately disagrees with the underlying thesis.
I have learned over the years that the most useful information often arrives on the days when the market moves the fastest. The noise is high, but so is the signal. Filtering that signal requires looking past the headline index percentage and into the individual name and sector options flows. That is exactly where the real story of this session resides.
The mortgage lender that suddenly drew double its normal options volume and a ninety-percent call bias sits at the center of that story. The solar complex that pushed volume five times higher sits right beside it. The energy complex that absorbed the put side of the ledger completes the picture. Together they describe a market that is not merely rising but actively choosing winners and losers in real time.
That process is never finished after a single day. It will continue to evolve. The traders who stay close to the options tape will be the first to notice when the next chapter begins.