
Ask a room full of nuclear engineers what actually slows a reactor build and you will get a polite pause, then a much less polite answer. It is rarely the physics. It is fuel, and the paperwork that has to exist before anyone is allowed to touch that fuel. I have watched this pattern for years, and it still surprises me how often the market prices the reactor drawing and ignores the permit that makes the drawing useful. That is the frame I keep coming back to with the latest move from NANO Nuclear and its HALEU Energy Fuel subsidiary: a definitive agreement to buy the U.S. nuclear fuel processing assets tied to Radnostix, formerly International Isotopes, and its fluorine-products unit. The headline number is modest. The thing being bought is not.
After a small premarket lift, the stock slipped on the day. Odd, if you remember how the same name jumped hard on a similarly sized logistics deal earlier in the year. Inbounds on the nuclear tape have been thin. Good news has been treated like background noise. I would argue this one is being underpriced, not because a dormant plant suddenly prints cash, but because a fuel cycle license is one of the few assets in this industry you cannot honestly accelerate.
A License You Cannot Rush, Bought for the Price of a Trucking Deal
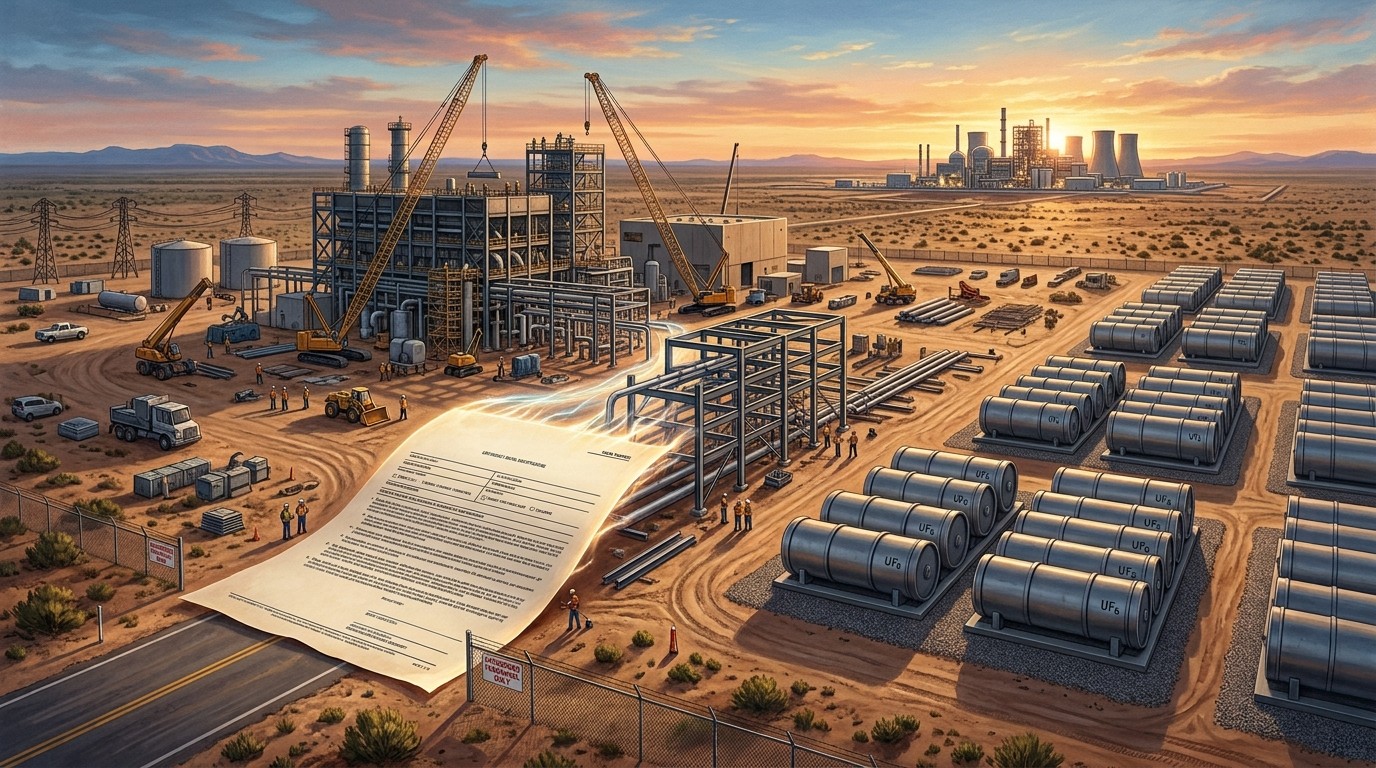
The asset is the old fluorine extraction and depleted-uranium deconversion project near Hobbs, New Mexico. Regulators issued the license on October 2, 2012, with a forty-year term. It was the first commercial license of its kind in the country. The facility itself was never built. Sit with that for a second. Thirteen years of a live authorization, and no plant on the pad.
The original design was straightforward in concept and awkward in practice. Take the depleted uranium hexafluoride tails left after enrichment, convert them into a stable oxide that can be disposed of, and pull the fluorine back out as high-purity products, including anhydrous hydrogen fluoride used in semiconductor and solar manufacturing. Nuclear leftover, turned into a chemical the chip industry already buys. That is a very 2026 sentence, and it is also a real industrial process, not a slogan.
Location does more work here than the press language admits. The site sits roughly thirty miles from Urenco USA in Eunice, the main commercial enrichment plant in the country, rated around 4.3 million separative work units a year, with a multibillion-dollar expansion already on the drawing board. Enrichment produces tails every day it runs. Storage authorization at Eunice runs up to 251 million kilograms of depleted UF6. The long-term plan for those tails has pointed overseas, toward a facility in the United Kingdom. A licensed deconversion site next door is the obvious domestic alternative. Obvious does not mean easy. It does mean the geography is no longer a footnote.
Why a Real License Sat Idle for Thirteen Years
Idle assets usually have a story, and this one is less mysterious than it looks. A condition in Urenco’s own license had blocked the use of deconversion plants that produced anhydrous hydrogen fluoride. That condition came off in 2025. Cylinder storage at Eunice was ample. There was no committed buyer. In plain English, there was a permit and no customer.
That customer problem is what changed, not the chemistry. The Russian uranium import ban, with waivers that run out in January 2028, forced a conversation Washington had postponed for a decade. Federal money for domestic enrichment followed. A single commercial enrichment plant and a single conversion plant, the latter running well below its licensed rate, stopped looking like a quirk and started looking like a bottleneck. I have found that markets are slow to reprice a constraint until the waiver date is close enough to put on a calendar. We are close enough.
If we are going to have this nuclear renaissance, we are not going to be able to do it without fuel.
A senior energy official, speaking on the supply gap
That line is not poetry. It is the constraint. Reactor physics can be elegant. Fuel chemistry can be solved. Neither matters if the cylinder has nowhere legal to go, and if the only conversion and enrichment capacity in the country is already spoken for by the existing fleet.
What the Purchase Price Actually Buys
The cash-and-stock consideration lands around $13.5 million. About $4 million of that is stock, which is dilution you can measure with a calculator and then forget. Relative to cash on the balance sheet, the outlay is roughly two percent. Relative to a fresh fuel-cycle application, it is a different category of spend.
The line that matters in the company’s release is not the one about depleted uranium. It is the claim that the existing license offers a significantly more efficient regulatory pathway to add other fuel-cycle processes through amendments, rather than opening a new application from a blank page. The chief executive framed it as multiple potential pathways into domestic fuel-cycle work, with the flexibility to decide later what actually gets built.
Translation, and this is my read rather than theirs: they are paying for a regulatory head start. Anyone who has sat through a fuel-cycle licensing proceeding knows the calendar is the expensive part. The enrichment plant down the road took years to license. Time saved at that stage is worth more than the purchase price, especially in a country with one conversion plant running at something like half to seventy percent of a 15,000-tonne license, and one commercial-scale enrichment plant.
The Workstream That Stopped Being a Slide
Readers who tracked the late-summer memorandum with Enveniam, the lead integrator on the LIS Technologies laser-enrichment effort, should have seen the shape of this. One of the six workstreams on that page was conversion and deconversion. At the time it read like vertical integration still living on a corporate slide. Four weeks later there is a licensed site attached to that workstream. Slides do not get NRC docket numbers. This does.
Since January the company has been assembling pieces that only make sense if you look at them as one chain rather than five press releases.
- Enrichment, via LIS Technologies’ laser approach, pitched by its backers as cheaper to run and less capital-heavy to deploy, with an integrator lined up for a planned Tennessee plant.
- Fuel supply and fabrication, through the HALEU Energy Fuel subsidiary that is the buyer here, plus an August memorandum with Quadrant Nuclear Industries on domestic HALEU.
- Logistics, through a transport package and the acquisition of a specialist hauler that moved the largest single international HALEU shipment in the relevant federal history, about 1.7 metric tons out of Japan, and turned the parent into a company with revenue.
- Fuel handling, through work on the KRONOS handling and storage system.
- Reactors: KRONOS at the University of Illinois, where technical review of the construction permit is underway, plus ZEUS and the space-oriented LOKI concept.
None of those lines is a finished plant. Together they are a bet that the company which can move fuel, store fuel, and eventually process the leftovers will matter more than the company that only draws the core. Perhaps the most interesting aspect is how unfashionable that bet still looks on a day the stock trades down.
Fuel Is Where the Margin Argument Lives
The cleanest case for spending on fuel rather than only on reactors does not even require a view on this specific name. Sell-side work on a separate TRISO supplier described a capital-light model, early pricing power, EBITDA margins that could approach the mid-sixties by 2030, and revenue moving from under $20 million in 2026 to more than a billion by 2030. All of that rests on a forecast of roughly 15 gigawatts of cumulative small-reactor deployment by 2035, up from zero, which would need on the order of 100 metric tons of fuel. The same note argued that funding growth without endless external capital is what separates a fuel name from peers tied only to reactor timelines.
That is the gap a reactor developer is trying to close. You raise money until first power. A fuel supplier can charge people along the way. Think of it, imperfectly, as owning the filling stations while everyone else is still designing the car. One desk cut its target on this name from the high thirties to the low twenties to reflect a higher cost of capital and a slower 2030 to 2035 buildout, and said outright that it prefers fuel and supply-chain names that make money now. If the market keeps paying fuel-cycle multiples, and this company keeps buying fuel-cycle assets, the conclusion is not subtle.
I do not treat sell-side margin bridges as gospel. I do treat the direction as a useful argument. A reactor story with no fuel path is a financing story. A fuel story with a reactor attached is a different conversation with the same investors.
Eight Big Reactors, and a Supply Chain With No Spare Room
The macro backdrop got louder after a U.S.-Korea package that includes on the order of $120 billion for eight large American reactors, six of one design and two of another. Strategists reading that package called it constructive for deployment and for the broader fuel cycle, and likely to widen the uranium supply deficit they already expect in the 2030 window. Eight gigawatt-scale reactors need conversion, enrichment, and eventually tails handling. That is more uranium hexafluoride moving through a chain with very little spare capacity.
Prices already show the strain. Separative-work prices sit at an all-time high and are still rising. North American conversion remains roughly three times pre-2022 levels even after falling from a peak near $97 per kilogram of uranium late in 2024. Term uranium has printed around $96 a pound. The sector ETF is down on the year while anything tied to data-center power is up. That split is the mood. It is also why a license can change hands without a parade.
| Pressure point | What the tape is saying | Why a license matters |
| Enrichment | SWU at a record and still climbing | Tails volume rises with every new SWU |
| Conversion | Still about 3x pre-2022, off the peak | One domestic plant, running below license |
| HALEU | Flagship capacity measured in low tens of tonnes | A single first core can absorb most of a year |
| Tails | Storage authorized, long-term plan pointed abroad | A licensed site thirty miles away is the alternative |
Western enrichment supply outside Russia is already short of Western demand before a single small reactor is connected. Figures derived from international agency data put supply near 24.8 million SWU against demand near 28.5 million. In a 2050 high case that includes small reactors, demand climbs toward 69 million. You do not need to believe the high case to see the present tense. The West is short now.
HALEU Is the Tightest Knot in the Rope
High-assay low-enriched uranium is where the optimism and the arithmetic collide. Centrus has talked about 12 metric tons a year of HALEU capacity, with first new output aimed at 2029. A single Oklo Aurora first core is on the order of 7 metric tons. Do the division. America’s flagship HALEU program, at the start, fuels about two reactors a year. That is the main reason microreactor developers have started walking down the fuel chain themselves instead of waiting for a merchant market that does not exist yet.
Is that a reason to own every developer that buys a fuel asset? No. It is a reason to stop treating fuel announcements as side quests. When the entire early HALEU system can be absorbed by two first cores, optionality on conversion, deconversion, transport, and fabrication stops being a diversification slide and starts being the business.
A rough early-year picture, not a forecast:
  Flagship HALEU aim: about 12 MT a year
  One advanced first core: about 7 MT
  Reactors that capacity can start: about two
  Commercial U.S. enrichment plants: one
  Commercial U.S. conversion plants: one
Can a Sub-Billion Name Carry This Much Ambition?
This is the objection I would raise if I were on the other side of the table. Laser enrichment, fuel fabrication, a deconversion plant, a transport fleet, three reactor designs, and a space concept is a lot of surface area for a company with a market value around $850 million. Maybe that value should be higher. Maybe the market is correctly refusing to capitalize five unfinished plans. Both sentences can be true on the same afternoon.
A useful comparison from late September lined cash against expected capital spending and developer payments through 2032. On that chart, the funding gap here was the smallest of three listed small-reactor names: roughly $581 million of cash against about $913 million of needs, versus a multi-billion cash pile set against a much larger build-own-operate bill elsewhere. Smallest gap is not the same as no gap. It does mean the company is not asking the market to finance a utility from a standing start.
Today’s deal does not close that gap and does not widen it in any way that matters. The real cost is whatever eventually gets built in Lea County. There is no final investment decision, so that figure does not exist. Bulls will call the absence optionality. Bears will call it a blank check. I have sat in both chairs on names like this. Both have a point, and the next filing will tell you which chair is more comfortable.
What Can Still Go Wrong
Licenses are not plants. This one has been unused for thirteen years, which is a fact the bull case has to carry rather than step around. A source-material authorization for deconversion is useful. Adding conversion, or anything that touches enriched material, means amendments, regulatory review, and possibly a different licensing basis. More efficient does not mean fast. I would tattoo that sentence on the investor presentation if I could.
New Mexico is the second risk, and it is political rather than technical. The deal needs state approval. Lea County already hosts enrichment and has lived with the industry. The state capital fought hard against a proposed interim spent-fuel storage site in the same corner of the map. A deconversion plant is a different animal. Expect the same activists anyway. Different process, same hearing room, same capacity to slow a calendar.
Focus is the third. Every new line of business is another place a delay can hide. The base case is still KRONOS at the university site, with construction targeted for late 2027 by at least one desk that rates the stock a buy. A slip there will not be repaired by a fluorine plant. Investors who wanted a pure reactor story are allowed to be annoyed. Investors who wanted a fuel story should notice that the reactor is still the clock the market will use.
Sentiment is the fourth, and it is the one you can feel without a model. Term uranium at a record, a sector fund down on the year, a peer pulling an offering, and a short interest that was about a quarter of the float as of May. This stock can move hard in either direction on a headline that would barely register in a calmer tape. Underpricing and volatility are not opposites. They often arrive together.
- The license has to become a project, not a docket entry.
- State approval has to survive a political climate that already rejected a different nuclear use nearby.
- Amendments for anything beyond deconversion have to clear review without resetting the clock.
- The reactor timeline at the university site has to stay intact, because that is still the equity story most holders came for.
- Cash has to cover the gap between optionality and a final investment decision.
The Gas Station Problem, Stated Without the Slogan
Modular reactors behind the meter are, in my view, the only durable answer to data-center load that does not assume a grid which keeps saying no. That view can be wrong on timing and still right on physics. A reactor without fuel is an expensive paperweight. The company’s own line, earlier in the year, was blunter: what good is a new car if there are no stations to fill it. Over nine months the pieces added have been the stations, the hauling, and now a licensed place to deal with what the stations leave behind.
In 2012 that license was close to worthless because there was no market for domestic fuel services of this kind. Then the import ban arrived, with a waiver cliff in 2028. Then federal enrichment awards on the order of $2.7 billion. Then record separative-work prices. Then an expansion thirty miles down the road. Then a reactor package large enough that strategists said it makes the 2030 fuel deficit worse. Stack those and a forty-year fuel-cycle authorization at $13.5 million looks cheap. The company paid about the same for a trucking business. One of those assets can be replicated with capital and contracts. The other cannot be replicated on a schedule you control.
A reactor without fuel is a very expensive paperweight. The license is the part of the supply chain you cannot honestly speed up.
How to Read the Next Two Quarters
Whether a dormant authorization becomes a working plant is the next question, and it will not be answered by another memorandum. The closing window is ninety to one hundred twenty days. After that, the first amendment filing is the real test. I would watch four things, in this order, and ignore the rest of the noise.
First, does the state sign off without conditions that hollow out the site advantage. Second, does the amendment ask for deconversion only, or does it reach for conversion and enriched-material work in the same breath. Ambition in the filing is information. So is restraint. Third, does the enrichment partner down the road show any commercial interest, even a non-binding one, in a domestic tails path. Fourth, does cash stay boring. Boring cash is a feature when the equity story is a stack of options.
There is a habit, in this corner of the market, of treating every nuclear headline as either renaissance or rug-pull. The Hobbs license is neither. It is a thirteen-year-old key to a door that was not worth opening until the customer showed up. The customer is not a single offtake contract. The customer is a policy cliff, a price chart, and a plant thirty miles away that produces tails whether or not anyone has a domestic plan for them.
A Note on What This Is Not
It is not a finished deconversion business. It is not a HALEU plant. It is not proof that laser enrichment will be cheaper, or that a university reactor will pour concrete in late 2027. It is not a reason to ignore short interest, dilution, or the chance that Santa Fe slows Lea County. Anyone selling it as those things is selling a different article.
It is a regulated head start, bought while the tape is bored, in a fuel cycle that is already short before the reactors everyone is modeling have been built. I have found that the deals which look small on the day they print are often the ones that reframe the company twelve months later, provided the next filing is real. Provided. That word is doing a lot of work, and it should.
Strategically, the move fits the chain the company has been building in public since January. It is positioning to supply fuel, move fuel, and handle the residue, rather than wait in line with every other reactor developer. Whether the market pays for that positioning before a plant exists is a separate trade. The industrial logic does not depend on the day’s close.