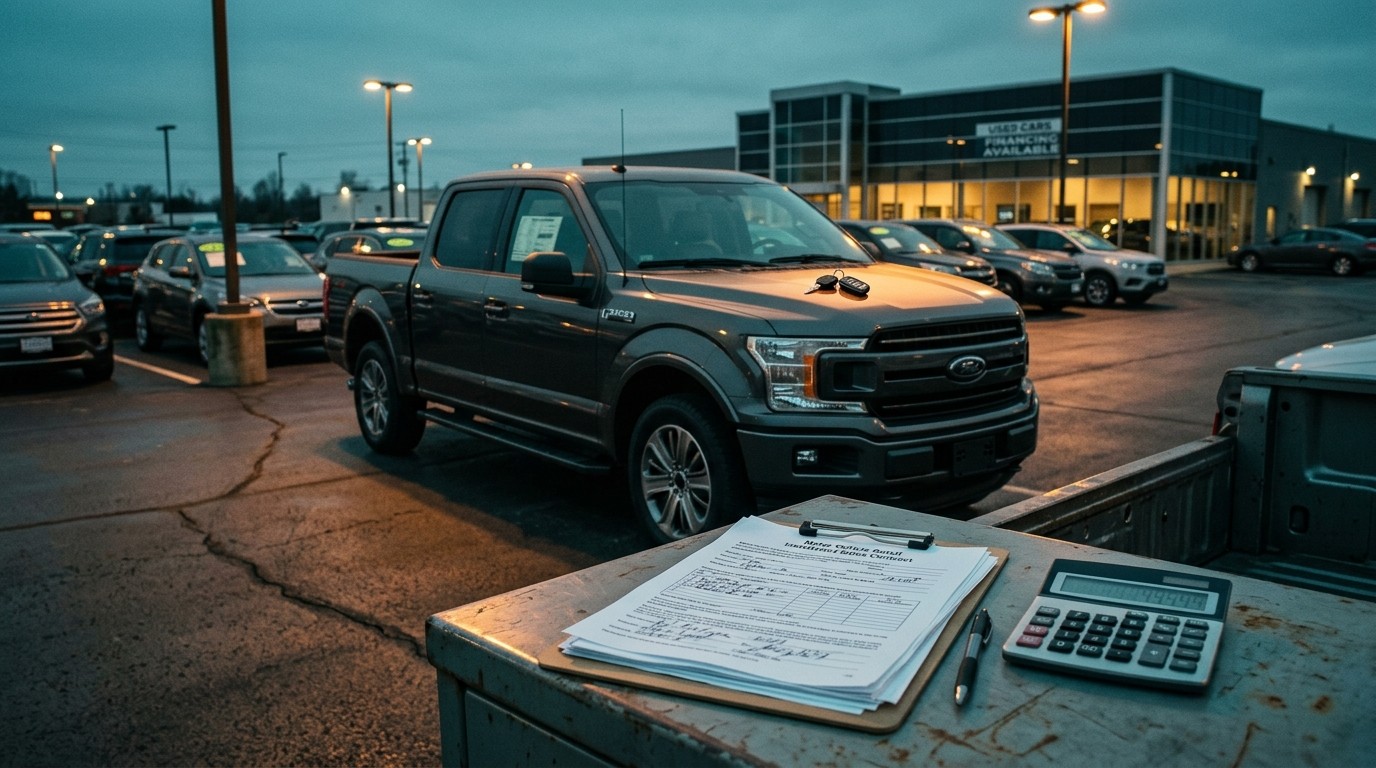

A customer walked into a Texas dealership last summer with a 2025 heavy-duty pickup that still smelled new. Fourteen thousand miles. Payment: $1,472 a month. He wanted out, or at least a smaller number on the statement. The truck was worth about $58,000. He still owed roughly $79,000. That $21,000 gap is negative equity, and it is the quiet trap that turns a car purchase into a multi-year money problem. I have watched versions of this scene play out for years. The request is almost always the same: make the payment smaller. The math almost never cooperates.
How Negative Equity Turns A Car Into Permanent Debt
Negative equity is simple on paper. You owe more than the vehicle would sell for today. In practice it is messy. Depreciation hits fast. Loan balances shrink slowly at first because early payments are heavy on interest. If you trade before those two lines meet, the leftover balance does not vanish. It rides into the next contract unless you write a check to close it.
Industry data puts the typical underwater trade-in hole near $6,900 now, up from the mid-$4,000s a decade ago. About one in four of those trades carries more than $10,000 of leftover debt. Five years ago, a hole that large usually meant a luxury sedan. Now it shows up on ordinary pickups. That shift should make anyone pause before treating a monthly payment as the whole story.
If you have a bunch of negative equity, it is very difficult to lower your payment.
– Dealership owner describing daily trade-in talks
Dealers hear this conversation two or three times a day. Buyers arrive focused on cash flow this month. They leave, too often, with a longer term and a bigger total bill. That pattern is what researchers and planners now call permanent car debt: unpaid balances rolling from one vehicle to the next until ownership never quite arrives.
Why The Hole Got Deeper
Prices are the obvious culprit. Average new-vehicle transaction prices have climbed about 31 percent since 2019, from the high $30,000s into the high $40,000s. A bigger sticker means a bigger loan. A bigger loan means more room to fall behind the moment the car leaves the lot.
The less obvious change is term length. In the 1970s, a 48-month note still felt experimental. By 2010 the typical finance-company loan sat near 60 months. A few years later it drifted toward 65. Today the average new-car loan is about 70 months. Roughly one in four buyers now signs 84 months or longer. That is a record.
I am not automatically against a long note. If you keep the car until the last payment, you will own it. Trouble starts when the loan outlives your patience with the vehicle. Among underwater trade-ins, the average age at trade is four years. By then a typical new car has lost nearly half its original value. You have also spent those early years paying a lot of interest and not much principal. Stretch the term and that gap widens.
The Snowball Nobody Plans For
When leftover debt rolls into the next loan, you are financing two things: the new car and the old mistake. To keep the monthly number familiar, many buyers add a year or two to the term. Then they do it again. Financial psychologists describe the result as a loop. Long loans plus frequent trades reinforce each other. You are always financing a car. You rarely finish one.
Buyers who roll negative equity are especially likely to grab the longest available term. In a recent quarter, about 43 percent of those who folded leftover balances into a new-car loan took 84 months. A couple thousand dollars leftover can be paid off and forgotten. Seven, eight, ten thousand? That is the range where people start to wonder if they will ever hold a title without a lien.
Once you start dipping into that $7,000, $8,000, $9,000, $10,000 upside-downness rolled into the next vehicle, you might never own the car.
– Automotive insights director
Perhaps the most interesting part is how ordinary the setup feels in the moment. Same payment. Newer features. Warranty still intact. The extra years hide in the fine print. Interest does not hide. On a $50,000 loan at 7 percent fixed, stretching from 60 to 84 months can cut more than $200 off the monthly bill while adding roughly $4,000 in interest over the life of the note. Across the market, average lifetime interest on an auto loan now lands near $10,000. That is rent paid for the privilege of borrowing.
Shopping The Payment Instead Of The Price
A lot of damage happens before anyone sits in a showroom chair. People budget a monthly number. They have $500 left after rent and groceries. They see $425 and think they are safe. Psychologists call that anchoring. The payment becomes the only figure that feels real.
Having $500 available does not make $425 cheap if it leaves no slack for insurance, tires, a deductible, or a bad month at work. And once the conversation is about thirty extra dollars a month, a $5,000 jump in sticker price starts to sound harmless. In my experience, that is how buyers talk themselves into more truck, more trim, more years.
Dealerships are designed to overwhelm the senses. New-car smell. Screens. Quiet leather. The rush fades. The payment does not. Spending a little more feels easy to justify while you are standing under fluorescent lights with a salesperson who already knows your target number.
- Decide a maximum total price before you shop, not just a monthly cap.
- Price insurance and maintenance before you fall in love with a trim level.
- Ask for the payoff and current wholesale value of any vehicle you already own.
- Refuse to roll leftover debt unless you can close most of it in cash.
- Compare 60-month and 84-month totals side by side, not just the payment.
Those steps sound boring. They are also the difference between owning a car in five years and still explaining a balance to the next lender.
Know What Kind Of Car Owner You Actually Are
An 84-month loan does not guarantee negative equity. Risk rises when the contract lasts longer than you will keep the vehicle. Researchers keep seeing the same mismatch: people sign for seven years and come back in three or five. Families change. Commutes change. Tech gets old. Color regret is real. None of that is a moral failure. It is a planning failure if the loan assumed you would stay put.
If you honestly want a different car every few years, a lease can match the habit better than a six- or seven-year note you will never finish. You will not own the car. You also will not drag an unpaid balance into the next deal when the term ends, assuming you stay inside mileage and condition limits. That tradeoff is worth saying out loud before you sign.
If you are already underwater by a wide margin, the least exciting advice is often the best. Keep the vehicle. Pay it down. Give depreciation a chance to slow while principal finally moves. Repair bills after the factory warranty can still cost less than replacing the whole machine. Once the loan is gone, that payment can move to savings, a vacation, or simply breathing room. I tend to drive cars until they embarrass me. That is not a personality flex. It is arithmetic.
| Situation | Better default move | Why it helps |
| Small leftover balance | Pay it off before trading | Stops interest from compounding on old debt |
| Large leftover balance | Keep the car two more years | Closes the gap without a bigger next loan |
| New car every three years | Consider a lease | Matches the habit without rolling equity holes |
| Payment-first shopper | Cap total price first | Blocks “just $40 more a month” upgrades |
| Loan already 84 months | Avoid another stretch | Prevents the permanent-debt loop |
What The Numbers Look Like In Real Life
Take that $50,000 example again. Same rate. Different clocks. The shorter term hurts monthly cash flow and saves thousands over time. The longer term feels kind on payday and expensive in year six. Neither is automatically wrong. The wrong move is pretending they cost the same because the payment looks similar after a trade.
Now add rolled-in debt. A $10,000 leftover balance on top of a $40,000 car is not a $40,000 car. It is a $50,000 loan wearing a cheaper vehicle’s clothes. If that next car depreciates on a normal curve, you can be underwater again before the first oil change cycle is done. That is how a “same payment” swap becomes a longer sentence.
Rough sequence of the trap:
  1. Buy with a long term to hit a monthly target
  2. Trade at year three or four while still underwater
  3. Roll the gap into the next note
  4. Stretch the term again to keep the payment familiar
  5. Repeat until the title never feels like yours
Does this mean nobody should finance a vehicle? Of course not. It means the product you are buying is both the car and the contract. Ignore the contract and the car will still lose value on schedule. The contract will not forgive you for being surprised.
Practical Ways To Stay Above Water
Start with a down payment that is actually a down payment, not a trade that still owes money. A meaningful cash cushion shortens the time you spend underwater after the first-year depreciation cliff. If cash is tight, buy less car. That sentence is blunt because the alternative is usually a longer term dressed up as a deal.
Get the payoff letter and an independent value estimate before you negotiate. Do not let the first number you hear become the only number you trust. If the gap is ugly, walk. Keeping a paid-down vehicle is not failure. It is often the only move that improves the next three years of cash flow.
- Write down a total purchase cap, including tax and fees.
- Pull your current payoff and a realistic wholesale range.
- Subtract. If the result is a large negative, stop shopping.
- Model 60-month and 72-month payments at the same price.
- Choose the term you can finish, not the term that flatters this month.
Warranty hunger is real. New tech is tempting. Family needs change. Those are valid reasons to switch vehicles. They are not valid reasons to pretend leftover debt is free. If you must move, pay down as much of the hole as you can first, even if it means delaying the purchase six months. Delay is cheaper than another 24 months of interest on money you already spent.
The Psychology That Keeps The Cycle Going
People are not foolish for wanting a comfortable commute. They are human for treating a monthly figure as a complete plan. Sensory overload in a showroom does the rest. I have found that the buyers who break the cycle are rarely the ones with the highest income. They are the ones who can tolerate an older bumper and a smaller payment story at dinner.
There is also a status layer nobody likes to admit. A newer grill photographs better. A longer loan hides the cost of that photo. If your identity is tied to the model year in the driveway, the market will gladly sell you another year of identity on installment. That is not a lecture. It is a product design.
You walk into a dealership and it is sensory overload. The initial rush wears off. The car payment may not.
– Specialist in financial psychology
So ask the unromantic question. Are you a keeper or a rotator? Keepers should hunt shorter terms, bigger down payments, and boring reliability. Rotators should look at leases or at used cars they can buy with cash or a short note. Mixing the two personalities is how the snowball forms.
When Holding On Beats Trading Up
Maintenance after year five can look scary on social media. A transmission quote will do that. Compare that quote with a new payment plus tax, plus the leftover balance you would roll. Many owners discover the repair is still the smaller number. Reliability varies by model, of course. The point is to run the comparison instead of assuming replacement is cheaper because it feels cleaner.
Once the loan dies, flexibility shows up. You can keep driving and redirect the old payment. You can sell without begging a lender to unwind a mess. You can wait for a price dip instead of shopping in a panic because a warranty clock is ringing. That optionality is worth more than another set of heated seats.
Certified planners often frame it as a trade-off question rather than a purity test. Carrying debt longer has a cost. Replacing the car early has a cost. Weigh them. Do not let the showroom decide which cost you will live with for seven years.
A Clearer Way To Think About The Next Purchase
Picture two columns. Left column: total cash out the door over the years you will actually keep the vehicle. Right column: the story you tell yourself about the monthly number. Shop the left column. Use the right column only as a constraint, not as a goal to maximize.
If a salesperson says the payment can stay the same, ask what happened to the term and the amount financed. Same payment with more years is not a tie. It is a loss you agreed to slowly. If they say your trade covers the down payment, ask whether that trade still has a payoff larger than its value. Language in dealerships is built to soothe. Your job is to translate.
Would I tell that Texas truck owner to keep paying $1,472? In his case, yes, unless he had a pile of cash I did not hear about. Lowering the payment without cash usually meant a cheaper vehicle plus the same $21,000 shadow, or the same class of truck plus even more years. Neither path fixed the hole. Time and principal do.
What To Remember Before You Sign
Negative equity is not a rare luxury-car problem anymore. Long terms are normal. Prices are higher. Four-year trades are common. Put those facts in one room and you get a market that can keep people financing transportation for a decade without a clean title. That is the trap. It is avoidable if you treat the contract with the same seriousness you treat the paint color.
Set a price cap. Know your payoff. Respect depreciation. Match the loan length to how long you will actually keep the thing. If you are already deep underwater, stay put long enough for the numbers to meet. If you rotate cars on purpose, stop using purchase loans as if they were short-term rentals.
None of this requires perfect discipline. It requires one uncomfortable conversation with yourself before the new-car smell does the talking. The payment will always try to sound small. The balance will not. Choose which number you want to live with when the shine is gone.