
Something unusual happened in the markets this week, and if you blinked you might have missed the quiet shift taking place beneath the usual headlines. While conversations continue to revolve around the same handful of technology giants, a different group of companies quietly posted some of the strongest relative gains seen in nearly three years. I have been watching these rotations for a while, and this one feels different. It is not just noise. It looks like a genuine moment of reassessment.
Why Non AI Stocks Are Suddenly Leading The Charge
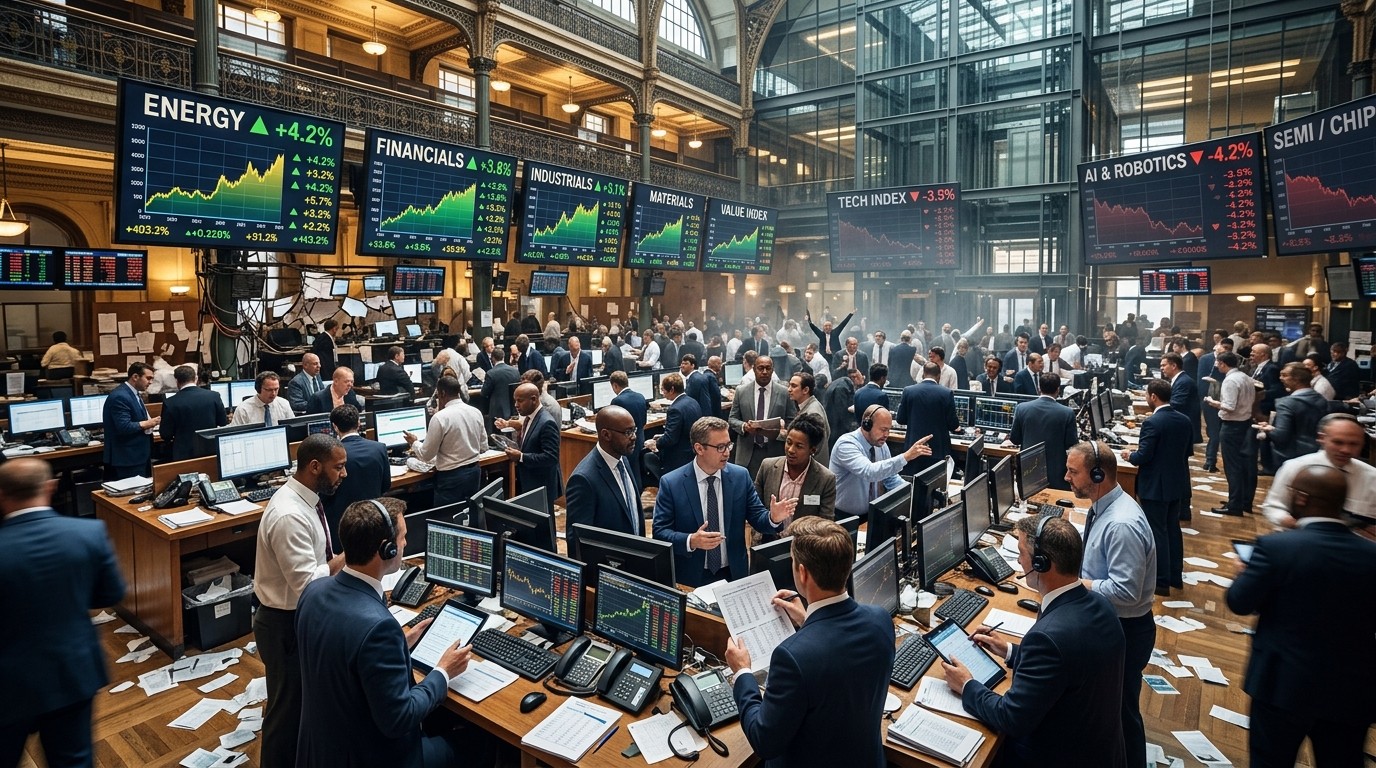
The numbers tell a clear story. Stocks with little or no meaningful connection to artificial intelligence infrastructure, chips, or cloud demand outperformed the broader market by a margin that stands out even against recent history. One analysis of major index data showed the gap reaching levels last seen only a couple of times since early last year. On one particularly sharp day the difference approached almost two full percentage points in favor of the non AI group. For the week as a whole the advantage stretched beyond three percentage points while the main index actually slipped lower.
That kind of divergence does not appear by accident. Investors appear to be questioning whether the concentration that has defined the market since late 2022 still makes sense at current valuations. When a relatively small cluster of names drives so much of the overall return, any pause in their momentum creates room for everything else to breathe. This week that breathing room became very visible.
The Companies Quietly Delivering Strong Results
Look at some of the individual names that stood out. A major credit scoring firm jumped nearly fourteen percent. Another data analytics player focused on consumer credit advanced more than ten percent. A well known restaurant operator gained over ten percent as well. Even a long established spirits company posted a solid nine percent rise. These are not speculative growth stories tied to the next generation of computing power. They are businesses with established models, recurring demand, and in some cases defensive characteristics that suddenly look attractive again.
I find it interesting how quickly sentiment can pivot when the dominant narrative softens even slightly. For months the conversation has centered on data center buildouts, power demand, and semiconductor capacity. Those themes remain important, of course. Yet when the broader market takes a step back, capital often seeks areas that have been relatively ignored. That search appears to be underway right now.
Understanding The Ex AI Benchmark
A specialized index was created earlier this year precisely to track this dynamic. It strips out companies with significant exposure to artificial intelligence related revenue streams, infrastructure spending, or demand drivers. At the time of its introduction, the excluded group represented roughly forty five percent of the main large cap benchmark. That concentration figure alone explains why the difference between the full index and the ex AI version can become so pronounced during certain periods.
The purpose of such a tool is straightforward. It gives investors a cleaner way to measure performance outside the dominant theme and potentially to hedge against periods when that theme cools. History for the index was reconstructed back to the start of last year, providing a useful window into how the non AI universe has behaved relative to the full market over time. Long term the broader index still leads, which is no surprise given the powerful multi year run in technology. Short term windows like this week, however, reveal the other side of the equation.
Investors are actively looking for ways to measure and manage exposure beyond the concentrated group of companies that have powered most of the gains since the generative AI wave began.
In my view this kind of benchmark serves a practical purpose. It forces a clearer conversation about concentration risk. When nearly half the market value sits in names tied to one powerful theme, the rest of the market can look neglected. That neglect sometimes creates opportunity.
A Closer Look At This Week’s Performance Gap
Wednesday offered the most dramatic illustration. The non AI version of the large cap index rose more than half a percent while the full index lagged by a wide margin, producing one of the largest single day spreads of the year in favor of the broader group. By the time Thursday closed, the weekly advantage for the ex AI measure had expanded to more than three percentage points. Only one other week in the recent past produced a larger gap, and that earlier episode also coincided with a pullback in the main benchmark.
These gaps matter because they highlight how uneven leadership has become. For long stretches the market has moved higher largely on the back of a narrow set of winners. When that leadership pauses, the relative performance of everything else can improve simply by standing still or advancing modestly. This week the non AI group did more than stand still. It advanced with real conviction while the overall index struggled.
Perhaps the most interesting aspect is the breadth of the move. It was not confined to one or two defensive sectors. Credit related firms, restaurant operators, and consumer brand names all participated. That variety suggests the rotation is more about seeking alternatives than purely fleeing risk.
Longer Term Context Still Favors Concentration
It would be a mistake to declare the end of the dominant theme based on one strong week. Over multi year horizons the companies tied to advanced computing and related infrastructure have delivered extraordinary returns. The structural drivers behind that performance, including sustained capital spending on data capacity and the ongoing integration of machine learning tools across industries, remain intact. Many of those businesses continue to report robust demand and expanding margins.
Yet markets rarely move in straight lines. Periods of extreme concentration eventually invite questions about valuation, positioning, and opportunity cost. When a large portion of institutional and retail capital sits in the same handful of names, even modest profit taking can produce noticeable underperformance relative to the rest of the market. That dynamic appears to have played out this week.
I have found that the healthiest markets usually feature leadership that rotates rather than remains locked in place indefinitely. Prolonged narrow leadership can create fragility. Broader participation tends to support more durable advances. Whether this week marks the beginning of a more sustained broadening remains an open question, but the performance gap itself is hard to ignore.
What Non Tech Compounders Offer Investors
Some research voices have highlighted a category they describe as non tech compounders. These are businesses capable of delivering consistent growth without relying on the current infrastructure buildout cycle. Pharmaceutical innovators with strong pipelines, certain consumer brand companies with pricing power, and selective industrial names often appear in such discussions. The appeal is straightforward. They can provide growth exposure that is less correlated with the dominant technology theme.
In periods when technology leadership broadens or when volatility rises, these compounders can play a useful role in portfolios. They offer a form of ballast. Their earnings streams are driven by different end markets, different customer bases, and different competitive dynamics. That differentiation becomes valuable precisely when the main growth narrative faces temporary pressure.
- Consistent earnings growth independent of technology cycles
- Established competitive positions in their respective industries
- Potential for multiple expansion if investor attention expands
- Lower correlation with the most crowded trades
Of course no group is immune to broader economic conditions. Consumer facing businesses still feel the effects of spending patterns. Healthcare names remain subject to regulatory and pricing pressures. The point is not that these companies are risk free. It is that their risk profiles differ meaningfully from pure technology infrastructure plays.
Investor Psychology And The Desire For Alternatives
There is a psychological element at work here as well. After years of watching the same names dominate performance rankings, many investors feel a natural urge to look elsewhere. That urge intensifies when valuations in the leading group stretch further from historical norms. The search for underappreciated value or simply for different sources of return becomes more intense.
This week’s price action may reflect that search in real time. Capital does not disappear. It reallocates. When the most popular corner of the market pauses, flows can move toward areas that have lagged. Sometimes those flows prove temporary. Other times they mark the early stages of a more meaningful shift in leadership. Distinguishing between the two is always difficult in the moment.
In my experience the most useful approach is to watch the persistence of the relative performance rather than any single week. One strong period can be noise. Several consecutive periods of outperformance by the broader market would carry more weight. So far the long term trend still favors concentration, yet the short term signal is clear enough to warrant attention.
Practical Implications For Portfolio Construction
What should an individual investor take away from this episode? First, concentration risk is real even when the concentrated names are high quality businesses. Owning a portfolio that closely mirrors the main large cap index means accepting substantial exposure to a single powerful theme. That exposure has been highly rewarding, but it also creates vulnerability to any sustained pause in that theme.
Second, the existence of tools that isolate the non AI universe makes it easier to monitor the other side of the market. Tracking relative performance between the full index and its ex AI counterpart provides a clean signal of whether leadership is broadening or remaining narrow. Persistent outperformance by the broader group would suggest a healthier market structure.
Third, selective exposure to quality businesses outside the dominant theme can improve diversification without requiring a complete retreat from growth. The goal is not to abandon successful positions. It is to ensure that portfolios contain multiple sources of potential return.
| Performance Measure | This Week | Recent Context |
| Ex AI Index Gain | Approximately 2.4 percent | One of the stronger relative weeks |
| Main Index Change | Nearly 1 percent decline | Contrasting direction |
| Relative Gap | Over 3 percentage points | Second largest recent weekly gap |
| Single Day Highlight | 1.72 point advantage | Fifth largest daily gap this year |
The table above captures the essence of the divergence in simple terms. Numbers alone do not dictate strategy, yet they do highlight when attention may be warranted.
Historical Parallels And Lessons From Past Rotations
Market history contains numerous episodes of extreme concentration followed by broadening. Technology leadership in the late 1990s eventually gave way to a multi year period in which other sectors played catch up. Energy and materials enjoyed strong relative runs during certain commodity cycles. Even within technology itself, leadership has rotated between hardware, software, and internet platforms over different decades.
Each episode carries its own unique drivers, so direct comparisons always require caution. Still, the pattern of eventual rotation is familiar. Capital tends to seek the next opportunity once the current one becomes widely owned and fully valued. The timing of that shift is notoriously difficult to predict. This week simply serves as a reminder that such shifts remain possible.
One lesson that stands out from past cycles is the value of patience. Investors who maintained diversified exposure through periods of narrow leadership often found themselves better positioned when the leadership changed. Those who concentrated heavily in the dominant theme sometimes faced sharper drawdowns once momentum faded.
Risks That Could Reverse The Current Move
It is equally important to acknowledge the risks that could quickly reverse this week’s relative strength. A renewed surge in spending plans or particularly strong earnings from the leading technology names could reassert their dominance. Macro data that supports higher growth expectations might also favor the more cyclical and higher beta areas of the market that have led for so long.
Interest rate expectations remain another variable. Shifts in the outlook for monetary policy can influence which parts of the market attract capital. A more accommodative stance might support broader risk taking, while a more restrictive path could keep the focus on the highest quality growth stories.
In short, one week does not make a trend. The structural case for continued investment in advanced computing capabilities remains compelling for many long term investors. The current episode is better viewed as a useful stress test of portfolio balance than as a definitive turning point.
How To Monitor The Situation Going Forward
For those who want to track whether this rotation has staying power, several simple observations can help. Watch the relative performance of the broader market versus the technology heavy portion over the coming weeks. Pay attention to earnings commentary from companies outside the AI infrastructure complex. Note whether capital continues to flow toward credit, consumer, and healthcare names or quickly returns to the prior leaders.
Volume patterns and breadth statistics also offer clues. Strong advances on solid volume across a wide range of sectors tend to signal more durable interest. Thin, low volume moves are more easily reversed. So far the recent action has shown enough participation to keep the discussion alive.
I tend to keep a mental checklist rather than a rigid set of rules. Relative strength persistence, earnings resilience outside the dominant theme, and any change in institutional positioning all factor into the assessment. No single data point decides the case.
Balancing Growth Ambition With Practical Diversification
The core challenge for many investors remains how to participate in powerful secular growth trends without becoming overly exposed to their inevitable periods of consolidation. Artificial intelligence related spending and innovation clearly represent one of the most significant capital allocation themes of the current decade. Ignoring it entirely would mean missing substantial opportunities.
At the same time, building a portfolio that depends almost exclusively on the continued success of that theme introduces its own set of risks. Valuation compression, temporary spending pauses, or simply the natural desire of capital to explore alternatives can all produce stretches of underperformance. Maintaining some exposure to quality businesses that compound value through different channels provides a form of insurance.
That insurance does not have to be expensive. Many of the non AI compounders trade at multiples that look reasonable relative to their growth rates and balance sheet strength. The opportunity cost of holding them during periods of extreme technology outperformance has been real, yet the diversification benefit becomes more apparent precisely during weeks like this one.
A Personal Perspective On Market Concentration
Having observed multiple market cycles, I remain respectful of the power of concentrated leadership when the underlying businesses are executing at a high level. The returns generated by the leading technology companies over the past several years have been extraordinary and largely justified by fundamental progress. Dismissing that progress would be a mistake.
Yet I also remain wary of any market structure in which nearly half the value resides in names tied to one overarching narrative. Markets function best when capital is allocated across a range of ideas and business models. Extreme concentration can be both a source of strength and a source of eventual vulnerability. This week offered a small reminder of the second possibility.
Whether the current relative strength in non AI stocks proves temporary or the start of something more lasting will only become clear with time. In the meantime the episode itself is worth noting. It demonstrates that the market still retains the capacity to surprise, and that leadership can shift even when the dominant story remains intact.
Final Thoughts On Navigating The Current Environment
The week just completed will likely be remembered as one of the clearer examples of non AI outperformance in recent memory. The size of the gap, the breadth of the participating sectors, and the backdrop of a softer main index all combine to make the move noteworthy. Investors who have felt the pull of concentration risk now have fresh data to consider.
None of this requires drastic action. Portfolios that already contain a thoughtful mix of growth themes and more traditional compounders are well positioned to weather either outcome. Those that have become heavily skewed toward the single most popular theme may want to review whether that positioning still matches their risk tolerance and time horizon.
Markets will continue to evolve. New technologies will emerge, capital will chase the next compelling narrative, and periods of narrow leadership will alternate with periods of broader participation. The ability to recognize those shifts, even in their early stages, remains one of the more useful skills an investor can cultivate. This week provided a useful case study in that recognition process.
Stay attentive to relative performance. Keep an eye on the businesses that have been overlooked. And remember that even the strongest themes eventually share the stage. The companies that delivered this week’s gains may not redefine the market on their own, but they serve as a reminder that opportunity often appears in the places that have been receiving less attention.
In the end the healthiest approach combines respect for the powerful secular trends currently shaping technology with a willingness to maintain exposure to quality businesses operating in different arenas. That balance is never perfect, yet it tends to serve investors well across full market cycles. This week simply made the case for that balance a little more visible than usual.