
I’ve been watching the tape long enough to know when the market starts talking to itself in nervous half-sentences. That is exactly the feeling hanging over futures this morning. Prices are only fractionally lower after an ugly overnight session, yet the tone is different. Traders are bracing for Nvidia’s first earnings report without its longtime leader at the helm, and the combination of tighter AI chip rules plus fresh regional friction has everyone second-guessing the growth story that carried stocks for months.
Futures Mixed As Growth Fears Meet Geopolitical Noise
As of the early hours, S&P futures sat about a tenth of a percent lower while Nasdaq contracts managed to claw back an earlier drop and turn modestly higher. Dow futures lagged, down more than half a percent. That follows a sharp Monday session in which the S&P dropped nearly two percent, the Nasdaq 100 lost close to three percent, and the VIX pushed above 23. The selloff left a mark that still has not fully healed.
Most of the Mag 7 names trade in the red in premarket action. Meta and Alphabet lead the declines on the downside, while Intel slides sharply after a filing showed a reduced stake by Nvidia. The pattern is familiar: smart-money exits tend to show up first in the quieter corners before the broader tape catches on.
Why Nvidia’s Print Matters More Than Usual
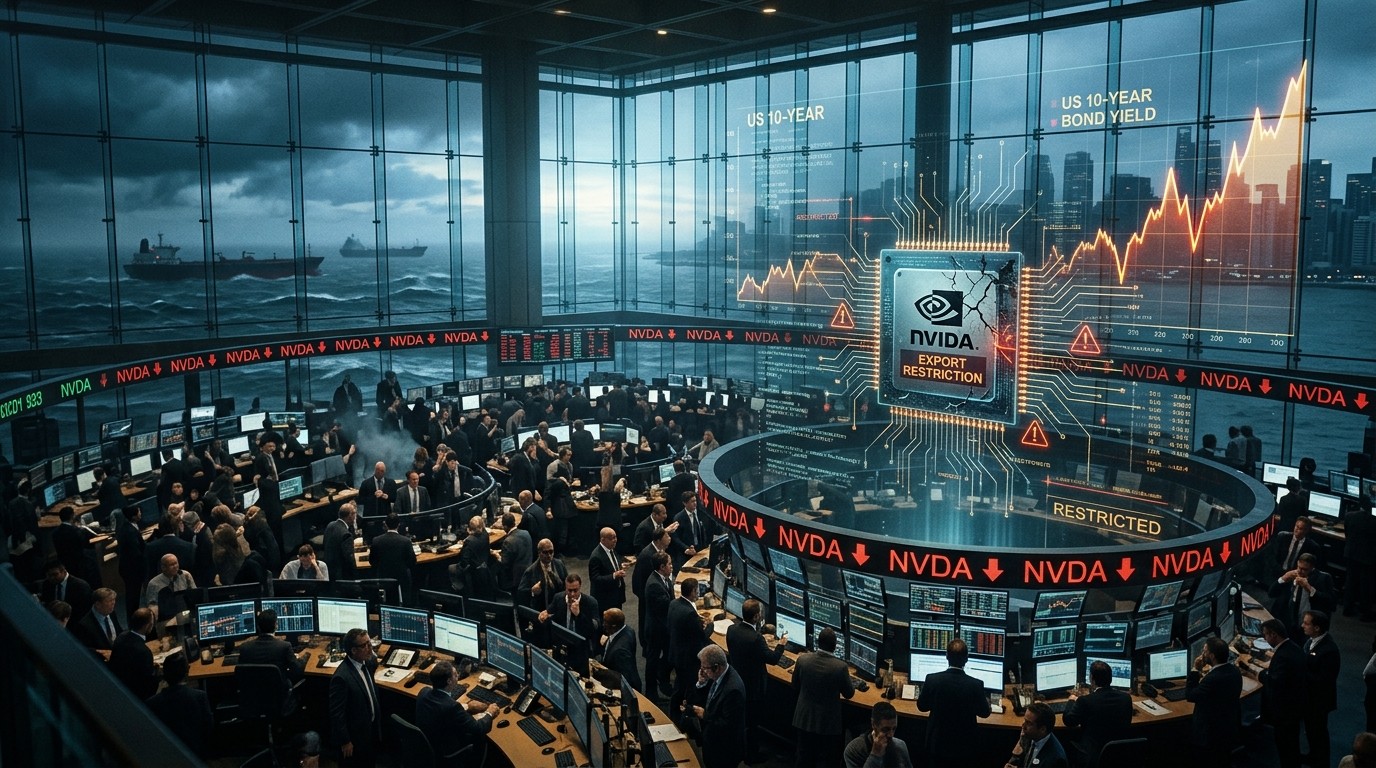
Nvidia reports after the close under unusual circumstances. There is no permanent chief executive in place. The board has formed a new national security and export control committee. Washington recently closed what many called the cloud loophole that allowed remote access to advanced chips. Options markets are pricing a move of nearly eight percent, and one-month implied volatility sits at its highest level heading into a print in quite some time.
Some desks assign a non-trivial chance that guidance gets pulled entirely until leadership is clarified. That possibility alone is enough to keep risk appetite on a short leash. I’ve found that when markets start pricing the chance of no guidance at all, the usual post-earnings relief rally becomes far less reliable.
The earnings results are going to be very strong. That’s not necessarily going to underpin the market, particularly because there’s so much else going on.
That assessment captures the mood. Near-term numbers may look solid, yet the real debate centers on what multiple investors are willing to pay for earnings that stretch into 2028 and beyond under a more fragmented AI supply chain.
The Defensive Rotation Is Loud And Clear
Consumer staples have opened up their widest premium over technology names in more than a decade. That is not a subtle shift. Money is moving into anything that does not depend on data-center power or advanced accelerators. Utilities have outperformed longer-duration Treasuries by a wide margin over recent sessions, a three-sigma move that underscores how extreme the preference for defense has become.
In my view the rotation feels less like a temporary pause and more like a genuine reassessment of where growth will actually materialize. When staples command that kind of relative premium, equity investors are not abandoning stocks entirely. They are simply refusing to pay up for the most AI-exposed parts of the market.
- Technology and semiconductor names remain under pressure across regions
- Defensive sectors continue to attract steady inflows
- Relative valuations between staples and tech have reached multi-year extremes
- Positioning data shows hedge funds cutting long exposure in growth names for consecutive weeks
Asia Feels The Export Rule Pressure First
Asian markets closed lower for a fourth straight session. The broader regional gauge dropped as much as 1.7 percent at one point. Korea and Taiwan, heavily exposed to the chip supply chain, have seen double-digit percentage declines this month. India, with far less direct AI exposure, has held up better and even posted gains.
Chinese AI-related names took another hit while domestic chipmakers rallied on the view that tighter U.S. rules will accelerate self-sufficiency efforts. Liquidity support from local authorities helped contain the damage on the mainland, yet the message remains clear: the AI ecosystem is becoming more fragmented, and the near-term capex outlook for export-dependent economies is under review.
Perhaps the most interesting aspect is how quickly the narrative shifted from pure growth optimism to questions about financing, leadership stability, and access to overseas compute power. Markets rarely move this fast without leaving scars.
Bonds Bid While Equities Price A Scare
Treasuries are firmer across the curve. Yields sit two to four basis points lower, and the curve is bull-steepening on haven demand. The ten-year yield has drifted toward 5.10 percent. European bonds are also stronger, with French paper leading after clarity around pension funding plans and UK gilts supported by softer labor data.
The contrast is striking. Equities are pricing a growth scare that the bond market has not fully embraced. Real and nominal yields remain elevated by recent standards. If equity weakness persists, the distribution of rate outcomes could shift quickly away from further tightening and toward a more cautious stance.
One strategist noted that the long end barely rallied on Monday despite falling oil, weaker stocks, and clear growth concerns. That reluctance to price a deeper slowdown leaves the rates market looking somewhat behind the equity tape.
Oil Shrugs Off Fresh Regional Claims
Crude prices remain near recent lows. WTI hovers around the mid-80s and Brent near the low 90s. Fresh claims of strikes and mine incidents near critical shipping lanes produced only a brief spike before the market returned its focus to ample supply and the restart of Iraqi flows through a key pipeline.
That muted reaction is telling. Physical markets appear well supplied, and traders are treating geopolitical noise as secondary to the broader demand picture. Gold holds near recent levels while silver shows modest strength. Copper remains stuck near multi-month lows, consistent with the cautious growth narrative.
Corporate Headlines Add Color But Not Clarity
Beyond Nvidia, the corporate calendar has delivered a mixed bag. One major home-improvement retailer posted better-than-expected comparable sales yet trimmed the upper end of profit guidance. An infrastructure consulting firm raised its longer-term outlook and saw shares jump. Several smaller names reported disappointing revenue or withdrew full-year targets, producing sharp declines.
Health insurers faced pressure after a proposed audit framework raised concerns about future margins. Meanwhile, reports of potential long-term memory chip supply agreements and preparations for large technology IPOs continue to circulate, though they have not been enough to offset the broader caution.
What Positioning Data Reveals
Hedge funds have sold equities for six consecutive weeks, a record stretch in some data sets. Retail investors have stepped in as buyers in recent sessions, particularly in the largest technology names. Systematic strategies have reduced exposure and sit modestly short U.S. equities. The technology long-short ratio in prime brokerage books has fallen to extremely low levels.
That cleaner positioning could limit further downside if Nvidia delivers a reassuring message. Conversely, any guidance disappointment or further negative headlines around leadership and export rules could trigger another wave of mechanical selling.
I’ve watched these cycles before. When positioning becomes this one-sided and volatility remains elevated, the market often needs a clear catalyst to decide whether the worst is already priced or whether another leg lower is still required.
European Markets Catch The Same Chill
European equities opened under pressure as the AI-related selloff rolled through time zones. Technology, resources, and autos lagged while travel names managed modest gains. Individual stocks reacted to company-specific news, including takeover approaches and rating changes, yet the dominant theme remained the same: caution around growth-sensitive sectors.
Economic survey data offered a small positive surprise in one major economy, but it was not enough to change the overall tone. Bond markets in the region continue to benefit from the broader risk-off bias and local political developments that have clarified fiscal intentions in certain countries.
Currency Markets Reflect Haven Demand
The dollar snapped a multi-day winning streak. The yen led G10 performance on classic haven flows, briefly pushing the dollar-yen rate lower. The euro and pound held relatively steady after mixed labor data in the United Kingdom. Softer wage growth has slightly reduced expectations for aggressive tightening, though the overall policy path remains data-dependent.
Currency traders are watching the same catalysts as equity desks. A weak Nvidia reaction could further pressure the dollar if it reinforces growth concerns, while a resilient print might allow the recent dollar strength to reassert itself.
The Day Ahead Holds Multiple Variables
Today’s calendar includes retail sales, industrial production, housing market data, and several Federal Reserve speakers. The Treasury will also auction short-term bills. Any of these could move the needle, yet most attention remains fixed on the after-hours earnings release.
Retail sales are expected to show modest growth after a stronger prior reading. Industrial production is seen largely flat. Housing sentiment remains subdued. Speakers will be parsed for any shift in the balance of risks around further policy tightening.
- Watch the retail sales print for signs of consumer resilience or fatigue
- Listen for any change in tone from Fed speakers on the path of rates
- Monitor premarket reaction in semiconductor names ahead of the close
- Assess whether Nvidia reiterates longer-term growth targets or introduces new caveats
Longer-Term Questions Linger
Beyond the immediate reaction, larger questions remain. How much of the AI investment boom was predicated on unrestricted access to leading-edge chips and overseas compute capacity? What happens to capital spending plans if supply chains fragment further? Can the broader market continue to expand if the single largest growth driver faces structural headwinds?
Some observers already describe the U.S. economy as showing early signs of stagflation dynamics: rising credit spreads, consumer fatigue in housing, and heavy reliance on one technology theme. Whether that framing proves accurate will depend in part on what companies say over the coming weeks about actual demand and financing conditions.
In my experience, markets can tolerate uncertainty for a while. They struggle when uncertainty compounds across leadership, regulation, and end-demand at the same time. That is roughly the position investors find themselves in today.
Putting The Pieces Together
Futures are mixed because the market is genuinely unsure. Bonds are bid because growth concerns are real enough to attract haven flows. Oil is largely ignoring the latest regional claims because physical supply looks comfortable. Technology leadership is under review, and the largest single name in the sector faces an unusually difficult communications challenge this evening.
None of this guarantees a further selloff. Positioning is cleaner than it was a few weeks ago. Retail support has appeared in key names. Near-term earnings for many companies remain solid. Yet the risk of another mechanical leg lower exists if the after-hours report fails to reassure on the medium-term outlook.
The next few sessions will tell us whether equities have overreacted or whether rates and currencies still have catching up to do. Either way, the comfortable growth narrative of recent months has given way to a more complicated picture. Traders who treat the current environment as business as usual may find themselves surprised by how quickly conditions can shift when leadership, regulation, and demand questions arrive together.
For now the market waits. The numbers will arrive after the close. The real test will be how investors choose to interpret them against a backdrop that already feels more fragile than it did only a short time ago.
That fragile feeling is what keeps me watching the overnight action more closely than usual. When futures are mixed, bonds are quietly bid, and the single most important earnings print of the season arrives under a cloud of leadership and regulatory uncertainty, the path of least resistance is rarely straight up. The coming hours will reveal whether the growth scare remains just that—a scare—or the start of a more sustained reassessment.