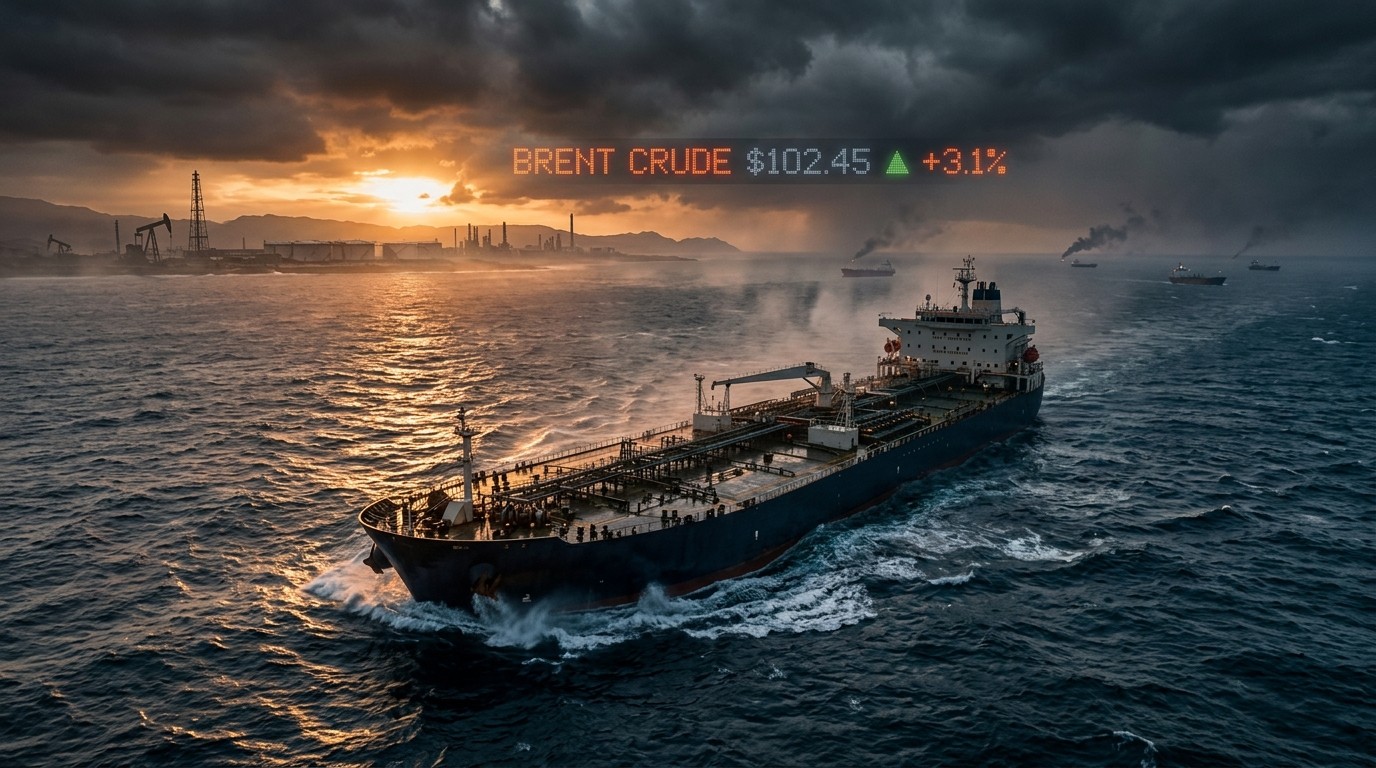

Have you ever watched a single stretch of water hold the entire world economy hostage? That is exactly what happened this week when oil prices exploded higher and U.S. crude finally punched through the $100 mark. I kept refreshing the numbers Friday morning, half expecting them to reverse, but they just kept climbing. West Texas Intermediate futures jumped 2.9 percent to settle around $100.78 a barrel while Brent, the global benchmark, climbed even harder, up 3.3 percent to $109.37. The catalyst felt almost inevitable once the details started rolling in.
Why Oil Suddenly Crossed The Century Mark
Three separate pressure points collided at the same time, and markets reacted the way they always do when supply looks shaky. First came the escalation in the Strait of Hormuz. At least nine commercial ships took fire this week in or near that narrow chokepoint. One Iranian missile strike reportedly sank the container vessel GFS Pride right in the strait on Wednesday. When vessels start going down in the corridor that carries roughly a fifth of the world’s seaborne oil, traders do not wait for official confirmations. They buy first and ask questions later.
Second, the so-called energy ceasefire between Russia and Ukraine collapsed almost as quickly as it appeared. Moscow kept hitting Ukrainian infrastructure. Kyiv answered by promising to resume attacks on Russian oil refineries. I have followed enough of these cycles to know that once both sides start targeting energy assets again, the risk premium does not fade overnight. It sticks around and pushes prices higher.
Third, and this one often gets overlooked in the geopolitical noise, U.S. commercial inventories posted a hefty draw of more than eight million barrels for the week ended October 9. Hurricane Isaias forced production shut-ins along the Gulf Coast, and the numbers showed it. When physical supply tightens at the same moment that shipping lanes look dangerous, the market has every reason to reprice higher.
The Strait Of Hormuz Remains The World’s Soft Spot
Anyone who has studied energy markets knows the Strait of Hormuz is not just another waterway. It is the single most important oil transit route on the planet. Roughly twenty percent of global petroleum liquids pass through those waters every day. When ships start taking missile fire, the insurance premiums spike, some operators refuse the voyage entirely, and the ones that continue demand higher freight rates. All of that cost flows straight into the price of crude.
I remember previous flare-ups in the same region. Prices rarely stayed calm once the shooting started. This time the attacks appear more frequent and more deliberate. Nine vessels in a single week is not a random incident. It is a pattern, and markets hate patterns that threaten consistent supply. The fact that a container ship was sunk adds another layer of seriousness. Container ships are not tankers, yet their presence in the same corridor still raises the overall risk temperature for every vessel nearby.
Traders are already pricing in the possibility of further disruptions. Some are quietly shifting cargoes to longer routes around Africa, which burns more fuel and takes extra days. Those extra days and extra costs eventually show up at the pump and in industrial energy bills. It is a slow-motion tax on the global economy, and right now it is being collected in real time.
Ukraine And Russia Reopen The Energy Front
The energy ceasefire that was supposed to calm things down lasted about as long as a summer rainstorm. Russia continued its strikes on Ukrainian power and energy infrastructure. Ukraine’s leadership responded by stating clearly that attacks on Russian refineries would resume. That single statement changed the tone of the market overnight.
Russian refining capacity has already taken hits in previous rounds of drone and missile exchanges. Every successful strike reduces the volume of refined products available for export or domestic use. Even if the crude itself still flows, the ability to turn it into gasoline, diesel, and jet fuel gets constrained. Markets understand that distinction. They treat refinery outages almost the same way they treat crude production cuts.
In my view, the most interesting part is how quickly both sides abandoned the informal truce. It suggests that energy infrastructure remains a high-value target for both parties. As long as that remains true, the risk of further supply interruptions stays elevated. That risk does not need to materialize fully to keep prices supported. The mere possibility is enough.
Inventory Draws And Hurricane Disruptions Add Extra Fuel
While the geopolitical headlines grabbed most of the attention, the physical market was already tightening. The weekly inventory report showed a draw exceeding eight million barrels. That is a sizable number in normal times. When it arrives alongside production shut-ins caused by a hurricane in the Gulf of Mexico, it becomes even more significant.
Gulf Coast platforms and refineries are designed to handle storms, yet every major weather event still forces temporary closures. Workers evacuate, production gets curtailed, and pipelines slow down. The lost barrels do not magically reappear the next week. They create a hole in the inventory data that traders notice immediately. Combined with the Hormuz and Russia-Ukraine developments, the inventory draw simply confirmed what the price action was already screaming: supply is under pressure from multiple directions at once.
I have watched similar confluence events before. When weather, geopolitics, and inventory data all point the same way, the resulting move can be sharper and more sustained than any single factor would produce on its own. That is the situation we are in right now.
How Traders And Markets Are Positioning
Futures volumes picked up noticeably on the break above $100. Some participants had been waiting for that psychological level for months. Once it cleared, momentum buyers stepped in and short covering accelerated the climb. Brent’s move above $109 shows the international market is even more sensitive to the Hormuz risk, which makes sense given its greater exposure to Middle East flows.
Refiners are watching crack spreads carefully. Higher crude costs squeeze margins unless product prices rise in tandem. So far the product markets have kept pace, but any further crude spike could test that relationship. Airlines, trucking fleets, and chemical producers are already recalculating their near-term energy budgets. None of them enjoy the current environment.
Perhaps the most telling signal is the behavior of longer-dated contracts. They have risen as well, though not as dramatically as the front month. That suggests the market expects the risk premium to persist for a while rather than vanish after a single quiet week. In my experience, when the back end of the curve starts lifting, the price floor tends to firm up.
Broader Economic Ripples Already Visible
Oil at these levels does not stay confined to the energy sector. Transportation costs rise. Manufacturing input prices climb. Inflation readings that had been cooling get a fresh upward nudge. Central banks that were hoping for cleaner data now face a new complication. None of this is theoretical. It is already showing up in freight rates and fuel surcharges.
Emerging markets that import most of their energy feel the pinch first and hardest. Currency pressures can follow if oil stays elevated for long. Even large economies with domestic production are not immune. Higher global prices eventually filter through to local retail markets one way or another.
I keep coming back to the simple arithmetic. The world still runs on oil. When the reliable delivery of that oil looks less reliable, the price adjusts upward until demand softens or new supply appears. Right now neither of those offsets is immediate. Demand remains reasonably firm and new supply takes time to bring online.
What History Suggests About The Next Few Weeks
Looking back at previous Hormuz crises and periods of Russia-Ukraine energy targeting offers a few useful patterns. Prices often overshoot on the way up, then settle into a higher range rather than collapsing back to the prior baseline. The risk premium can linger for months even after the most dramatic incidents fade from the headlines.
Inventory rebuilds after weather events also take time. Production platforms do not restart at full capacity the day after a storm passes. Maintenance schedules get rearranged and some deferred work gets completed while crews are already mobilized. Those temporary losses can stretch longer than the weather maps initially suggested.
If further ship attacks occur or if additional Russian refineries go offline, the next leg higher could arrive quickly. Conversely, any genuine de-escalation in either theater would likely trigger profit-taking. The market is coiled tightly around these two geopolitical threads. Whichever one moves first will set the tone for the rest of the month.
Key Factors Worth Watching Closely
Several concrete items will determine whether $100 becomes a floor or a temporary ceiling.
- Frequency and severity of further incidents in the Strait of Hormuz
- Actual damage reports from any new Ukrainian strikes on Russian refining assets
- Pace of Gulf Coast production recovery after the hurricane-related shut-ins
- Weekly inventory data over the next two or three reports
- Statements from major producers about their willingness to offset any lost barrels
Each of these can swing the balance. A quiet week in Hormuz combined with steady inventory builds would ease pressure. Another sunk vessel or a successful strike on a large Russian facility would do the opposite. The market is listening for every scrap of information.
How Different Players Are Adjusting
Producers with spare capacity are quietly happy. Higher prices improve cash flow and justify previously marginal projects. National oil companies in particular benefit when the global marker rises, even if their own production stays flat.
Consuming nations are less pleased. Strategic petroleum reserves exist for moments like this, yet most governments prefer not to tap them unless the situation becomes extreme. Coordinated releases can calm markets temporarily, but they also signal that officials are worried. That signal itself can sometimes amplify volatility.
Refiners sit in the middle. They need crude, but they also need product cracks wide enough to absorb the higher feedstock cost. Some are already optimizing runs toward the most profitable products and delaying lower-margin operations. That kind of operational flexibility helps in the short run yet cannot fully insulate them from a sustained crude rally.
The Psychological Barrier Of One Hundred Dollars
Numbers matter in markets. Crossing $100 is not just arithmetic. It is a headline that reaches far beyond trading floors. Consumers notice. Politicians notice. Corporate treasurers notice. The round number carries emotional weight that $97 or $103 simply do not. Once the barrier is broken, a new reference point forms in the collective mind.
I have seen this happen with other commodities and equity indexes. The first sustained close above a major round level often invites a period of consolidation as the market digests the new reality. Sometimes the consolidation is brief. Sometimes it lasts weeks. Either way, the fact that the level has been conquered changes the conversation from “will it happen” to “how high can it go.”
That shift in framing is already underway. Analysts who spent the summer debating whether $90 was sustainable are now modeling scenarios that include $110 and beyond. The distribution of possible outcomes has moved higher, and positioning will gradually reflect that shift.
Supply Chains Feel The Strain In Real Time
Shipping companies that still transit the strait are rewriting their risk assessments daily. Some are adding armed security. Others are rerouting entirely. Both choices cost money. Those costs get passed along the chain until they reach the final buyer of the crude or the products refined from it.
Insurance markets are adjusting premiums higher for any voyage that includes the high-risk zone. Higher insurance is another form of price increase that never appears in the official crude quote yet still affects the delivered cost. In that sense the headline price understates the true economic impact.
Port congestion can also develop if vessels delay entry or wait for clearer security conditions. Delays compound. A few days of hesitation at the strait can create knock-on effects at discharge ports thousands of miles away. The global oil logistics system is finely balanced. Sudden risk aversion throws that balance off.
Longer-Term Implications For Energy Strategy
Events like this week’s surge reinforce a lesson that policymakers keep relearning. Concentrated transit routes create concentrated vulnerability. Diversifying supply sources and expanding alternative routes sound straightforward on paper. In practice they require years of investment and diplomatic coordination.
Some countries will accelerate efforts to secure non-Hormuz barrels. Others will revisit strategic stockpile targets. A few may push harder on domestic production incentives. None of these responses will lower prices next week, yet they shape the landscape for the next decade.
Meanwhile the immediate market remains focused on the next tanker transit and the next drone report. The long-term planning and the short-term trading coexist uneasily. Both are rational reactions to the same underlying fragility.
A Personal Observation On Market Psychology
Watching prices climb this fast always brings a familiar mix of excitement and unease. The excitement comes from seeing a clear fundamental story play out in real time. The unease comes from knowing that rapid moves often overshoot and then correct sharply. I have learned to respect both impulses.
Right now the fundamental story looks solid. Multiple independent sources of supply risk are active simultaneously. Inventory data supports the direction of the move. Positioning had room to expand once the $100 level gave way. That combination is powerful.
At the same time, markets are forward-looking. If the next few weeks bring even modest de-escalation, a portion of the risk premium will unwind. The speed of that unwind could surprise people who assume the new higher range is permanent. Balance is the hardest thing to maintain when headlines are this loud.
Practical Takeaways For Different Audiences
For industrial energy users, the message is straightforward. Budget for higher costs in the near term and explore any available hedging windows while liquidity remains decent. Waiting for perfect clarity usually means paying a steeper price later.
For investors focused on the energy complex, the environment favors producers with low break-even costs and flexible marketing arrangements. Downstream businesses face more margin pressure until product prices fully catch up.
For policymakers, the episode is another reminder that energy security and geopolitical stability remain tightly linked. Rhetoric about energy independence sounds different when tankers are under fire in a critical strait.
Ordinary consumers will feel the effects more gradually through higher gasoline and diesel prices, elevated airfares, and eventually broader inflation metrics. The lag between crude spikes and retail prices varies, yet the direction is rarely in doubt.
Looking Ahead Without The Crystal Ball
No one can say with certainty where prices will stand a month from now. What can be said is that the current set of risks is more intense than the set that existed at the start of the week. That intensity has already been translated into a higher price. Whether it intensifies further or begins to ease will decide the next chapter.
I plan to keep a close eye on vessel traffic reports from the strait, official damage assessments from any new refinery incidents, and the upcoming inventory figures. Those three data streams will tell the story more accurately than any single forecast.
In the meantime the market has delivered a clear verdict. When the world’s most important oil artery looks less safe and major refining capacity sits in the crosshairs, $100 is no longer an ambitious target. It is the new starting point for the conversation. How long that conversation stays elevated depends on events still unfolding on the water and in the skies above contested territory.
The coming days will reveal whether this week’s surge marks the beginning of a sustained higher range or simply a dramatic spike that eventually fades. Either outcome will carry consequences that stretch far beyond the trading screens. For now the screens are flashing a number that many thought was months away. Reality arrived early, and the market is still adjusting to its presence.
One final thought. Energy markets have a way of reminding everyone that geography still matters. Pipelines and tankers follow the same physical constraints they always have. When those constraints tighten, prices respond. This week the constraints tightened from three different directions at once. The result is a crude market that has rediscovered the century mark and shows little immediate interest in retreating. That is the reality traders, companies, and consumers all have to navigate from here.