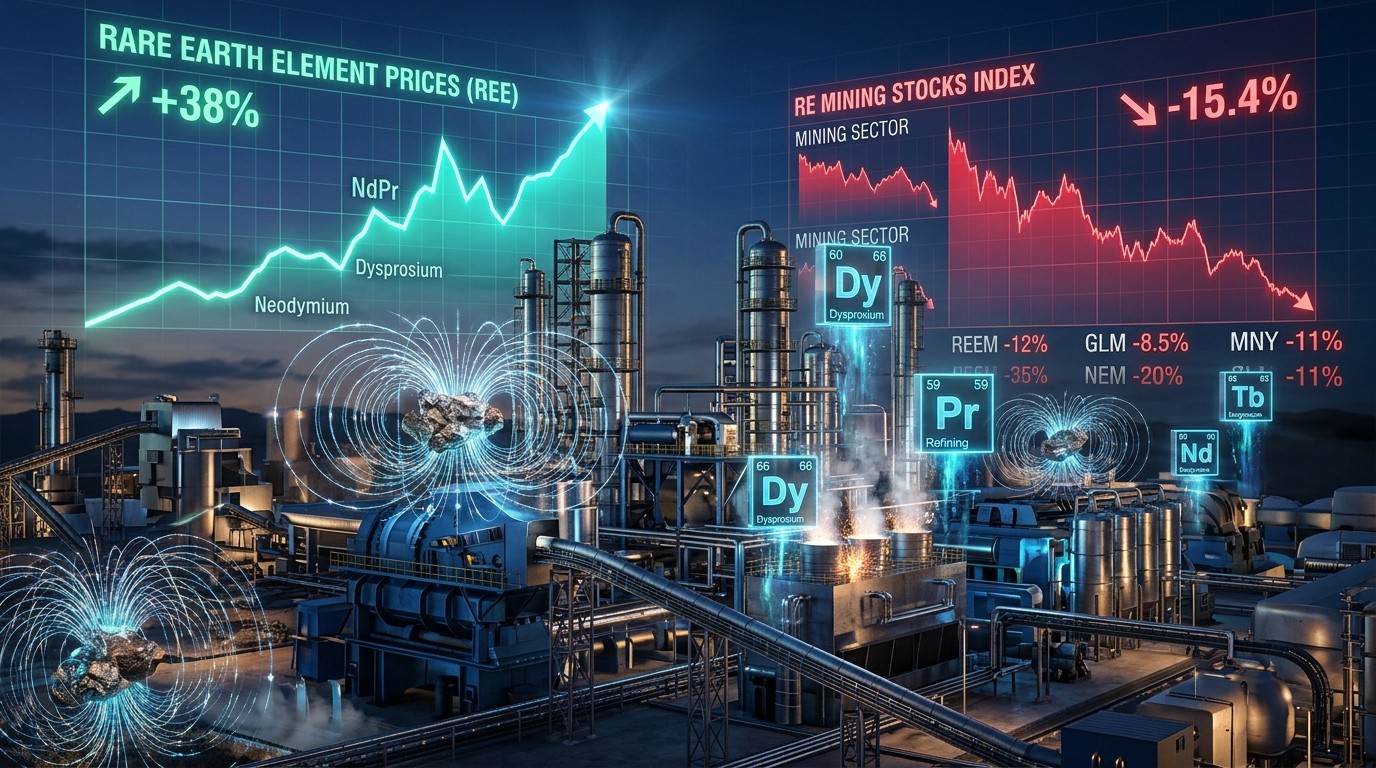

Here’s a puzzle that keeps me up at night more than it probably should. China still holds the keys to the rare earth spigot. The latest high-level talks between leaders changed almost nothing on that front. Japan is scrambling because yttrium supplies are running critically low. Washington has drawn a clear line in the sand with a $110 per kilogram floor under NdPr. And Western buyers? They’re shelling out anywhere from five times to a staggering 346 times the Chinese price for certain heavy rare earths. So why, exactly, are rare earth stocks down for the year?
That question sits at the heart of a growing disconnect that feels almost deliberate. The physical market is flashing green lights in almost every direction. Demand keeps getting revised higher. Governments are writing price floors and offtake agreements. Premiums for material outside China have ballooned into territory that would have seemed impossible two years ago. Yet the equities that should be riding this wave are stuck in reverse. I’ve watched this sector long enough to know that when fundamentals and share prices diverge this sharply, something eventually gives. The only real debate is whether the catch-up happens through a sudden policy headline or a slow grind higher once macro pressure eases.
The Numbers Tell a Story Markets Refuse to Hear
Year to date the picture is almost cartoonish in its contrast. Ex-China NdPr prices have climbed roughly 23 percent. At the same time a basket of rare earth producers has dropped about 28 percent on average. Developers have held up a bit better, but even there the average is still down around 17 percent once you strip out the one or two outliers that managed to climb. The broad rare earth ETF that many investors use as a proxy peaked in the spring and has since given back a large chunk of those gains, sliding from north of $100 into the high $50s.
Look across the producer list and the pain is widespread. Flagship names in Australia, the United States and elsewhere are all deep in the red for the year. Even some of the large Chinese producers sit lower than where they started January. On the developer side the damage is more mixed but still ugly for most. A handful of names have held or gained ground, but the majority have seen declines of 35 to 60 percent. One analyst team put it bluntly: they question how equities have performed so poorly despite strong underlying market fundamentals.
In my view that underperformance has less to do with the rare earth story itself and more to do with the broader environment. Higher yields, wobbling technology stocks, and a general aversion to long-duration, capital-intensive projects have pulled capital away from the entire space. The commodity is behaving like a strategic asset. The stocks are trading like a classic risk-off casualty. That gap is the opportunity, or the trap, depending on your time horizon.
Price Floors Changed the Game More Than Most Realize
Perhaps the single most important structural shift of the past year is the arrival of real price support from Western governments. The United States set a floor of $110 per kilogram for NdPr tied to one major domestic producer. Similar arrangements have appeared for other projects involving Japan and additional U.S. support. One developer even secured floors on dysprosium and terbium at levels that would have looked aggressive not long ago: $575 per kilogram for dysprosium and more than $2,000 for terbium.
What nobody fully expected is that those floors would help stabilize Chinese pricing as well. For years Beijing used quotas, policy shifts and later export controls to swing NdPr prices from roughly $175 per kilogram down toward $50 and back again. That volatility made project financing nearly impossible for Western developers. Over the past ten months, however, Chinese prices have begun to cluster around the same $110 level that Washington put in place. The wild swings that used to define the market have largely disappeared.
That stability should, in theory, make the equity story cleaner. Projects that once looked unbankable now sit on firmer ground. Yet investors are still assigning lower multiples to those same projects than they did at the start of the year. I’ve found that markets can stay irrational longer than project developers can stay solvent, but the current setup feels different. The safety net is real this time.
Two Markets, Wildly Different Prices
NdPr has largely become a single global market again, with Chinese and Western prices converging near the floor. Everything heavier tells a completely different story. Once China began rationing heavy rare earths, a thin and opaque Western market emerged for material that simply does not leave Chinese ports. The gaps that opened up are extreme.
Dysprosium in Rotterdam has traded around $1,074 per kilogram against roughly $227 inside China. Terbium has sat near $4,594 versus $983. Those numbers already look dramatic. Then you get to the lesser-known elements. Yttrium oxide has averaged about $8 per kilogram in China over the past five years. European spot has been quoted near $740. Some U.S. quotes have gone as high as $1,750. That is an 85-fold premium in the more conservative comparison. Gadolinium has traded at roughly ten times the Chinese price in certain North American markets, with CIF quotes reaching $3,100 per kilogram in extreme cases.
Samarium, critical for the samarium-cobalt magnets used in missiles, fighter jets and radar systems, has shown the most extreme disconnect of all. CIF North America prices have reached 346 times the Chinese level. That is not a typo. Three hundred and forty-six times.
The shortage is not theoretical. Japan has made urgent requests for help resolving its yttrium crisis, warning of severe shortages by year-end. Inventories are plunging. Outside China the oxide has been quoted near $1,150 per kilogram against roughly $9 inside China. That is a 179-fold increase over two years. Reports suggest China is delivering only about two-thirds of the rare earths it committed to under earlier agreements, and Japan is receiving the bare minimum. High-level talks produced a short truce rather than a lasting solution, and markets largely shrugged it off.
Analysts are careful to note that the ex-China market for dysprosium and terbium remains tiny, only a few hundred tonnes against a Chinese market more than twenty times larger. They also question whether current Western premiums are fully sustainable. Some magnet makers are already exploring shifts toward lower-cost ferrite alternatives. Even after applying meaningful haircuts, however, the forecast still leaves integrated Western producers capturing premiums that would have been unimaginable in 2023.
Demand Keeps Getting Revised Higher
While the supply side is constrained, the demand side keeps surprising to the upside. Updated forecasts now show NdFeB magnet demand growing at a compound annual rate of about 7.3 percent through 2035, reaching roughly 365,000 tonnes. That figure sits 15 percent above previous estimates. Electric vehicles remain the largest single driver, with unit forecasts climbing toward 52 million by the middle of the next decade. But newer categories are gaining weight: data-center cooling motors, e-bikes and scooters, and drones.
Drones currently represent only about one percent of the modeled demand. Yet military production estimates from ongoing conflicts already run into the millions of units. Those numbers suggest the formal forecasts may still be conservative. Then there are humanoid robots. Some models now assume deliveries growing at a 45 percent compound rate to 2.5 million units by 2035. One major automaker is reportedly preparing production lines designed for a million robots a year. For context, global electric vehicle sales rose more than 4,600 percent between 2014 and 2024. Whether the robot curve follows a similar path is anyone’s guess, but the magnet math becomes uncomfortable very quickly if it does.
Netting the supply and demand numbers produces a clear picture. The global NdPr market is expected to remain in deficit through 2028, roughly 7 percent short this year. A period of approximate balance follows as several new projects and expansions come online. Then the deficit reopens and deepens, reaching about 10 percent by 2035. The combined dysprosium and terbium balance follows a similar trajectory, ending the period with a 12 percent shortfall.
The West’s Hidden Bottleneck
The bullish case grows even stronger once the focus moves beyond the mines themselves. Ex-China NdFeB magnet capacity is projected to rise more than 300 percent by 2030, reaching around 70,000 tonnes. That sounds impressive until you realize it would still represent only about 23 percent of global capacity, with China controlling the rest.
Even that modest share may prove difficult to achieve because the West is missing a critical intermediate step. Global capacity for NdFeB metallization and alloying sits near 210,000 tonnes this year, and more than 90 percent of it remains under Chinese control. Ex-China capacity is expected to roughly double to 38,000 tonnes by 2030. That expansion falls well short of the planned Western magnet plants. Lead times for the specialized strip casters needed in the process now stretch up to two years, and sourcing those machines from China has become effectively impossible under current export rules.
This industrial bottleneck, rather than a pure geological shortage, is what many observers now see as the real constraint. China is likely to maintain market dominance for years. Shortfalls in Western supply, combined with the high probability of ongoing Chinese export controls, support the idea of persistently bifurcated markets and meaningful pricing premiums for anything produced outside China. The scarcity premium is structural, not cyclical. Equity markets, for the moment, are treating it as temporary.
Valuations Look Like a Fire Sale
On a price-to-net-asset-value basis the producer coverage trades at an average of roughly 0.57 times. Developers sit even lower, around 0.47 times. Those multiples imply substantial upside if the underlying forecasts prove anywhere close to accurate. One major producer carries more than 100 percent upside to the analyst target. Another sits near the same level after a target increase. A third developer shows potential upside above 200 percent. Even after some target cuts tied to project delays, the remaining upside remains large.
Rating changes have been mixed. One name moved to Hold after becoming the subject of an all-scrip takeover. Another shifted to Speculative Buy purely on valuation grounds even though its target price was reduced, simply because the share price had fallen further and faster. Price targets have a habit of following prices rather than leading them, of course. Still, the current setup leaves the sector trading at roughly fifty cents on the dollar relative to conservative net asset values.
Some of the selling pressure is entirely rational. These are long-duration projects that require heavy capital spending. When the ten-year yield sits above 5 percent and speculative capital is scarce, duration assets suffer. Macro pressure explains part of the disconnect. It does not erase the fundamentals.
A Parallel Story in Tungsten
Tungsten is not a rare earth, but it sits in the same strategic category and displays an even sharper version of the same pattern. China controls roughly 80 percent of global supply. One prominent Western producer has watched its shares fall more than 60 percent from their spring peak and trade back near levels seen at the start of the year, even after a recent investor day.
Operations at its flagship project have moved in the right direction. Production has begun and is ramping toward continuous operations, with first concentrate shipments expected soon. Cost curves are projected to improve dramatically as volumes rise. Balance sheets look solid, with meaningful net cash positions. Yet the stock continues to struggle.
Part of the pressure comes from soft spot prices for concentrate. Western ammonium paratungstate has slipped from above $3,000 per metric ton unit toward $2,700. Chinese prices have retreated further. One careful explanation points out that Western processing plants are already running at capacity under long-term contracts and simply cannot absorb additional concentrate. Finished product remains tight even while concentrate appears soft. Looking further out, new defense procurement rules taking effect in 2027 will make Chinese or Russian origin material ineligible for U.S. contracts even if processed in a third country. Strategic stockpiles are reported as nearly depleted. The rearmament order book is expected to run strong from 2027 through 2030. Futures contracts for the metal are in the planning stages for early 2027.
In short, the spot market is pricing today’s processing bottleneck. The equity is pricing the spot market. The demand cliff that begins in 2027 is priced almost nowhere. The pattern feels familiar.
Supply Security Moves Center Stage
At the major mining conferences this season the conversation has shifted. Governments are no longer simply talking about critical minerals. They are writing checks, accelerating permits, funding infrastructure, setting price floors and signing offtake agreements. Resource security has become a core industrial policy issue rather than a niche concern. The open question is whether the industry can actually deliver the supply that markets and policymakers are beginning to price in.
For rare earths the honest answer appears to be: not anytime soon, and not without continued reliance on Chinese material for a meaningful share of the chain. That reality is precisely why the companies capable of building scalable non-Chinese capacity probably should not be trading at half of net asset value on conservative assumptions.
When Macro Finally Lets Go
We have watched versions of this movie before. Physical tightness builds. Policy responses arrive. Equities lag for a while and then catch up violently once a clear catalyst appears. Today the ingredients are all present: a short trade truce with an expiration date, a Japanese government openly seeking yttrium help, a Western tungsten producer trading below even cautious targets just months before new sourcing rules take effect, a functional price floor that has turned NdPr into a market with a visible safety net, and an equity complex still valuing the West’s limited scalable capacity at a deep discount.
Demand is expected to remain robust as Western countries push harder to secure supply outside China and build independence across the magnet value chain. The disconnect between that outlook and current share prices is unlikely to last forever. History suggests it closes through a combination of policy headlines and improving risk appetite rather than through a sudden collapse in the physical market. Investors waiting for a perfect macro all-clear may find themselves buying the same names 50 percent higher once the turn arrives.
After all, nothing closes a half-NAV gap quite like a 346-times price premium that refuses to disappear. The physical market has already voted. The equity market is still making up its mind. In my experience, those two votes eventually align. The only real question is how much higher the stocks will be by the time they do.
The current setup is uncomfortable for anyone who believes markets are efficient in the short run. It is more interesting for anyone willing to look past the next quarter’s macro noise and focus on the multi-year structural shift underway. Price floors, export controls, rising magnet demand from vehicles, data centers, drones and eventually robots, and a Western processing gap that will take years to close all point in the same direction. The commodity is acting like the strategic asset it has become. The stocks have not yet caught up. That gap is the story of the year in critical minerals, and it is still very much open.