
Have you ever watched the numbers flash across the screen and felt that strange disconnect between what the data claims and what everyday life actually feels like? That exact sensation hit hard this morning when the latest retail sales figures landed. Headline numbers jumped higher than almost anyone expected, yet the mood among households remains stuck near rock bottom. The contrast is sharp enough to make you pause and wonder which story is closer to the truth.
The Startling Gap Between Spending And Sentiment
Retail sales climbed 0.8 percent from the previous month, well above the modest 0.3 percent rise that many had penciled in. On a year-over-year basis the gain reached 6.3 percent. At first glance those figures look like pure strength. People are still walking into stores and tapping their cards. Yet dig a little deeper and the picture grows more complicated. The so-called control-group sales, the slice that actually feeds into broader growth calculations, managed only a thin 0.1 percent increase after a much stronger prior month. That measure strips out the noisier categories such as gasoline stations, auto dealers, building materials, and food services. In other words, the core of goods spending that matters most for economic output barely moved.
I keep coming back to the same observation: households are still spending, but the composition of that spending is shifting in ways that feel less comfortable. Eight of the thirteen major categories posted gains. Furniture stores, electronics retailers, and restaurants all saw increases. At the same time, people pulled back on hobbies and building materials. The standout category, though, was gasoline stations. Sales there jumped 6.4 percent in value. That single line item explains a large share of the overall strength. When the price at the pump stays elevated for months, the dollar totals at the station climb even if the volume of fuel bought stays roughly the same.
Fuel Costs Quietly Rewrite Household Budgets
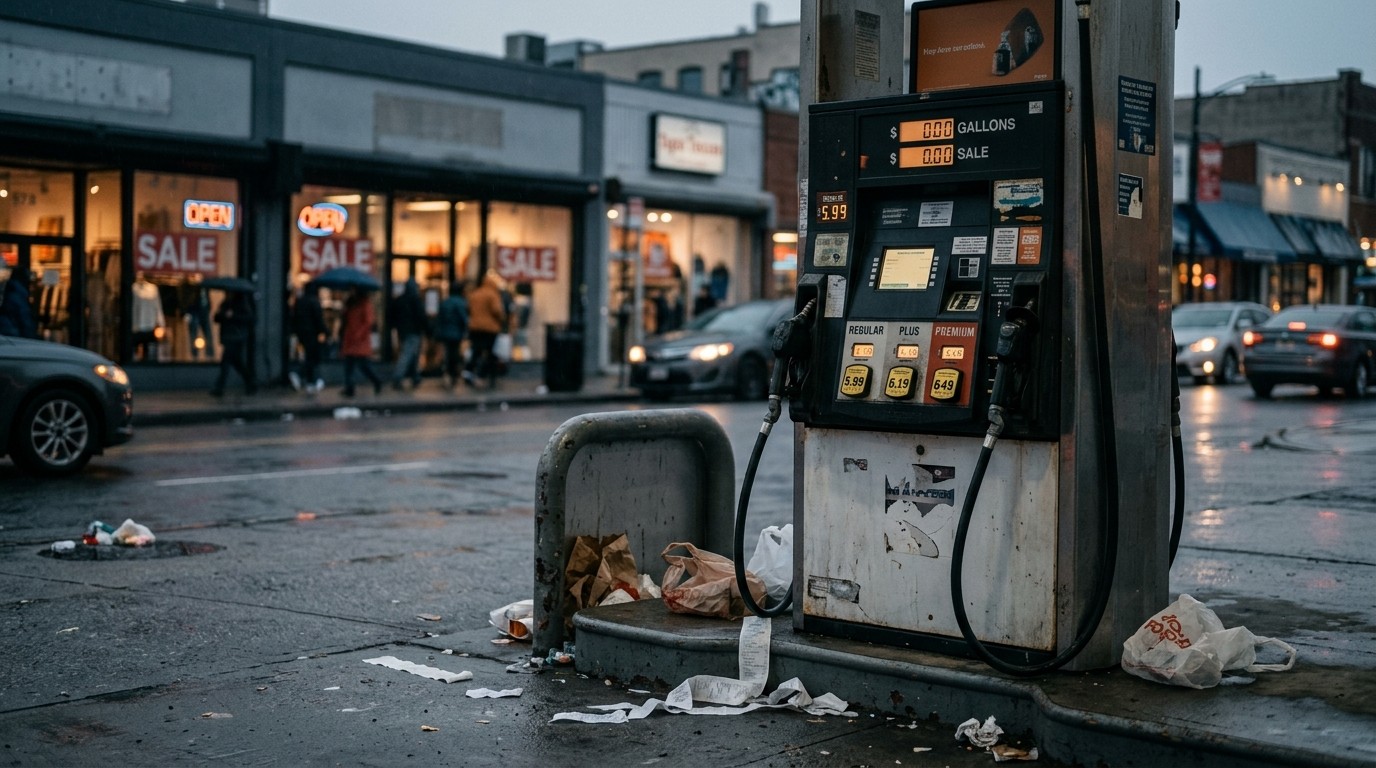
National average gasoline prices have lingered above the psychologically important four-dollar mark for three straight months. Diesel has stayed above five dollars and at times flirted with record territory. Those levels are not abstract. They show up every week when drivers fill their tanks. High-frequency card data reinforce the point. Fuel spending on credit and debit cards rose more than 20 percent in recent readings. Total card spending per household edged up only 0.2 percent on a seasonally adjusted basis in the latest month, slowing from a 1 percent gain earlier. Gas spending itself accelerated to a 5 percent increase from 3.1 percent the month before.
What happens next is almost predictable. Several other categories contracted. Home improvement dropped 1.6 percent. Department stores fell 1.1 percent. Clothing eased 0.9 percent. Furniture slipped 0.5 percent. Even restaurants and groceries showed small declines of 0.4 percent and 0.2 percent respectively. Online spending was essentially flat. The pattern suggests a classic substitution effect. Money that once flowed toward discretionary items is being redirected to the pump. It is not that people have stopped consuming; they are simply rearranging priorities under pressure.
Rising fuel bills are crowding out other purchases and translating into dismal consumer sentiment at a politically sensitive moment.
In my view this is the most interesting part of the entire release. Headline retail sales can look robust while the underlying experience of the typical household grows tighter. Executives at major food and restaurant chains have already acknowledged that many customers remain in a challenging environment. At the same time, several large banks continue to describe the consumer as resilient. Both statements can be true at once. Resilience does not mean comfort. It means people are still managing to spend, even if the choices feel more constrained than a year ago.
Why The Control Group Matters More Than The Headline
Economists pay special attention to control-group sales precisely because the broader figure can be distorted by volatile items. Gasoline is the clearest example. When prices surge, the dollar value of sales rises even if drivers buy fewer gallons. Building materials and auto dealers introduce their own swings. Food services sit outside the goods category that feeds most growth estimates. Strip those out and you get a cleaner read on underlying demand for core merchandise. That cleaner read showed only a 0.1 percent rise this time. After a strong prior month, the slowdown suggests consumers took a breather as the third quarter closed and price pressures continued to mount.
Faster inflation is taking a bigger bite out of paychecks. Real purchasing power erodes when the same paycheck buys less at the station and the grocery aisle. The effect is gradual rather than dramatic, which makes it easy to overlook until the cumulative impact becomes obvious. Card data already hint at that process. Softening across several major non-fuel categories points to budgets that are being squeezed at the margins.
Resilience Versus Comfort: Two Different Stories
It is worth distinguishing between resilience and ease. Loan growth and corporate activity remain healthy according to recent bank observations. Credit performance has not shown broad deterioration. Those signals argue against an imminent collapse in spending. Yet the same data set also shows fuel costs accelerating while other categories soften. The consumer is still present, still spending, still keeping the economy from tipping over. That presence does not erase the strain that appears in confidence surveys sitting near record lows.
Perhaps the most telling detail is how evenly the pressure is distributed. Lower-income households feel the fuel shock most acutely because energy and food take a larger share of their budgets. Middle-income families notice the trade-offs when they delay a home-improvement project or skip a clothing purchase. Higher-income households may absorb the higher pump prices with less visible sacrifice, yet even they contribute to the aggregate slowdown in certain discretionary categories. The result is a broad-based moderation that does not yet look like a full stop.
How Elevated Energy Prices Shape Daily Choices
Walk into any convenience store attached to a gas station and the behavioral shift becomes visible. Customers still buy coffee and snacks, but the basket often looks leaner. Some drivers fill only half a tank more frequently rather than topping off completely. Others adjust routes to shave a few miles. These micro-adjustments accumulate. Over weeks and months they free up just enough room in the budget to keep essential spending intact while trimming the optional items.
I have found that the psychological weight of seeing four-dollar gasoline every day is underappreciated. It becomes a constant reminder that costs remain elevated even when other inflation measures cool. That reminder feeds directly into the sentiment readings that sit at historic lows. People do not need a formal survey to know their budgets feel tighter. They experience it every time they swipe a card at the pump.
- Fuel spending continues to accelerate while several discretionary categories contract
- Control-group sales barely rose, signaling softer underlying goods demand
- Headline retail strength is heavily influenced by higher prices at gasoline stations
- Households appear to be reallocating rather than cutting spending outright
- Sentiment remains depressed even as absolute spending levels stay elevated
The combination creates a confusing public narrative. On one hand the economy keeps delivering solid sales totals. On the other hand the typical household reports feeling worse than the numbers suggest. Bridging that gap requires looking past the headline and into the composition of spending. Once you do, the story becomes clearer: higher energy costs are absorbing a larger share of the wallet, leaving less room for everything else.
What The Softening Categories Reveal
Home improvement spending fell notably. That category often serves as a proxy for confidence in the housing market and willingness to invest in longer-term projects. A 1.6 percent decline is meaningful. Department stores and clothing also retreated. These are classic discretionary areas where households can delay purchases without immediate consequences. Furniture showed a smaller but still negative reading. Even restaurants, which had been relatively resilient for much of the past year, edged lower. Groceries declining, however slightly, is harder to dismiss because food is less optional. Taken together the list paints a picture of selective restraint rather than broad retrenchment.
Online spending holding nearly flat is another useful signal. E-commerce had been a growth engine for years. A pause suggests that the overall pie is not expanding as rapidly as before, so dollars shifted toward fuel simply reduce the amount left for digital carts. None of these moves look catastrophic. They look like rational responses to a sustained increase in a non-discretionary cost.
The Broader Economic Implications
For growth calculations the control-group figure carries more weight than the headline. A 0.1 percent monthly rise after a strong prior reading implies that goods consumption contributed less to third-quarter activity than some had hoped. Services spending, including restaurants, remains an open question, but the goods side looks more muted. Inflation itself receives mixed signals. Higher gasoline prices feed into headline inflation measures, while softer demand in other categories may eventually ease price pressure elsewhere. The net effect depends on how long fuel prices stay elevated and how households continue to adjust.
Banks have described consumer spending, loan growth, and corporate activity as still healthy. Credit metrics have not flashed broad warning signs. Those observations argue that the economy retains underlying momentum. At the same time, the same institutions note that fuel costs are pinching budgets. The two observations sit side by side without contradiction. Momentum can persist even while margins of comfort narrow.
| Category | Monthly Change | Implication |
| Gasoline Stations | +6.4% | Primary driver of headline strength |
| Home Improvement | -1.6% | Clear discretionary pullback |
| Department Stores | -1.1% | Softness in broad retail |
| Clothing | -0.9% | Delayed non-essential purchases |
| Control Group | +0.1% | Muted core goods demand |
Looking across the table the pattern is consistent. Strength is concentrated in the category most directly tied to higher prices. Weakness appears in areas where households retain flexibility. That distribution is exactly what one would expect when a large, sticky cost center expands inside a fixed budget.
Sentiment At Record Lows Despite Solid Sales
Consumer sentiment surveys have lingered near historic troughs even as absolute spending has held up. The gap is not new, but it remains striking. People can continue to open their wallets while simultaneously reporting that they feel worse about their financial situation. Part of the explanation lies in the composition of spending already discussed. Another part lies in the cumulative effect of several years of elevated prices. Even if the pace of inflation has moderated in some areas, the price level itself remains much higher than it was before the recent surge. Households notice the level more than the rate of change once the rate has slowed.
Political calendars add another layer. Confidence readings often deteriorate in the months leading into major elections regardless of the underlying data. That tendency does not erase the economic substance behind the current readings. Fuel prices that stay high for months on end are a tangible, recurring reminder of cost pressure. When those prices coincide with softer discretionary spending, the sentiment numbers become easier to understand.
Substitution Effects In Everyday Practice
Substitution is rarely dramatic in real time. It shows up as a slightly smaller grocery basket, a postponed furniture purchase, or one fewer restaurant meal per month. Over a full quarter those small decisions add up. Card data already capture the early stages of the process. Fuel spending accelerates while clothing, home improvement, and department-store totals ease. The total spending number can still rise because the fuel increase is large enough to offset the declines elsewhere. The household, however, experiences the change as a loss of flexibility.
In my experience watching these cycles, the longer the elevated fuel prices persist, the more the substitution becomes entrenched. Temporary spikes produce temporary adjustments. Multi-month elevations produce more permanent shifts in shopping patterns. Convenience-store traffic may hold steady while the mix of items purchased tilts toward lower-cost options. Online carts shrink at the margin. The cumulative impact appears in the control-group sales that feed into growth estimates.
Looking Ahead: What To Watch Next
Several indicators will clarify whether the current pattern is a brief pause or the start of a longer moderation. Future retail sales releases will show whether control-group growth stabilizes or continues to slow. Card data will reveal whether fuel spending keeps accelerating or begins to normalize if pump prices ease. Credit metrics will indicate whether the pressure on budgets begins to affect repayment behavior. Sentiment surveys will test whether the gap between hard data and soft data narrows or widens.
None of these markers points to an immediate collapse. The consumer has proven more durable than many expected through earlier shocks. Durability, however, is not the same as unlimited capacity. When a large and recurring expense expands, something else must give. The latest figures suggest that the giving is already underway in several discretionary categories. How far that process runs will shape the path of spending into the final months of the year.
The morning’s numbers delivered a clear message once you look past the headline. Retail sales can climb to record territory while the typical household still feels the squeeze. Rising costs at the pump are not an abstract inflation statistic. They are a weekly line item that forces real trade-offs. Those trade-offs show up in softer control-group sales, contracting discretionary categories, and sentiment that remains stuck near historic lows. The economy continues to move forward. The comfort level of the people powering that movement has not kept pace.
Understanding the difference between headline strength and underlying strain is essential for anyone trying to read the current moment accurately. The data do not lie, but they do require careful interpretation. Fuel prices have altered the composition of spending in ways that matter for both growth calculations and everyday experience. Until those prices retreat meaningfully, the gap between record sales and record-low sentiment is likely to persist. That tension, more than any single monthly print, defines the consumer landscape right now.
Households are adapting, banks still see resilience, and absolute spending levels remain elevated. Adaptation, however, has limits. The longer the pressure at the pump continues, the more visible those limits become in the categories that households can still control. Watching that process unfold will remain one of the more revealing exercises in the months ahead. The numbers will keep arriving. The real story will continue to live in the details beneath them.