

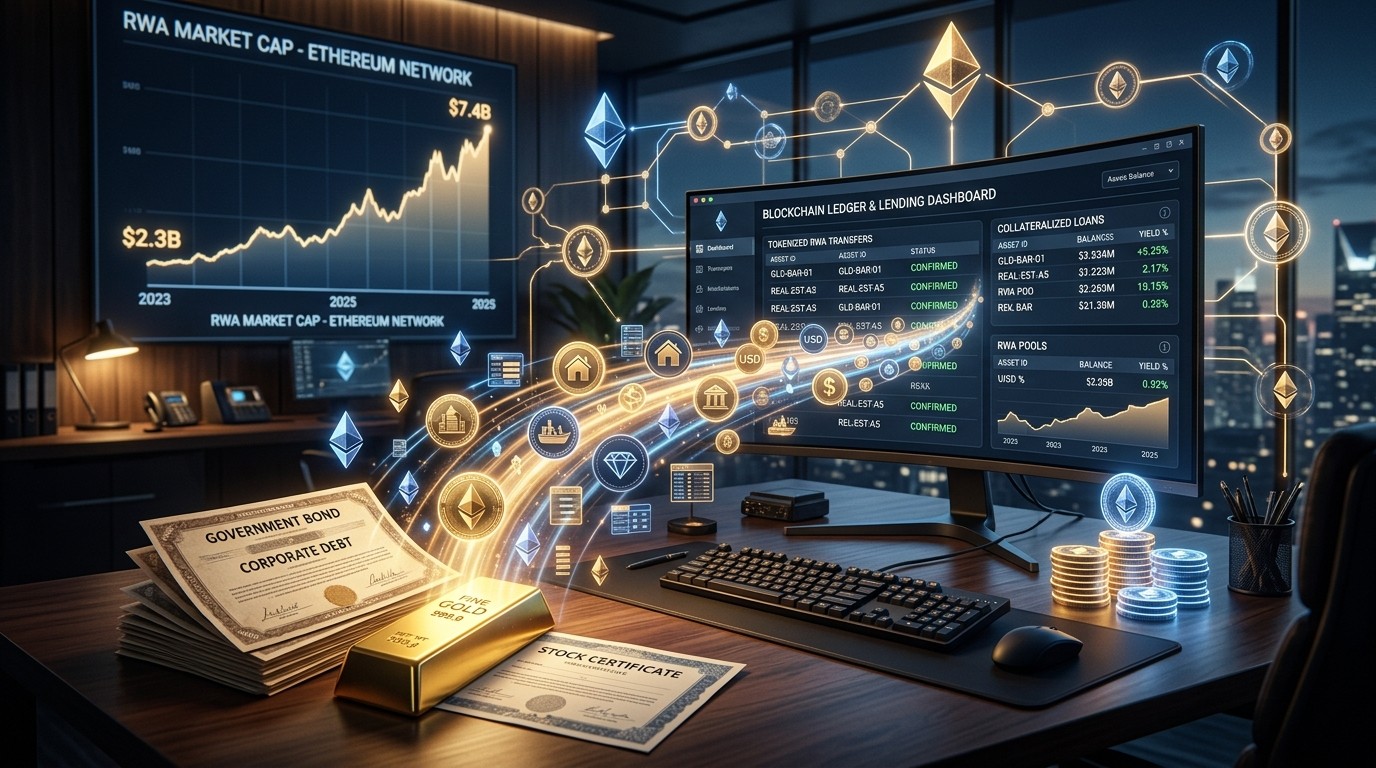

Here is the number that stopped me mid-scroll. Tokenized real-world asset deposits jumped from $2.3 billion to $7.4 billion between the second quarter of 2025 and the second quarter of 2026. Same window, total DeFi deposits slipped by about 15 percent. That is not a cute coincidence. It is a market telling you, quite loudly, that capital is leaving the purely crypto-native loop and parking itself in assets that still look like the old financial system, only now they live onchain.
What The $7.4 Billion Figure Actually Means
I have watched plenty of crypto cycles dress up a bounce as a revolution. This one feels different, and not because the marketing is prettier. The growth sits in deposits that can move across venues. Tokenized funds, stocks, and commodities kept finding real use in lending, spot markets, and perpetual futures while crypto-native activity cooled. If you only look at headline DeFi TVL, you miss the rotation happening underneath.
The working definition matters. The data focuses on distributed assets that can leave the issuing platform. Closed gardens and some permissioned networks sit outside the main count. That choice makes the $7.4 billion figure more useful, not less. You are looking at collateral that can actually travel.
Finance is not being disrupted but rewired.
That line has been floating around hybrid finance conversations for a while. I buy the spirit of it. Tokenized paper is not replacing banks overnight. It is plugging old cash flows into new rails: lending books, automated market makers, high-throughput chains, and derivatives venues that never sleep.
RWA Collateral Grew While Broader DeFi Contracted
Between those two second quarters, RWA deposits across lending protocols and decentralized exchanges rose from $2.3 billion to $7.4 billion. Total DeFi deposits fell around 15 percent. Part of that decline is painfully ordinary. People withdrew. Prices of crypto-native collateral slipped. Opportunity cost changed. None of that explains why tokenized collateral kept climbing.
Treasury and multi-strategy products supplied a large share of the new collateral. Names that keep showing up in these books include JTRSY, BUIDL, and sUSDS, followed by private-credit style products such as JAAA, syrupUSDT, syrupUSDC, and PRIME. The delta-neutral sleeve sUSDe added another deposit stream. In plain English, investors posted things that still pay a coupon or a funding yield, then borrowed against them.
That last point is the quiet killer feature. If the asset keeps earning while it sits as collateral, the opportunity cost of locking it up drops. I have found that this is usually the moment a product stops being a demo and starts being a balance-sheet tool.
- Yield-bearing RWA collateral clustered on Aave, Morpho, and Kamino.
- Ethereum held nearly 70 percent of measured RWA deposits.
- Plasma picked up share as lending expanded beyond Ethereum.
- Solana’s slice was supported by Kamino activity.
Concentration is not automatically a bug. Ethereum still has the deepest borrower demand and the most familiar lending liquidity. That said, the second-place chains are no longer a footnote. Once a treasury token can move, it will hunt the cheapest borrow and the tightest liquidation engine. Liquidity follows that hunt.
Why Yield-Bearing Collateral Changes Borrower Math
Classic DeFi collateral often asked you to freeze an asset that pays nothing except price appreciation. Tokenized Treasuries and private-credit wrappers flip that. You can keep a slice of the yield and still open a loan. The spread between what the collateral earns and what the borrow costs becomes the real product.
Selected RWA strategies in the study printed yields somewhere between about 3.2 percent and 5.5 percent. Tokenized Treasury funds sat near the lower end. Private credit, lending markets, vaults, and delta-neutral funding strategies sat higher, with very different risk shapes. That range is not spectacular if you grew up on 20 percent stablecoin farms. It is spectacular if you think like a treasurer.
Perhaps the most interesting aspect is how boring the best use case looks. A fund that already owns short-duration government paper tokenizes the claim, posts it, borrows stablecoins, and recycles the cash. No fireworks. Just a tighter loop between cash management and onchain credit.
Spot Markets Split In Two Directions
Spot activity told the same story with louder volume numbers. Aggregate DEX trading, still dominated by crypto-native tokens, fell roughly 70 percent year over year. RWA spot volume rose about 220 percent over the same Q2-to-Q2 window. Yes, it started from a much smaller base. No, that does not make the divergence fake.
Tokenized gold and funds did a lot of the heavy lifting. XAUT and PAXG kept showing up as major contributors. sUSDe volume jumped after liquidity migrated from an older automated market maker design to a newer one. Tokenized equities were still a smaller slice during the core measurement window, then started to matter more as the summer turned into September.
Later onchain readings put tokenized stocks around a $3.19 billion market capitalization in early September, with 6.3 percent of that deposited in DeFi and $9.70 billion traded on DEXs over the prior 30 days. On one high-throughput network, tokenized stock DEX volume later hit $730.9 million over 30 days, with daily prints touching $100 million. That is retail-shaped flow, not just a few desks parking inventory.
| Segment | Q2 2025 to Q2 2026 move | What it signals |
| RWA deposits | $2.3B to $7.4B | Collateral demand, not just issuance |
| Total DeFi deposits | Down about 15% | Crypto-native risk appetite cooled |
| RWA spot volume | Up about 220% | Trading use is catching issuance |
| Aggregate DEX volume | Down about 70% | Native token turnover shrank |
Perpetual Futures Became The Fastest Lane
If deposits are the slow grind, perpetuals are the sprint. Volume on an RWA-focused venue operating through a high-performance derivatives stack rose roughly twenty times from launch, while crypto-native perpetual activity weakened after October 2025. Commodities, equity indexes, and technology names did most of the work.
Oil and precious metals generated heavy turnover. S&P 500 and Nasdaq-100 style contracts gave traders index exposure without touching a brokerage ticket in the usual sense. Semiconductor names were another busy pocket. Open interest did not just tag along. Equity indexes and chip stocks held a larger share of outstanding positions than commodities, even when commodities printed huge volume. That is a positioning story, not only a day-trading story.
Fresh September readings kept the trend alive. Perpetual DEX open interest reached $19 billion, with RWA contracts around 24 percent of the total, up from about 6 percent at the start of 2026. The number of RWA markets across perpetual DEXs had moved past 1,000. Two days later, Q3 RWA perpetual DEX volume sat at $365 billion, up 32 percent quarter over quarter. Public equities contributed about $175 billion, close to 48 percent of that pile.
Does that mean tokenized stocks have replaced cash equities? Of course not. It means traders found a 24-hour venue for exposures they already understood. In my experience, products travel fastest when the payoff is familiar and the wrapper is new.
Venue Revenue Did Not Rise In Lockstep
Here is the awkward bit. Application revenue across lending and trading venues declined between those two second quarters even as RWA activity increased. Crypto-native borrowing and trading still produced most of the fees. RWA growth was real. It was not yet large enough to replace the missing native flow.
The derivatives venue that also runs its own settlement stack generated the most application revenue in the comparison set. That dual role matters. When the exchange and the chain sit closer together, more of the economic stack stays in-house. Lending protocols told a different story. One large lending platform in the set had little or no protocol-level take rate, which limited how much activity converted into direct revenue. Trading venues carried the highest revenue multiples in the valuation comparison.
Independent follow-up data later said that same RWA derivatives venue processed $202.36 billion during Q2, up 79.2 percent quarter over quarter, while equity perpetual volume rose 377 percent to $58.9 billion. Fees and volume are cousins, not twins. You can have a roaring book and still watch take-rate mix shift under your feet.
Who Is Actually Holding These Tokens
Wallet data is a blunt instrument, and the report is honest about that. One wallet is not one investor. Still, the gap between product types is too wide to ignore. Institutional wrappers such as a large tokenized Treasury fund showed average wallet balances in the tens of millions of dollars. Tokenized stock products showed much smaller balances, more consistent with retail tickets.
Tokenized equities also recorded the fastest holder growth among the categories studied. Smaller ticket sizes make that easier. You do not need a family office to buy a slice of a household name after hours. Institutional products attracted fewer wallets and much larger balances. Both patterns can be healthy. They just should not be mashed into one narrative about “the user.”
During the core measurement window, tokenized-stock value sat around $2.2 billion. By late September, later market tallies put tokenized stock capitalization near $3.5 billion. One large alternative chain led with about $1 billion, followed by Ethereum and Solana. Those three networks represented around 70 percent of the measured tokenized-equity market. Issuance is spreading. Liquidity is still picky.
Ethereum Still Dominates, But The Map Is Stretching
Almost 70 percent of measured RWA deposits lived on Ethereum. That is not nostalgia. It is liquidity gravity. Borrowers already sit there. Oracles are battle-tested. Liquidation paths are familiar to risk desks. If you are posting a tokenized Treasury note as collateral, you care more about unwind quality than about a slightly cheaper gas fee.
Plasma ranked second in the deposit ranking, helped by lending expansion beyond the original chain. Solana’s share leaned on Kamino. I would not call this a multi-chain free-for-all yet. I would call it a barbell. Ethereum remains the credit hub. Faster chains pick up flow when the product is trading-heavy or when a local lending market offers a better rate.
Tokenized stocks complicate that map. Retail-shaped equity tokens showed more willingness to live where fees are low and listings are aggressive. Credit collateral stayed conservative. Different assets, different homes. That is how markets usually grow up.
The Hybrid Finance Thesis, Without The Slogan
Strip away the branding and the thesis is simple. Tokenized assets become interesting when they plug into three sockets at once: a credit market, a spot venue, and a derivatives book. Issuance alone is a press release. Usage across those three sockets is a system.
- Issue a claim on a real cash flow or a familiar market exposure.
- Let that claim move off the original platform.
- Accept it as collateral without killing the underlying yield.
- List it for spot transfer and, where it makes sense, for perpetual trading.
- Watch whether open interest and deposits rise together.
Steps one and two happened years ago in pockets. Steps three and four are what changed in this twelve-month window. Step five is the tell. Deposits and perps both expanded. That is harder to fake than a single TVL print.
Risks That The Victory Lap Usually Skips
Let me be blunt. Tokenized does not mean riskless. You still have issuer risk, transfer-agent risk, oracle risk, smart-contract risk, and the old-fashioned chance that the underlying asset does something ugly. A Treasury wrapper can look cash-like until settlement rules freeze a wallet. A private-credit token can look yield-like until the loan book stops paying.
Perpetual markets add another layer. Index and single-name equity perps can drift from the cash market they reference. Funding rates can punish the crowded side. Liquidity that looks deep at noon can thin out at 3 a.m. if the market makers who warehouse inventory decide the spread is no longer worth it.
There is also a measurement problem. Wallet averages can hide funds, market makers, and clustered custody. A $3.5 billion tokenized-stock figure can include inventory that is not freely floating. I like the direction of the data. I do not treat every decimal as scripture.
What A Treasurer Should Do With This
If you run cash, the useful question is not “is RWA the future.” The useful question is whether a tokenized claim improves your collateral optionality without wrecking your operational controls. Can you move it? Can you price it? Can you unwind it on a bad Tuesday? Does the yield survive the haircut?
For many desks, the first sane use is still short-duration government paper and high-quality money-market style tokens. Private credit belongs in a different bucket. Delta-neutral stable products belong in another. Mixing those risk types because they share an acronym is how people get surprised.
A practical filter I keep coming back to:
  Can it leave the issuer’s garden?
  Does it keep earning as collateral?
  Is there a real borrower on the other side?
  Is there a second venue if the first one blinks?
If you cannot answer those four, you do not have a market. You have a listing.
What Traders Are Really Buying
Retail-shaped flow into tokenized stocks is not a mystery. People want after-hours access, smaller tickets, and a wallet they already use. Whether that demand survives a messy corporate action or a transfer restriction is the test that has not fully arrived yet. Fast holder growth is encouraging. It is not the same thing as durable secondary liquidity in a stress window.
On the derivatives side, traders are buying continuity. Indexes, oil, metals, and chip names already live in their heads. A perpetual wrapper lets them express a view without waiting for a cash session. Volume exploding twentyfold from a low base is what you would expect if the product is convenient. Convenience can fade if basis risk gets sloppy.
I keep coming back to the 24 percent open-interest share for RWA contracts. That is no longer a curiosity sleeve. That is a meaningful slice of the perpetual pie. When a sleeve gets that large, it starts to matter for venue revenue, for liquidations, and for how risk engines treat collateral correlations.
Why DeFi Could Shrink And Still Matter
A 15 percent drop in total DeFi deposits sounds like a funeral if you only sell the old story. The old story said every idle token would live in a pool forever. The new story is pickier. Capital wants collateral that institutions recognize, yields that survive a spreadsheet, and venues that can clear both crypto-native and tokenized flow.
That is why the revenue picture can look soft while the usage picture looks strong. Fees followed the old mix. Activity is rotating into a new mix. There is usually a lag. Sometimes the lag lasts longer than the people writing quarterly notes would like.
Is the rotation finished? Not even close. Tokenized stocks were still climbing after the original cutoff. Perpetual share was still climbing in September. Deposit concentration on Ethereum was still high. Those three facts can live together. Markets do not rewire in a straight line.
A Cleaner Way To Read The Next Twelve Months
Watch four gauges, not one trophy number. First, RWA deposits as a share of total DeFi deposits, not only the raw $7.4 billion. Second, the share of those deposits that remain yield-bearing after haircuts. Third, RWA perpetual open interest versus crypto-native open interest. Fourth, whether venue revenue starts to follow RWA volume instead of only native volume.
If deposits keep rising while revenue stays stuck, you have a usage boom with a monetization problem. If revenue follows, the hybrid stack is becoming a business, not a demo. If tokenized-stock market cap keeps marching toward and through that $3.5 billion mark while DeFi deposits of those stocks stay in the mid-single digits as a percentage, you have trading interest that has not fully turned into credit demand. Each mix implies a different winner.
Tokenised assets are moving beyond issuance. The interesting part is no longer whether a bond can live on a chain. The interesting part is whether that bond can borrow, trade, and hedge without leaving the rails.
I will take that framing over another speech about disruption. Rewiring is slower. It is also harder to dismiss when the deposit line triples during a year when the rest of DeFi took a step back.
The Bottom Line I Keep Repeating To Myself
The headline is simple enough for a group chat. RWA deposits more than tripled to $7.4 billion. DeFi deposits fell about 15 percent. Spot RWA volume jumped while native DEX volume cratered. Perpetual RWA activity exploded from a small base and then kept going into the third quarter. Tokenized stocks grew after the original snapshot. Ethereum still hosted most of the deposits. Revenue did not automatically follow.
The interpretation is less simple, which is why this market is worth sitting with. We are watching credit, cash, gold, and listed-equity exposure learn how to live in the same wallet as a perpetual ticket. Some of that will fail. Some of it will look obvious in hindsight. Right now it looks like the part of crypto that finally found a customer who already understood the asset, and only needed a better pipe.
That customer is not waiting for a manifesto. They are waiting for collateral that keeps paying, markets that stay open, and an exit that works when the chart stops being friendly. The last year gave them more of that than the year before. The next year will show whether $7.4 billion was a landing pad or just the first stop on a much larger transfer of balance sheets onto rails that never close.



