
Have you ever watched a safety net start to tear right when the world needed it most? That is exactly what is unfolding with Saudi Arabia’s role in the global oil market. For years the kingdom acted as the quiet buffer. When shipping lanes grew risky, it pushed crude westward through its massive East-West pipeline and kept supplies moving. Now that buffer itself is under pressure, and the consequences stretch far beyond the Gulf.
Why the Bypass Pipeline Suddenly Matters More Than Ever
Most people picture oil as something that simply flows from well to tanker. Reality is far more complicated. A pipeline is not just a metal tube buried in sand. It is a living network of pumping stations, power supplies, control systems, storage tanks, and loading terminals. Break any one of those links and the whole chain slows or stops.
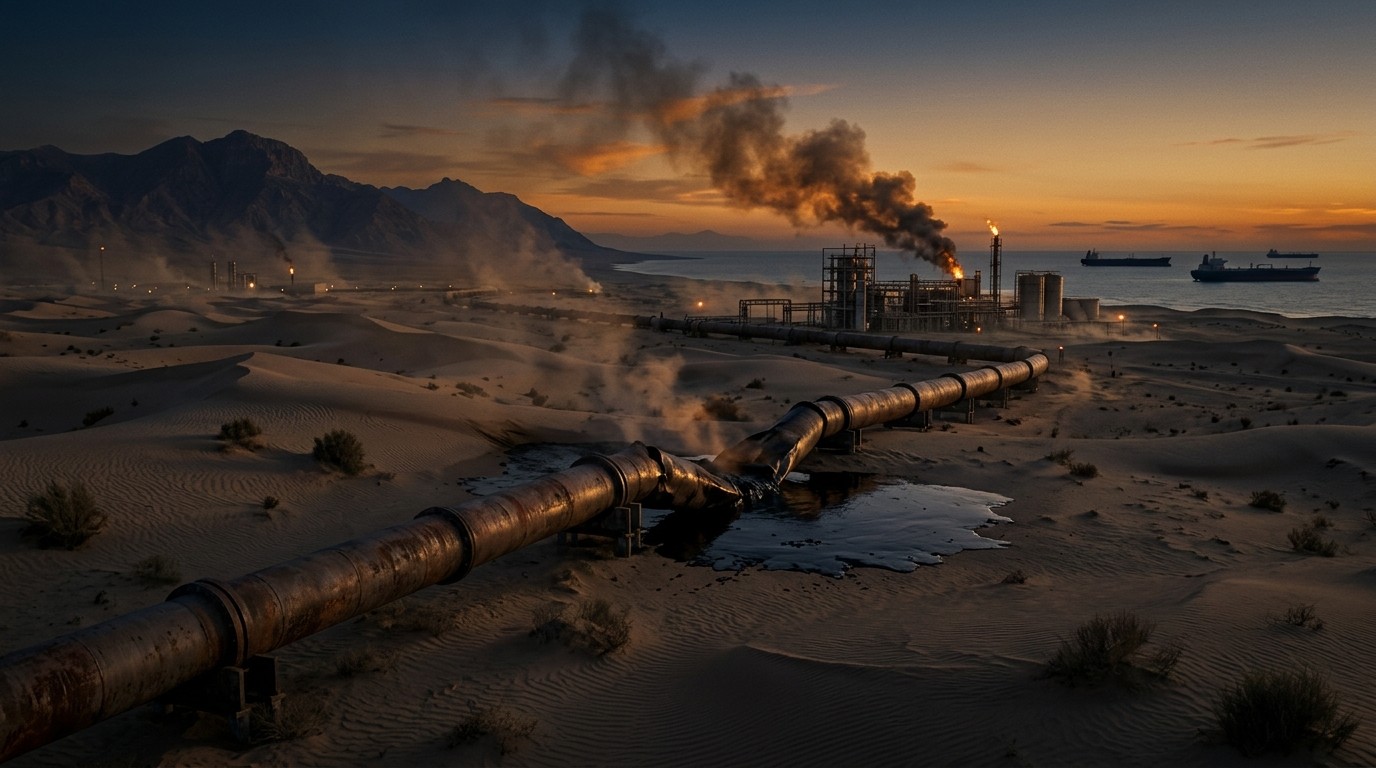
Recent months have shown how fragile that network has become. Strikes hit key pumping stations along the East-West corridor. One attack in September largely knocked the line out of service. Another in early October struck a station at Khurais for the first time. Fires and aviation disruptions added further strain. The pipeline has been partially restored, yet permanent equipment losses remain unresolved. Yanbu, the Red Sea terminal, can be rendered useless without a single bomb landing on the docks. If the crude stops arriving, the tankers simply sit idle.
I have been following energy logistics for a long time, and one detail keeps jumping out at me. Analysts sometimes treat each damaged station as a neat percentage of lost capacity. That approach misses the point. What truly counts is throughput. Benchmark numbers put normal movement through the corridor near 5.8 million barrels a day. A full week of interruption risks more than 40 million barrels. Stretch that to a month and the figure climbs past 170 million. These are stress calculations, not claims that the line is completely closed. Still, they show how quickly the volume at risk can pile up.
The Rebuild Timeline Nobody Wants to Talk About
Earlier estimates suggested the wider Gulf energy complex could recover in roughly five years. Fresh analysis now stretches that horizon to seven or even ten years for the most severely damaged and interconnected systems. Partial output will return sooner. Full, reliable operation will not. Think recovery windows running from late 2033 into 2036.
Why so long? The equipment is the bottleneck. Large compressors, turbines, high-voltage transformers, specialized pressure vessels, and integrated control systems are not sitting on warehouse shelves. They are custom-built. The critical path for replacing a major package runs about 84 months: a year to assess damage and secure design funding, three years to procure and manufacture, two years to deliver and install, and another year to commission and stabilize. Insecure sites, financing gaps, factory queues, and the possibility of further attacks could easily add three more years.
Money can reserve a manufacturing slot. It cannot shrink every stage of engineering and fabrication. In my view that is the part many policymakers still underestimate. Announcing a repair is easy. Delivering certified, operational capacity under real-world constraints is a different story.
The Staggering Cost of Putting the System Back Together
Reconstruction of the broader Gulf energy system, Saudi Arabia included, has been modeled across three scenarios. These are funding envelopes built on clear assumptions, not audited damage assessments and not a Saudi-only bill.
| Scenario | Base Reconstruction | Execution Uplift | Finance and Startup | Total Envelope |
| Controlled | $400 billion | $100 billion | $50 billion | $550 billion |
| Central | $800 billion | $280 billion | $120 billion | $1.20 trillion |
| Severe | $1,400 billion | $630 billion | $250 billion | $2.28 trillion |
In the central case, roughly $180 billion needs to be committed in the first two years alone. Years three through five climb toward $540 billion. Averaged over seven years the figure exceeds $170 billion annually. Every Gulf state will compete for the same manufacturers, engineering firms, fabrication yards, and specialist crews. A transformer slot taken by one country is a slot another country does not get.
Delay carries its own price tag. A three-year postponement on the central program could add $76 billion to $125 billion in cost escalation and another $42 billion to $90 billion in financing charges. Meanwhile the fuel still has to come from somewhere. Each year that one million barrels a day of supply stays offline means 365 million barrels that must be replaced. At an illustrative $150 a barrel that works out to about $55 billion. Leaving a full three-million-barrel daily gap unrepaired for three additional years implies nearly half a trillion dollars in replacement purchases.
How the Diesel and Jet Fuel Gap Keeps Widening
The baseline global shortfall for diesel and jet fuel already sits at a minimum of three million barrels a day. Saudi disruptions threaten to push that number higher. If one million barrels a day of crude cannot reach working refineries, the loss of diesel and jet fuel runs roughly 300,000 to 450,000 barrels daily. An extra net loss of half a million barrels a day would lift the baseline to 3.5 million, an increase of about one-sixth. That adds 15 million barrels of shortfall every single month.
Careful accounting is essential here. Lost crude, the refined products it would have produced, and the missed export cargo can all describe the same barrels. Double counting must be avoided. The direction of travel remains clear. Saudi Arabia used to be the main source of relief for the region. When its bypass becomes unreliable, the global deficit grows.
Perhaps the most sobering test involves American capacity. Over a recent four-week stretch, U.S. refineries produced about 5.17 million barrels a day of distillate. They exported 1.56 million and used 3.77 million at home. Replacing a three-million-barrel daily gap from the United States alone would require 58 percent more distillate output than American plants currently deliver. Year-over-year production growth sits near 150,000 barrels a day. The global gap is nearly twenty times that figure. Promising more exports does not create more fuel. It simply shifts the shortage from one buyer to another and drains domestic inventories.
Real-World Ripples: Food, Freight, and Flights
Fuel shortages do not stay confined to balance sheets. They reach the dinner table and the airport gate. Cereal prices already sit more than 17 percent higher than a year earlier. Farmers need diesel before the harvest pays. Truckers need it before invoices clear. Refrigeration needs it before food reaches store shelves. Airlines require certified jet fuel at the specific airports they serve. Diesel cannot simply stand in for jet fuel.
The weakest buyers, countries short on foreign exchange and credit, face the harshest outcome. They will not merely pay more. In many cases they will be priced out entirely. That is the quiet human cost that rarely makes the headline charts.
Recovery will be proven by fuel actually delivered, not by repairs announced or by a lower headline price.
I keep returning to that simple standard. Announcements and price snapshots can mislead. Physical barrels in tanks and engines tell the true story.
Saudi Arabia’s Own Economy Already Feels the Strain
The kingdom’s oil activity fell by roughly a quarter in the second quarter. Overall GDP contracted nearly 5 percent. Those numbers matter because they show the shock absorber is itself absorbing damage. What used to be the world’s insurance policy has become another source of risk.
This is not a temporary price spike that vanishes the day a ceasefire is signed. Reopening a shipping lane does not magically rebuild a refinery or replace a custom turbine. The reconstruction of Gulf energy infrastructure will be measured in years and in trillions of dollars. The world is likely to remain short of diesel for much of that period.
What Policymakers and Markets Should Actually Watch
Every promise of quick relief deserves the same test. Does it put physical fuel into the system, or does it merely rearrange existing barrels? Claims that prices are about to fall, suggestions that alternative suppliers can instantly fill the gap, and optimistic repair timelines all need to be measured against delivery data rather than press releases.
In my experience the markets eventually respect physical reality. Inventories, floating storage, and refining utilization rates will reveal more than any single announcement. The East-West pipeline’s reliability, the pace of equipment orders, and the actual volume of diesel and jet fuel reaching end users will form the real scoreboard.
- Track weekly distillate production and export figures rather than just crude prices
- Watch for confirmed delivery of major replacement equipment, not just contracts
- Monitor the gap between announced repair completion and actual sustained throughput
- Pay attention to countries struggling to secure credit for fuel imports
- Note any further interruptions at key Gulf facilities
The coming years will test assumptions that many still treat as solid. Saudi Arabia’s ability to act as the swing supplier has been compromised. The cost of restoring full capability is enormous. The time required is longer than most public discussion admits. And the diesel shortfall sits at the center of the problem, affecting agriculture, transport, and aviation in ways that compound quickly.
None of this means the system collapses overnight. Partial flows continue. Some capacity returns. Alternative routes and suppliers stretch to cover what they can. Yet the margin of safety has narrowed, and the rebuild will be neither cheap nor quick. Anyone making decisions about fuel security, inflation risks, or investment timelines needs to plan for a multi-year adjustment rather than a rapid bounce-back.
Looking ahead, the smartest approach is measured realism. Acknowledge the damage. Respect the engineering and manufacturing constraints. Follow the physical barrels. And remember that the shock absorber the world relied on for so long is itself now under repair. That shift changes the entire risk landscape for energy markets.
The story is still unfolding. Pumping stations can be repaired, but the specialized components take years to produce. Funding envelopes can be announced, yet competing demand across the region will stretch every fabrication yard. Diesel shortages can be managed for a while, yet the cumulative effect on food systems and logistics grows harder to ignore. In the end the proof will sit in the tanks and the engines, not in the headlines. That is the frame worth keeping in mind as the next chapters of this energy challenge write themselves.
I have watched energy markets long enough to know that physical constraints eventually overrule optimistic narratives. The current situation in the Gulf is a clear example. Saudi Arabia’s pipeline network, once a reliable bypass, now carries elevated risk. The rebuild will take the better part of a decade for full reliability. Costs run into the hundreds of billions or even trillions depending on the path taken. And the diesel gap sits at the heart of the problem, with limited ability for any single country to close it quickly.
For businesses, governments, and ordinary consumers the practical takeaway is straightforward. Build in more buffer. Diversify supply sources where possible. Watch the hard data on production and deliveries. And prepare for a longer period of tighter fuel markets than many currently expect. The old assumption that Saudi Arabia could always step in and smooth the gaps no longer holds with the same confidence. That change alone is enough to reshape planning across multiple sectors.
The coming months will bring more data points. Some repairs will succeed. New equipment orders will be placed. Alternative logistics routes will be tested. Yet the fundamental timeline and cost structure outlined here are unlikely to shift dramatically. Custom industrial equipment does not appear overnight. Competing demand for the same scarce manufacturing capacity will persist. And every additional interruption adds both time and expense.
In the final analysis the energy damage from recent events is structural rather than cyclical. It will not reverse the moment tensions ease. The world will need to live with a thinner margin of safety in refined products for years. How governments, companies, and markets adapt to that reality will determine how costly the adjustment becomes. Paying attention now, while the numbers are still becoming clear, is the least painful option available.