

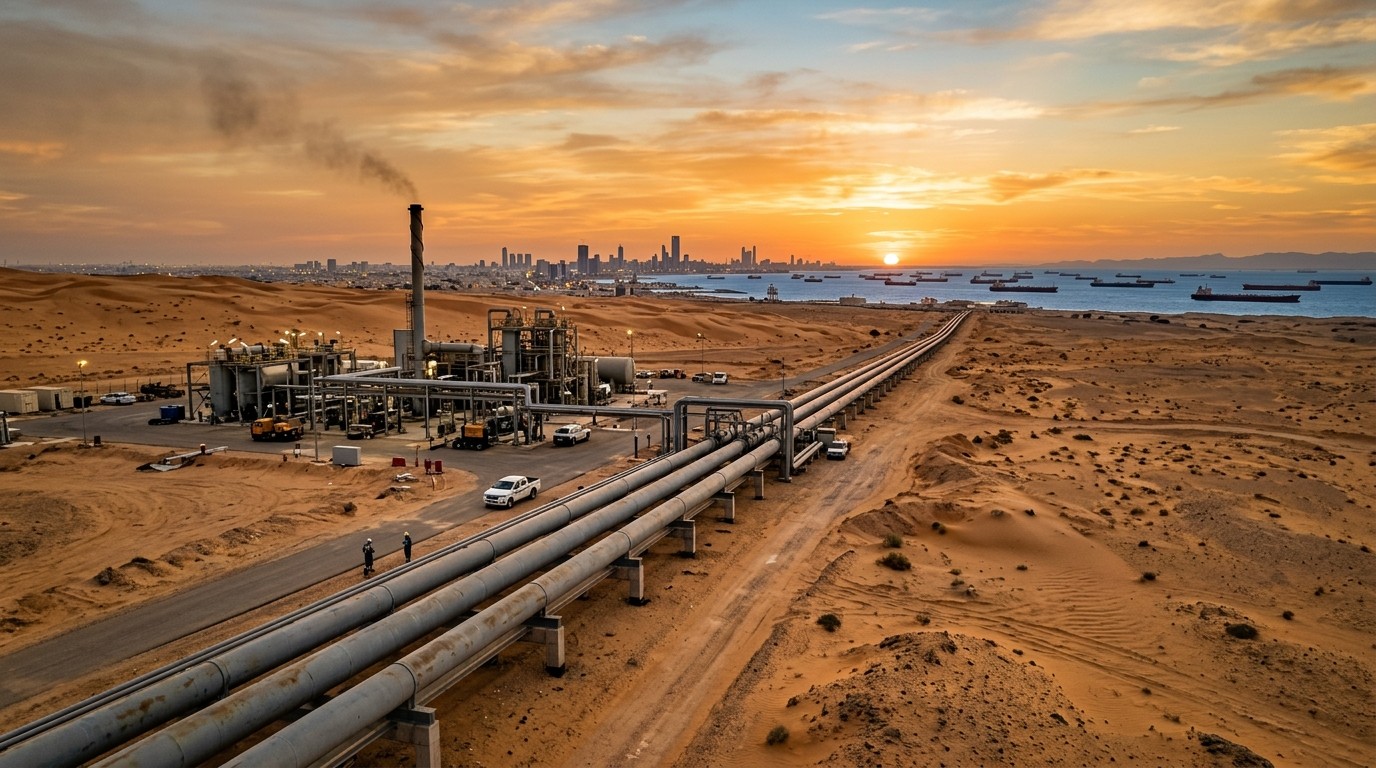

That is the whole story in one awkward sentence, and it is also why the story is not over. A conduit that can shift crude from the kingdom’s main eastern fields toward the Red Sea is not a side pipe. It is a spare lung. When someone punches it, even briefly, every desk that prices diesel, jet, and dated cargoes has to ask a nastier question. What if the next punch lands on a station that takes longer to patch?
What Actually Happened On The East-West Line
Energy-sector sources described a fresh attack on the East-West pipeline, this time at a pumping station east of Riyadh in the Khurais area. The detail that stood out was simple. That station had not been the target before. Damage was called large. The line stopped again. Follow-up reporting then narrowed the scare. Oil continued to flow through the link. The halt was brief, over the weekend, and operations were described as back to normal.
Normal is a slippery word in this business. A line can be “flowing” while still running below its design rate, with a crew working nights on a damaged manifold and a trader quietly widening a bid-offer spread. I have found that the first official comfort is often true and still incomplete. Molecules moving is not the same thing as spare capacity you can lean on without thinking.
The route itself is roughly 745 miles, tying the eastern producing heartland to the Yanbu terminal on the Red Sea. That geography is the point. It gives the kingdom a way to put crude on the water without sending every barrel through the Gulf and out the Strait of Hormuz. In calm years people treat that option like insurance they hope never to claim. In a year when the Gulf already feels tight, the option is the product.
Why A Station East Of Riyadh Matters
Khurais is not a random pin on a map. It sits in the system that gathers and pushes crude westward. A pumping station is the unglamorous heart of a long line. Kill the pumps, or damage the power and controls around them, and pressure drops even if the steel pipe itself is intact for hundreds of miles. Repair crews can be excellent and still need days, not hours, if turbines, transformers, or control rooms take the hit.
Perhaps the most interesting aspect is the choice of target. Earlier strikes on this corridor trained the market to watch a short list of nodes. A station that “was not targeted before” widens that list. Defense planners hate widened lists. So do insurers. So should anyone who thinks a single successful intercept means the corridor is safe for the quarter.
A pipeline is only as calm as its least defended pump. Flow today does not retire the risk of a longer stop tomorrow.
Market voices were quick to push back on the idea of a lasting outage. One widely shared note from an energy correspondent put it plainly: flows through the east-west link had not been interrupted in the way some early reports suggested. That correction matters. False outage stories move flat price and then humiliate the people who chased them. True short outages that get repaired still change the risk premium, just more quietly.
The Pattern Behind “Again”
This was not framed as a one-off. The corridor has been targeted several times amid renewed fighting between Saudi forces and the Houthi movement, after weeks of sharper clashes. Fighting next door in Yemen has intensified, not cooled. When a conflict widens on the ground, infrastructure within reach of longer-range strikes stops being a theoretical vulnerability.
I do not pretend to score battlefield claims from a screen. Both sides are talking their book. What a market can score is repetition. Repeated attempts on the same strategic pipe, even when most fail or get patched fast, are a process. Processes get priced. One dramatic weekend does not.
Two Stories From The Same Weekend
Over the weekend the Saudi-backed government in Yemen announced what it called a new phase in the fight to restore state authority. Its information minister wrote that the operation aims to extend authority over every inch of Yemeni land. He tied recovery of land, islands, and positions around the Bab al-Mandeb Strait to the security of one of the world’s vital sea lanes, arguing that militia control had turned the passage into a tool for pressure and threats.
That is the optimistic reading, and it is not empty. If shipping near the southern Red Sea becomes less hostage to threats, insurance premia and rerouting costs can ease. Those costs have already taught shipowners a grim lesson over the past few years: a strait does not have to close to get expensive. It only has to feel unreliable.
The other reading arrived the same day. A political bureau figure from Ansar Allah, cited in regional coverage, dismissed victory headlines as media noise. The claim was that opposing forces were still falling back, from the Gulf of Aden coast near Ras al-Aara toward areas around Al-Muwasit and positions linked to rivals in Taiz. Alleged gains, in that telling, live on social feeds and nowhere else.
You can hold both statements in your head without picking a flag. One side is selling momentum. The other is selling resilience. Neither statement tells you whether a pump station east of Riyadh is easier or harder to hit next month. Geography does. The pipeline sits in Saudi territory. The fight being described is in Yemen. Drones and missiles have already shown they do not respect that distinction as neatly as a textbook border does.
What Traders Should Separate
- A confirmed brief halt is not a multi-week outage. Treat early “stopped for good” claims with suspicion.
- A repaired line is not a forgotten line. Repeat targeting raises the odds of a longer repair window later.
- Red Sea politics and Gulf politics are linked in price, even when the weapons and the maps differ.
- Export continuity at Yanbu is the number that matters more than the rhetoric from either camp.
Short version, and I will say it the way a desk would. Do not buy the scare. Do not sell the scar.
How The Physical System Absorbs A Hit
People outside the industry picture a pipeline as one tube. Operators picture a network. Storage tanks upstream can take a few hours of production if pumps trip. Downstream tanks at a terminal can keep loadings going while the line is down, until those tanks draw down. Spare pumps, bypasses, and the ability to reroute some volume inside the eastern system all buy time. That is why a weekend stop can vanish from the export schedule and still have been real.
The limit shows up when several things fail together. A damaged station, a cautious restart, a ship that missed its window, and a buyer who will not wait. None of those, alone, empties the market. Together they tighten prompt barrels and leave the back of the curve looking oddly calm. That shape, tight now and hopeful later, is exactly the mood company leadership described in London the same day.
The Two-Year Inventory Warning
The chief executive of the kingdom’s national oil company, speaking in person at an energy forum in London, did not sound like a man describing a market on the mend. Amin Nasser said the squeeze on crude and refined fuels is set to worsen. Refilling stockpiles that were tapped as an emergency measure might take two years. Until Hormuz fully reopens and confidence returns, pressure at both ends of the barrel intensifies. Even after that, replenishing inventories while meeting demand could take up to two years.
He added a line that should be taped above a few trading screens. Brent, in his telling, would have reached as high as $200 a barrel if the East-West pipeline did not exist. The system, he said, is already straining. It was his first in-person speech since the launch of the Iran war. That context is doing a lot of work. A CEO does not usually spend a London stage on counterfactuals unless the bypass route has been earning its keep in real cargoes, not in theory.
Until the main Gulf outlet fully reopens and confidence returns, pressure at both ends of the barrel will intensify. Replenishing inventories while meeting demand could take up to two years.
Amin Nasser, national oil company chief executive, Energy Intelligence forum
Read that beside the weekend repair and the picture gets sharper. The bypass worked. It also just got hit. The man running the world’s largest oil company is telling you the bypass is one reason prices are not already in triple digits past $150, let alone $200. Gratitude and fragility are the same fact, viewed from two chairs.
Both Ends Of The Barrel
“Both ends” is not a slogan. Crude is one end. Gasoline, diesel, jet, and fuel oil are the other. A pipeline strike threatens the first. A long period of diverted voyages, cautious refiners, and drawn stocks threatens the second even if the pipe is welding back together. Refiners cannot invent weeks of lost runs. They can only run harder later, and later has its own maintenance calendar.
In my experience, product markets punish complacency faster than crude does. A driver notices diesel. A airline notices jet. A crude trader can hide inside a curve for a while. If Nasser is right that restocking takes up to two years, the product squeeze is not a headline you fade on a Friday. It is a slow grind that shows up in cracks, freight, and the weird little shortages nobody modeled in January.
| Pressure point | What the weekend showed | What still sits unresolved |
| East-West pumps | Brief stop, flows described as normal again | New station targeted, repair depth unclear |
| Yanbu loadings | No confirmed lasting export gap | Any repeat hit meets thinner spare time |
| Hormuz route | Bypass credited with capping the price spike | Full reopening and confidence still pending |
| Global stocks | Emergency draws already used | Refill horizon cited at up to two years |
| Refined fuels | Squeeze expected to worsen, not fade | Products can stay tight after crude stabilizes |
Tables like that are tidy. The tape is not. Still, tidy helps. If you only remember one row, remember the last. Products can stay tight after the crude scare cools. That is where households and freight companies actually live.
A Bypass Is Not A Magic Shield
The $200 counterfactual is easy to mock and hard to dismiss. Counterfactuals always smuggle an assumption. Here the assumption is that without a Red Sea outlet, Gulf disruption would have forced a much larger price to destroy demand and pull fringe barrels forward. Maybe the number is high. Directionally, the point stands. A functioning westbound line has been a shock absorber.
Shock absorbers wear out if you keep hitting the same pothole. Each repair uses parts, crew hours, and political attention. Each near-miss teaches an attacker something about which nodes answer slowly. I am not arguing the corridor is about to fail. I am arguing that treating a successful weekend restart as proof of immunity is how people get surprised in month three.
Rough mental model, not a forecast:
  Export continuity today     = high
  Spare time if hit again     = lower than last quarter
  Inventory refill clock      = long
  Product tightness           = still building
  Headline noise              = ignore the first hour
Yemen, The Strait, And The Pipe Are One Risk Budget
Bab al-Mandeb sits at the southern gate of the Red Sea. Yanbu sits on the Saudi Red Sea coast. A tanker that loads at Yanbu still has to think about the road south if its buyer is in Asia via the Suez route, or about the long way around Africa if that gate feels hostile. Securing land and islands near the strait, if the announced campaign actually does that, would lower one cost. It would not repair a pump in Khurais.
The inverse is also true. A perfect record on pipeline defense does not calm a shipowner who has watched threats around the southern passage. Risk budgets inside shipping firms are not academic. They are war-risk quotes, crew agreements, and a charterer who would rather pay more and sleep. When ministers talk about safeguarding navigation, they are talking about those quotes as much as about maps.
So the weekend contained two security stories that rhyme. A land campaign framed as a push to reopen authority and protect a chokepoint. A strike on the inland system that exists so crude can avoid a different chokepoint. Optimism on one does not cancel damage on the other. Anyone selling you a single narrative is selling you a position.
Claims, Counters, And What You Can Verify
Battlefield messaging is cheap. Export data is slower and better. Over the next stretch, the checks that matter are dull. Are Yanbu loadings keeping their recent pace? Are eastbound and westbound nomination patterns shifting? Do refined product cracks stay elevated after the crude flat price shrugs? Does freight on Red Sea routes ease, or does it stay sticky because crews and insurers remember longer than ministers do?
Rhetoric fails those tests all the time. A “new phase” can be real and still take months to change a loading calendar. A denial that mercenaries are advancing can be partly true and still irrelevant to whether a drone reached a substation. I would rather be slightly late and right on barrels than early and eloquent on slogans.
- Separate the confirmed halt from the repaired flow. Both can be true.
- Watch the node that was new, not only the nodes everyone already circled.
- Pair any Red Sea security claim with actual voyage behavior, not posts.
- Listen to the inventory clock. Two years is a horizon, not a promise, but it is not a shrug either.
- Price products on their own. Crude calming down is not a diesel pardon.
Why The First Hour Always Lies A Little
Supply scares have a rhythm. A source says stopped. A second source says damage. A price jumps. Then an operator, or someone close to nominations, says barrels are moving. Half the jump comes out. Commentators call the first report fake. It often was not fake. It was unfinished.
That rhythm is exhausting, and it is also useful. It trains you to ask timing questions. Stopped for how long? At what rate did it restart? Which customers were deferred, not cancelled? Deferred barrels are the quiet kind of tightness. They do not trend on social feeds. They show up when a refiner in the Mediterranean bids a cargo he used to ignore.
If you write about markets for a living, the temptation is to pick a camp in that first hour so you sound decisive. Resist it. Decisive and early is how bad oil notes get born. The better habit is a boring one. Write down what is confirmed, what is claimed, and what would falsify the claim by Wednesday.
Hormuz In The Background, Always
Nasser’s condition was specific. Until Hormuz fully reopens and confidence returns. Not until a press release says so. Confidence is a ship that actually sails, an insurer that cuts the quote, a buyer who stops demanding a discount for uncertainty. Full reopening without confidence is a map update. Confidence without volume is a mood. You need both before the emergency-stock story ends.
The East-West line is the physical argument that the kingdom can keep exporting while that confidence is incomplete. Hitting it is an attempt to knock out the argument. Missing, or damaging it only enough for a weekend pause, leaves the argument standing and a little more expensive to insure. That is a win for continuity and a loss for complacency. Markets are allowed to hold both.
Would Brent really have printed $200 without the line? I doubt anyone can prove the counterfactual cleanly. Price spikes that large invite demand destruction, strategic releases, and political deals that the straight-line story skips. Even so, the direction is the part worth keeping. Remove the bypass in a Gulf crisis and the clearing price jumps hard. Keep the bypass, and you buy time. Time is what a two-year restock needs.
What A Longer Outage Would Actually Change
Imagine, without turning it into fiction, a repair measured in weeks rather than a weekend. Eastern production does not vanish. It backs up into storage, then into Gulf export schedules that may themselves be constrained. Buyers who preferred Yanbu for political or logistical reasons scramble for substitutes. Differentials move before flat price does. Sour crude spreads, Red Sea premia, and freight all get a vote.
Refiners with little inventory cover run down stocks and pay up for prompt products. That is the “both ends” problem in operational language. A crude barrel you cannot place quickly becomes a diesel barrel you cannot make on time. The public sees the second part at the pump and calls it a mystery. It is not a mystery. It is a lag.
None of that is the base case after this particular strike. The base case, on the reporting we have, is a line that stopped and restarted. Base cases are for sizing positions, not for forgetting tails. The tail is a second or third hit on a station that was not on last month’s list.
Insurance, Crews, And The Cost You Do Not See In Brent
Flat price is the number everyone screenshots. The bill that changes behavior is often elsewhere. War-risk insurance. Extra security guards on a terminal. A longer ballast leg because an owner will not transit a strait this week. A refinery that delays a crude purchase until the nomination looks boring again. Those costs do not always lift Brent. They do lift the price of reliability, which is what industrial buyers actually purchase.
A brief, repaired attack still ticks those meters. Underwriters do not need a month-long outage to revise a corridor. They need a pattern. “Targeted several times” is a pattern. “Station not hit before” is how a pattern spreads. If you only model the barrels that failed to load, you will undercount the event.
A Practical Read For The Next Few Weeks
Here is how I would hold it, knowing I can be wrong by Wednesday and would rather admit that than marry a take. Flows are the fact that cools the panic. The new target is the fact that keeps the premium alive. The London remarks are the fact that stops you from calling the whole tape a local skirmish. Yemen messaging is color until voyages and territorial control show up in shipping data.
If loadings stay steady and no second station goes down, flat price can yawn. That yawn will tempt people to declare the story dead. It will not be dead. It will be dormant inside a larger squeeze that company leadership already called strained. Dormant risk is the kind that looks like a waste of worry right up until it is not.
Continuity now + repeat targeting + slow restock = a premium that fades in headlines and lingers in cracks.You can disagree with the weights. I would not zero any of the three terms. Zeroing the first term was the mistake in the early “pipeline stopped” posts. Zeroing the second is the mistake waiting in the “all clear” posts. Zeroing the third ignores the man who runs the barrels.
The Human Lag Inside A Fast Market
There is a smaller point, easy to skip. Repair crews, terminal operators, and ship planners absorb these weekends in their bodies, not in a model. Fatigue is not a price input until a night shift misses something a fresh crew would have caught. I have no evidence that happened here. I mention it because systems under repeated alert get sloppier at the edges. Sloppy edges are where the next “brief” halt becomes a longer one without anyone intending a dramatic strike.
That is not a prediction. It is a reason to respect operational updates more than victory posts. The people who know whether a pump is truly back are not writing thread-length arguments about who fled which ridge.
Where This Leaves Price, Without A Fake Forecast
I am not going to hand you a year-end target. Anyone who does, today, is guessing about Hormuz confidence, about whether the westbound corridor stays patchable, and about demand that can still disappoint. What can be said cleanly is conditional. If the bypass keeps working and the Gulf outlet slowly normalizes, the violent upside case weakens and the inventory rebuild still takes time. If the bypass gets a real outage while the Gulf outlet stays distrustful, the upside case Nasser sketched stops being a speech line.
Between those branches sits the dull middle, which is where most weeks live. Crude flows. Products stay firmer than the macro crowd expects. Freight refuses to cheapen on schedule. Headlines alternate between triumph and denial. The pipe keeps its role as the uncelebrated reason the dull middle exists at all.
Maybe that is the note to end on, because it matches the tape I watched. Not a collapse. Not an all-clear. A corridor that took another punch, stood back up, and reminded anyone paying attention that standing back up is a job it may be asked to do again. The barrels are moving. The question worth keeping is how many more weekends that sentence stays easy to write.
If you track this stuff for a portfolio rather than for sport, write the conditionals down before the next alert. What you will do if flows stay normal. What you will do if a second station joins the list. What you will ignore, which is most of the victory talk. The market will keep offering you speed. The pipe, and the stocks behind it, are offering you duration. Duration is the part Monday’s restart did not cancel.
]]>


