

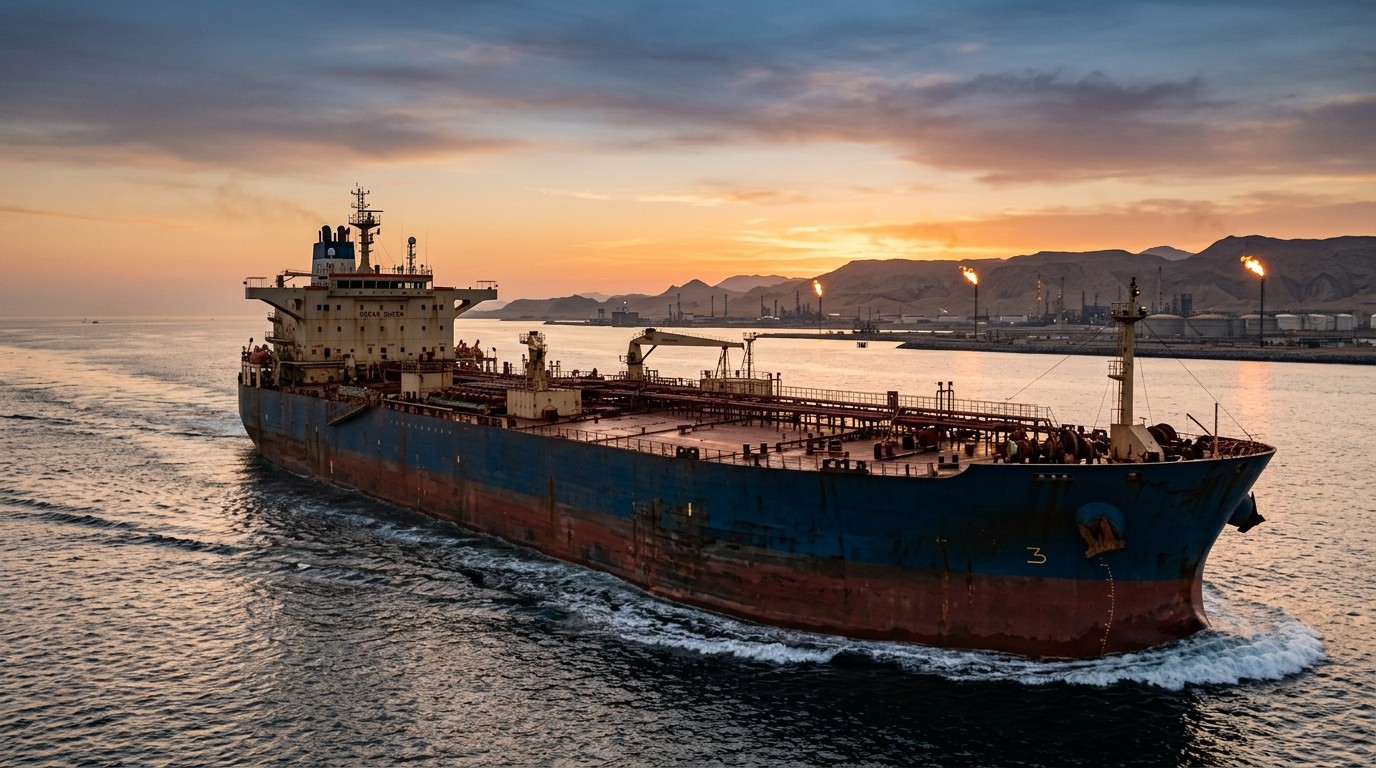
Saudi Oil Exports Hit Highest Level Since Iran War

Saudi crude shipments just jumped back to 6 million barrels a day after a pipeline hit. Prices eased. The real question is whether Hormuz stays open long enough for that rebound to last.
Financial market analysis from 25/09/2026. Market conditions may have changed since publication.
Have you ever watched a market panic over a single pipeline, then shrug two weeks later as if nothing much happened? That is roughly where oil traders sit right now. Saudi crude is moving again in volume, even after a drone strike knocked a key cross-kingdom line out of service. I keep coming back to one number: six million barrels a day in September. That is not a rumor from a chat room. It is the kind of flow data that makes desks sit up.
What The Latest Export Rebound Actually Means
September shipments from the kingdom have climbed back toward the monthly average seen through 2025. That is a sharp contrast with August, when exports sat near 3.4 million barrels a day. The jump is close to 80 percent. In plain language, cargoes that looked stranded found a route. Not a perfect route. A workable one.
The East-West line had become the market’s favorite safety valve. It let barrels leave eastern fields and reach the Red Sea without threading the Strait of Hormuz. When that line took damage and closed, Brent leapt toward 110 dollars. Then the price faded. Confidence crept back in. Ugly, cautious confidence, but still confidence.
In my view, the rebound is less a victory lap than a reminder. Energy infrastructure in the Gulf can be hit and still keep the world supplied, at least for a while. That “for a while” is doing a lot of work.
How The Kingdom Rerouted Barrels After The Outage
After the pipeline shut, exports did not simply vanish. They shifted. Tankers headed back toward Hormuz. The United States military has tried to keep a usable lane along Oman’s coast. Other Gulf producers have used that path for months. It is still a dangerous commute. Attacks on tankers have not stopped. They have just become part of the operating backdrop, which is a grim sentence to write.
Commodity researchers tracking seaborne flows have noted that the Gulf ramp-up is partly a direct answer to the pipeline outage. It also hints that skippers and charterers feel slightly more willing to use the strait because traffic itself is rising. Herd behavior works in shipping too. One successful transit makes the next one easier to insure, or at least easier to justify on a risk committee call.
The ramp-up from the Mideast Gulf is a consequence of the pipeline outage, but it likely also signals a greater confidence in using the Strait of Hormuz given rising traffic.
Hormuz flows recently printed a seven-day average around 13.2 million barrels a day. Before the wider conflict snarled traffic, that corridor often moved closer to 17 million. So the lane is open-ish. It is not normal. Anyone calling this a full reset is selling comfort.
Why Prices Jumped Then Softened So Fast
Oil loves a clean story. Pipeline down equals shortage. Shortage equals higher prices. Markets bought that story for a few sessions. Then inventory math and tanker tracking spoiled the plot. If barrels still leave the Gulf, the shortage is smaller than the headline. Traders fade the panic. That is the unromantic core of commodities.
I’ve found that the first price spike after infrastructure news is often a liquidity event more than a physical event. Options dealers hedge. Momentum funds chase. Physical desks wait for fixtures and load data. When the fixtures show up, the chart looks silly in hindsight. Not always. Often enough to keep veterans skeptical.
That does not mean 110 was irrational on the day it printed. It means the market priced a longer outage than the system actually delivered. Industry chatter now says the East-West line restarted at low rates earlier this week and is increasing throughput. Official public confirmation from Riyadh has been thin. A senior company executive told an overseas interview that interruptions to oil kit usually last days, not weeks or months. He declined a precise pipeline update. That mix of calm tone and missing detail is classic Gulf messaging.
The Pipeline That Became A Geopolitical Shortcut
Think of the East-West system as a pressure-release valve bolted onto geography. Eastern production wants the world. The shortest sea path is Hormuz. Hormuz can be squeezed. So you pump west to Yanbu and load on the Red Sea. Buyers in Europe and beyond get a route that avoids the most contested choke point. Insurers sleep a little better. Freight desks rewrite voyage calculations.
When that valve closes, two things happen at once. Physical optionality shrinks. Narrative risk explodes. Those are not the same problem, though they arrive in the same news cycle. Physical optionality is barrels, berths, and draft. Narrative risk is what a fund manager tells a client at 7 a.m.
- The line moves crude from eastern fields toward Red Sea terminals.
- It reduces dependence on a single maritime choke point.
- Damage forces more cargoes back onto the Hormuz path.
- Even a short halt can reprice risk premia across the curve.
Perhaps the most interesting aspect is how quickly the market treated the line as both indispensable and replaceable. Indispensable on Monday. Replaceable by Friday, once tankers lined up again. That whiplash is exhausting if you live on screens. It is also how energy markets have worked for decades. Redundancy is never free. It is also never complete.
Hormuz Traffic Is Recovering, Not Healing
A seven-day average of 13.2 million barrels is a serious number. It is also well below the pre-war rhythm. Call it a working corridor under military escort and private anxiety. Crews still face attack risk. Owners still wrestle with war-risk premiums. Charterers still argue about who pays for the extra insurance and the extra days.
Rising traffic can be its own security signal. More ships imply more eyes, more escorts, more commercial insistence that the lane remain usable. It can also be a target-rich environment. Both readings can be true on the same afternoon. That is the uncomfortable part.
Other Gulf states have leaned on the Oman-coast lane for months. Saudi barrels joining that stream is not a surprise so much as a late confirmation. When your western pipeline is wounded, you use the water you have. You do not wait for a perfect security briefing.
What Six Million Barrels A Day Signals To Buyers
For refiners, reliability beats poetry. A supplier that can still load near last year’s average after a strike is a supplier you keep on the slate. That does not erase political risk. It does change how procurement teams talk internally. They can say the barrels arrived. They cannot say the route was calm.
Asian buyers in particular watch loading programs the way other people watch weather. Delayed cargoes ripple into crack spreads, inventory draws, and awkward conversations with governments. A September rebound toward six million barrels a day takes some of that heat off. It does not put the file back in a drawer marked “normal.”
| Period | Export Picture | Market Read |
| Pre-conflict baseline | Higher Hormuz throughput near 17 million bpd regionally | Routine but watchful |
| August slump | Saudi crude near 3.4 million bpd | Severe disruption premium |
| September rebound | About 6 million bpd from the kingdom | Premium fades, risk remains |
| Recent Hormuz average | Around 13.2 million bpd over seven days | Partial recovery of the lane |
Numbers like these are snapshots. They age fast. A week of quiet loadings can be followed by a week of alerts. Anyone building a model on a single month should keep an eraser nearby.
The Quiet Role Of Military Lanes And Commercial Nerve
You can dislike militarized trade routes and still admit they move oil. The carved-out lane along Oman’s coast is not a tourist brochure. It is a workaround. Workarounds become habits if they last long enough. Habits become the new map.
Commercial nerve matters just as much. A captain, an owner, and an insurer have to agree that a voyage is worth the premium. When they do, cargoes sail. When they do not, you get floating storage, delayed programs, and angry emails from refineries. September’s rebound suggests enough of those three parties said yes.
I am not going to pretend that “yes” feels heroic. It feels like a calculated shrug. Markets run on calculated shrugs more often than speeches admit.
Why Official Silence On The Restart Still Matters
Private industry sources say the line is moving again at low volume and ramping. Public confirmation has not matched that detail. That gap is not a scandal. It is a style. Energy ministries and national oil companies often prefer deeds over press notes when infrastructure is sensitive.
Still, markets hate fog. Fog invites rumor. Rumor invites another spike. A short, dull operational update would probably do more for price stability than a polished interview about resilience. Dull is underrated in this business.
Temporary interruptions to oil infrastructure last usually for days, not weeks or months on every occasion.
That line is meant to soothe. It also sets a standard. If the next outage lasts longer than “days,” the soothe becomes a problem. Credibility in energy is a stock that draws down fast and rebuilds slowly.
What Traders Should Watch Next Without Getting Cute
Skip the grand forecasts for a minute. Watch fixtures. Watch the gap between nominated loadings and actual sailings. Watch war-risk premiums on the Gulf-to-Asia route. Watch whether Yanbu loadings recover as the western line gains rate. Watch product cracks in Europe if Red Sea optionality returns in size.
- Confirm whether pipeline volumes keep rising after the initial restart.
- Track Hormuz seven-day averages against the old 17 million baseline.
- Note any fresh attacks that change insurer appetite overnight.
- Compare Saudi loadings with the 2025 monthly average, not just August.
- Separate headline barrels from barrels that actually arrive on time.
That list is boring on purpose. Boring checklists keep people from turning a logistics story into a morality play. There is already enough of that online.
The Wider Market Still Sits On A Thin Cushion
Global balances were not overflowing with spare comfort before this latest hit. Spare capacity exists on paper. Moving it through contested water is another job. When one major exporter improvises routes and still hits six million barrels a day, the system looks tougher than the scare headlines. When you remember how close August came to 3.4 million, the system looks brittle. Both can live in the same paragraph.
I’ve sat through enough oil cycles to distrust the word “contained.” Contained is what people say before the next drone, the next premium spike, the next delayed very large crude carrier. The honest stance is narrower. This month’s flows recovered. Last month’s flows did not. Next month is not obligated to copy either one.
Demand is not a saint in this story either. If prices grind lower because the outage looks manageable, refiners run harder. If they run harder, inventories stop looking tight. If inventories stop looking tight, the geopolitical premium shrinks until the next shock puts it back. Round and round. You know the ride.
A Few Human Details Markets Pretend Not To See
Behind every loading number is a crew that slept poorly and an operations team that rerouted a program at 2 a.m. Behind every price pullback is a risk manager who still cannot quite close the file. We talk in million-barrel units because that is the language. The language hides the fatigue.
It also hides a simple truth. Consumers only notice this chain when gasoline or diesel jumps. Producers notice it every day. Midstream notices it when a weld, a pump, or a control room takes damage. The September rebound is good news for supply. It is not a holiday for the people who move the supply.
In my experience, the public debate swings between two lazy poles. One pole says the Gulf can always deliver. The other says one strike ends the modern economy. Reality keeps camping in the muddy middle, where exports recover and the route still looks like a bad neighborhood after dark.
How To Read The Next Headlines Without Whiplash
When the next alert hits, ask three questions. Did physical loadings change, or did only the words change? Is the affected kit unique, or is there a second path? How long did the last similar outage actually last once the dust settled? Those questions are not clever. They are a filter.
If loadings hold near the 2025 average while Hormuz traffic stays in the low-to-mid teens, the market can keep treating this as managed risk. If either leg breaks, the 110 handle stops looking like a curiosity and starts looking like a floor for the next squeeze.
Can the kingdom keep exporting at this clip if another piece of kit goes down? Maybe. That “maybe” is the entire trade. People who sell certainty here are not doing analysis. They are doing theater.
A Practical Takeaway For Anyone Who Follows Energy
Treat the September rebound as evidence of adaptability, not invincibility. Treat the pipeline restart chatter as constructive, not conclusive. Treat Hormuz’s 13.2 million barrel average as a partial reopening, not a peace dividend. Write those three sentences on a note if you have to. They will age better than most hot takes.
The story under the story is route diversity. One line west. One sea lane south. Military cover that nobody wanted to need. Commercial players who still lift cargo because the world still burns the stuff. That combination got September close to six million barrels a day. It might get October there too. It might not.
If you only remember one thing, remember the contrast. August looked like a supply scare with a face. September looks like a workaround that found its legs. Workarounds can run for years. They can also trip on the next piece of bad luck. Holding both ideas at once is not indecision. It is the job.
And if prices drift while the water stays tense, do not confuse a quieter screen with a safer map. The map is the same map. The tankers are just moving on it again.
Bitcoin is the beginning of something great: a currency without a government, something necessary and imperative.


Anthropic Founders Seek 50.1 Percent Voting Control Before IPO

Iced Coffee Job Interview Advice From Career Coaches
Related Articles

Eric Schmidt: Ukraine’s Drone Future of War
Eric Schmidt, ex-Google chief, now deeply involved in drone tech for Ukraine, claims its deadly "no man's land" shows how wars will be fought tomorrow. Drones vs drones, AI deciding kills—what happens when humans step back entirely?

JPMorgans Top Stock Ideas Entering May 2026
April delivered impressive gains across major indexes, but which stocks does JPMorgan favor heading into May? Their latest list highlights intriguing opportunities in fintech, manufacturing, and retail that could surprise investors this month...

Patos Meme Coin Presale Surges as Traders Exit ETH
While Ethereum struggles below key support levels and fear dominates the market, traders are quietly rotating into a new Solana-based meme coin called Patos. Its presale has already pulled in six figures with seven confirmed CEX listings coming... but what happens when it finally launches?