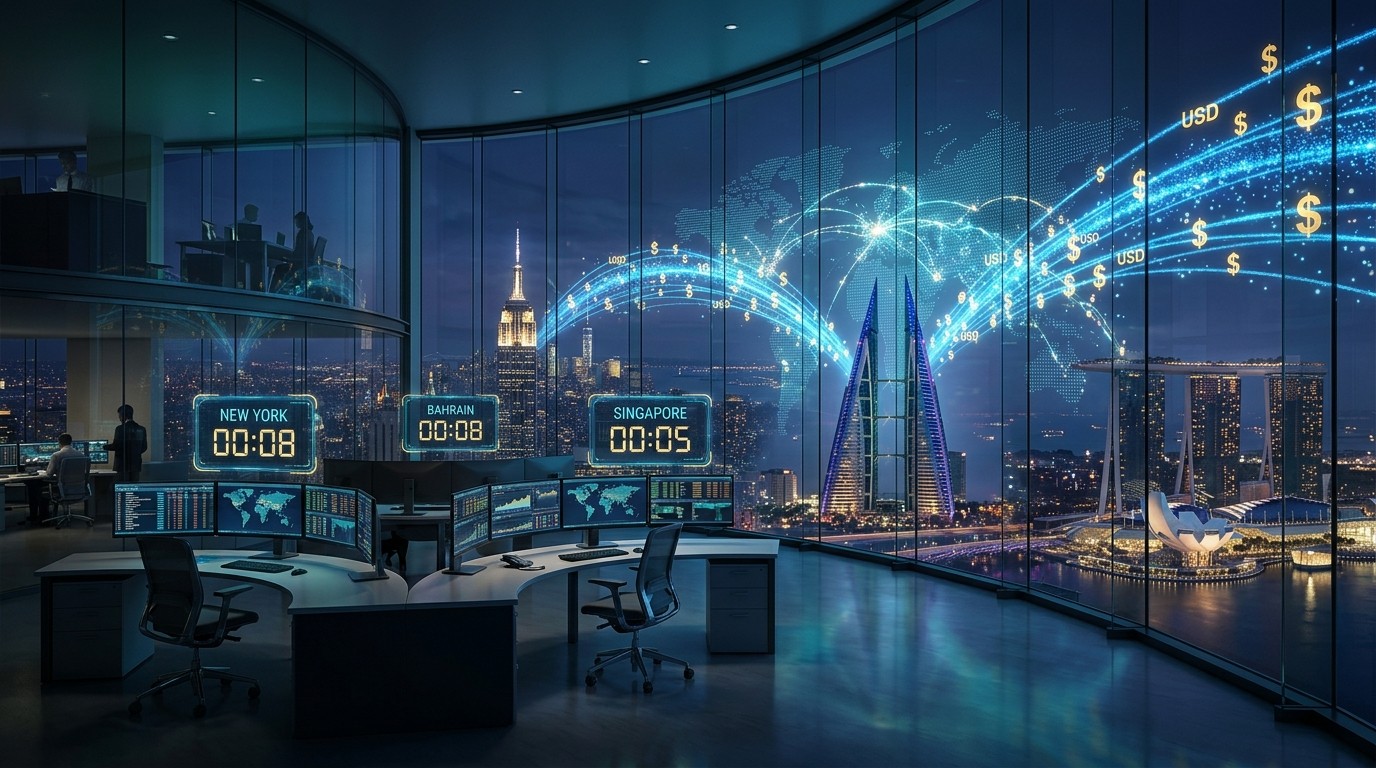

Have you ever watched a critical supplier payment sit frozen over a long weekend while your team scrambled for workarounds? I have seen that frustration play out more times than I can count, especially for companies whose operations stretch across Asia, the Gulf and the United States. The banking clock simply stops when New York markets close, and everything waits. That old limitation just took a serious hit.
A Fresh Step Toward Always-On Dollar Transfers
Singapore Gulf Bank has moved to give eligible clients something closer to continuous access. By plugging into a specialized 24/7 transfer service operated by a major global custodian, the bank now lets qualifying U.S. dollar payments settle outside traditional American banking hours. Weekends and U.S. public holidays no longer create the same hard stop they once did.
In my view, this is one of those practical upgrades that rarely make splashy headlines yet quietly change how money actually moves for real businesses. The service works between accounts held directly at the custodian or through correspondent banks that have enrolled in the same network. Not every transfer qualifies, of course. Both the sending and receiving institutions need to meet the network’s requirements, and the accounts themselves must be eligible. Still, for the clients who qualify, the difference is noticeable.
Corporate teams can now handle account funding, supplier payments and time-sensitive treasury moves without watching the calendar quite so anxiously. Retail clients who meet the criteria gain access as well, which is less common than you might expect. Most of these continuous-settlement tools stay locked inside institutional walls. Extending the reach a little further feels like a deliberate choice rather than an afterthought.
Why Continuous Settlement Matters Across Time Zones
Picture a trading desk in Singapore that needs to fund a position in New York on a Friday evening local time. Or a Gulf-based importer whose supplier invoice lands on a U.S. holiday. Under the old model, those payments sat in limbo until the next available banking window. Cash remained trapped. Opportunities slipped. Relationship managers fielded nervous calls.
The bank’s executive vice chairman put it plainly when discussing the move. Clients simply do not operate on a single time-zone schedule anymore. Their needs keep rolling while traditional U.S. banking hours stand still. That gap has grown more expensive as supply chains and digital asset businesses run around the clock.
Our clients operate across markets and time zones, and their business needs do not always fall within traditional US banking hours.
From the custodian’s perspective, continuous dollar settlement helps institutions manage available cash more precisely and meet urgent obligations without the usual weekend or holiday friction. I find that framing useful. It is less about technology for its own sake and more about removing friction that has quietly taxed companies for decades.
The relationship between the two institutions is not brand new. Earlier this year the bank joined the custodian’s broader correspondent banking network specifically to strengthen its U.S. dollar clearing capabilities. That earlier step laid the groundwork for the current expansion. Looking back, the sequence feels intentional rather than opportunistic.
How The Service Actually Works In Practice
Eligible transfers settle at any hour between accounts that sit either directly at the custodian or with enrolled correspondent banks. The key word remains “qualifying.” Both sides of the transaction need to participate in the network, and the accounts must meet specific criteria. Once those conditions are satisfied, the payment can move without waiting for the next U.S. banking day.
For corporate users the most immediate applications include funding operating accounts, settling supplier invoices that cannot wait, and executing treasury transactions where timing affects cost or risk. Retail clients who qualify gain a similar ability to move dollars outside the usual windows. That dual access is worth noting. Many continuous-payment solutions stay firmly institutional. Opening the door a bit wider changes the conversation.
I have spoken with treasury managers who describe the previous weekend freeze as a recurring operational tax. They built buffers, arranged backup funding lines, or simply accepted delayed settlement as the cost of doing international business. Removing even part of that tax improves cash-flow predictability. In competitive markets, predictability often matters more than pure speed.
The Bank’s Broader Payment Platform And Transaction Scale
The 24/7 dollar capability sits on top of an existing real-time settlement platform the bank launched last year. That platform, known internally as SGB Net, already processes more than twenty billion dollars in monthly fiat transactions. The volume figure is striking. It signals that the bank has already built meaningful traffic among digital-asset firms, payment providers and other institutions that need reliable multi-currency movement.
Despite the Singapore reference in its name, the bank holds its banking license from the Central Bank of Bahrain. Its backers include Bahrain’s sovereign wealth fund and a Singapore-based investment group. That cross-regional ownership structure mirrors the client base it aims to serve—companies whose activity routinely spans the Gulf and Asia.
Corporate banking services began in late 2024. The multi-currency real-time platform followed in May 2025. Adding continuous U.S. dollar transfers now feels like the logical next layer rather than a sudden pivot. Each step has expanded the hours and the corridors in which clients can move money.
Instant Funding Links For Institutional Trading
Only a week before the latest announcement, the bank confirmed a separate partnership that connects its settlement platform to an institutional trading venue. Selected institutional customers across supported Asian and Gulf jurisdictions can now settle transactions instantly in U.S. dollars. Additional currencies and client groups are planned for later stages.
For eligible clients the practical effect is immediate. Funds deposited onto the trading platform become available for trading without the usual banking-hour delay. In markets that never sleep, that difference can be decisive. Over-the-counter desks, exchanges and payment firms all operate continuously while traditional banks still observe fixed cutoffs. Bridging that mismatch has become a recurring theme in conversations I have had with digital-asset operators.
The same partnership also brings additional digital-asset liquidity into the bank’s offering. Over the coming months the bank intends to reference the partner’s markets when setting trade prices for its own customers. Layering settlement and liquidity together creates a tighter loop for institutions that need both cash movement and asset access in the same workflow.
Demand comes from exchanges, payment providers, over-the-counter trading desks and financial technology firms that operate continuously while banks maintain fixed settlement cutoffs.
That observation captures the core tension neatly. The operational day for many clients has lengthened. The banking day has not kept pace—until tools like these begin to close the gap.
Wider Industry Moves Toward Continuous And Tokenized Infrastructure
The same global custodian has been active on several related fronts. Reports earlier this month described ongoing discussions that could cover six distinct business areas, including crypto products, custody, wealth management, trading, payments and financial infrastructure. Those talks remain exploratory, yet they illustrate how traditional institutions continue testing deeper integration with digital-asset service providers.
On the cash side, the custodian has already launched a deposit-tokenization service. Participating customers can create blockchain entries that represent their existing demand-deposit claims. The service runs on a private network restricted to authorized participants. Customer balances stay recorded in traditional systems, and the usual risk, compliance and control frameworks continue to apply. The initial focus has been collateral and margin transactions—exactly the kind of high-frequency, time-sensitive activity that benefits from faster movement of value.
Separately, an institutional staking arrangement was announced earlier this year. Eligible institutions will eventually be able to access staking capabilities alongside custody, fund accounting, tax reporting, payments and client reporting. Customer assets remain inside the custodian’s framework while specialized infrastructure handles the staking layer. Regulatory review still applies, as one would expect.
Fund ownership records are also moving onto shared ledgers. A digital transfer-agency platform now maintains investor transactions and official shareholder records on blockchain while the traditional transfer-agency services continue in parallel. Early users include major asset managers preparing regulated tokenized funds. The scale of the underlying business—trillions in supported assets across millions of investor accounts—makes the experiment more than a proof of concept.
Taken together, these initiatives show a consistent direction. Large institutions are not abandoning existing systems. They are layering continuous settlement, tokenization and digital-asset capabilities onto the rails they already operate. The Singapore Gulf Bank expansion fits inside that broader pattern rather than standing apart from it.
Practical Implications For Corporate Treasury Teams
What does this mean day to day for a corporate treasurer? Several concrete changes stand out.
- Cash that previously sat idle over weekends can now be deployed or returned more quickly when both counterparties participate in the network.
- Supplier payments timed to production or shipping schedules become less dependent on the U.S. holiday calendar.
- Intraday liquidity management gains another tool for covering short-term gaps without drawing on more expensive backup facilities.
- Cross-border teams operating in Asia or the Gulf can initiate dollar movements that complete while New York is still closed.
None of these benefits is automatic. Eligibility rules remain. Not every bank or account is enrolled. Yet for those that qualify, the operational calendar lengthens in a useful way. I have found that treasury teams often value reliability over pure novelty. A service that works consistently on Saturday mornings or U.S. holidays earns more trust than one that merely promises speed under ideal conditions.
Risk and compliance teams will still apply the same scrutiny they always have. Continuous availability does not remove the need for sanctions screening, fraud controls or liquidity monitoring. It simply removes the artificial pause that used to occur every Friday evening New York time.
Looking Ahead At The Evolution Of Payment Rails
The move by Singapore Gulf Bank is incremental rather than revolutionary, and that is precisely why it matters. Incremental changes that actually reach clients tend to stick. Grand announcements about future rails often fade. Practical extensions of existing networks tend to compound.
We are watching several parallel tracks at once. Traditional correspondent banking is adding continuous settlement windows. Private blockchain networks are representing deposit claims. Tokenized fund records are appearing alongside conventional transfer agency systems. Institutional staking is being folded into custody platforms. Each track addresses a different friction point, yet all of them push toward greater continuity.
For companies whose working capital spans multiple time zones, the cumulative effect is already visible. The old assumption that money stops moving when the New York Fed window closes is eroding. It has not disappeared. It is simply less absolute than it used to be.
I expect more regional banks and specialized platforms to seek similar connections. The demand is real. Digital-asset businesses, global supply-chain operators and multi-currency treasury teams all feel the same pressure. Once a few institutions demonstrate reliable 24/7 dollar movement, competitive pressure does the rest.
Of course challenges remain. Network eligibility creates uneven access. Regulatory frameworks still differ across jurisdictions. Liquidity management inside continuous systems requires careful design. None of those issues vanishes overnight. Yet the direction of travel is clear enough that ignoring it carries its own cost.
A Quiet Shift With Lasting Consequences
Sometimes the most important banking changes arrive without fanfare. No dramatic product launch. No sweeping regulatory overhaul. Just a practical expansion of the hours in which eligible clients can move dollars. Singapore Gulf Bank’s adoption of continuous USD book transfers belongs in that category.
Clients whose operations never really stop now have one more tool that matches their actual schedule. Corporate treasurers gain a measure of relief from the weekend freeze. Retail clients who qualify receive access that was previously rare. Digital-asset institutions already using the bank’s real-time platform gain another settlement option that aligns with markets that trade around the clock.
The broader industry continues testing tokenization, staking and blockchain-based recordkeeping. Those experiments will take time to mature. In the meantime, extending the operating hours of existing dollar payment networks delivers immediate, measurable value. That combination—pragmatic near-term improvement alongside longer-term infrastructure work—feels like the most sustainable path forward.
I will be watching how quickly other institutions follow and how client adoption grows. Continuous settlement is no longer a theoretical discussion. It is becoming an operational reality for a growing set of eligible accounts. For anyone who has ever waited through a long weekend for a critical payment to clear, that reality arrives not a moment too soon.
The banking day is lengthening. The companies that adapt their cash-management processes accordingly will find themselves with a quieter, more predictable treasury function. In a world where markets and supply chains already run without pause, that quieter function may prove one of the more valuable competitive edges available.
Perhaps the most interesting aspect is how ordinary the service will eventually feel. Today continuous USD transfers still sound novel to many finance teams. In a few years they may simply be expected. The institutions that build the capability now will be the ones clients turn to when that expectation becomes standard. Singapore Gulf Bank has taken a clear step in that direction. Others will almost certainly follow.
Until then, the practical advice remains straightforward. Review eligibility for continuous settlement options. Map the payment flows that currently freeze over weekends or holidays. Calculate the opportunity cost of those freezes. And stay alert to further expansions of the networks that keep dollars moving when traditional clocks stop. The gap between continuous business needs and traditional banking hours is narrowing. Closing it further will reward the teams that prepare early.