
Have you ever stood in a store aisle or scrolled endlessly online, feeling that familiar knot in your stomach because you know the gift you want to buy sits well outside what you can actually afford right now? You are far from alone. Almost half of adults surveyed recently admitted they would take on debt just to purchase a present if the money was not available at the moment. That pressure hits hard during the holidays, when expectations climb and wallets feel thinner than ever.
I have watched friends and family fall into this trap year after year. They swipe the card, tell themselves they will figure it out later, and then spend January and February paying interest on something that was supposed to bring joy. The financial planner in me always wants to step in and say the same thing: if you already know you cannot comfortably cover the cost, forcing the purchase usually starts a chain of harder choices down the road. Regular bills get delayed. Credit balances creep up. Stress multiplies. It does not have to unfold that way.
With a bit of realistic planning and a few practical tools, thoughtful gifts remain completely possible even when money feels tight. The goal is simple. Give from a place of intention rather than obligation or panic. Below I walk through clear steps that have helped many people keep their holiday spending under control while still making the people they care about feel valued.
Build Your Holiday Gift Plan Around What You Can Truly Afford
Everything starts with an honest number. Before you browse a single product or write a single name on a list, sit down and decide exactly how much money you can spend without touching rent, groceries, or emergency savings. A useful rule of thumb many people follow is one to two percent of annual take-home pay. Multiply that yearly figure by 0.02 and you have a solid upper limit. That number becomes your total gift budget for everyone on your list.
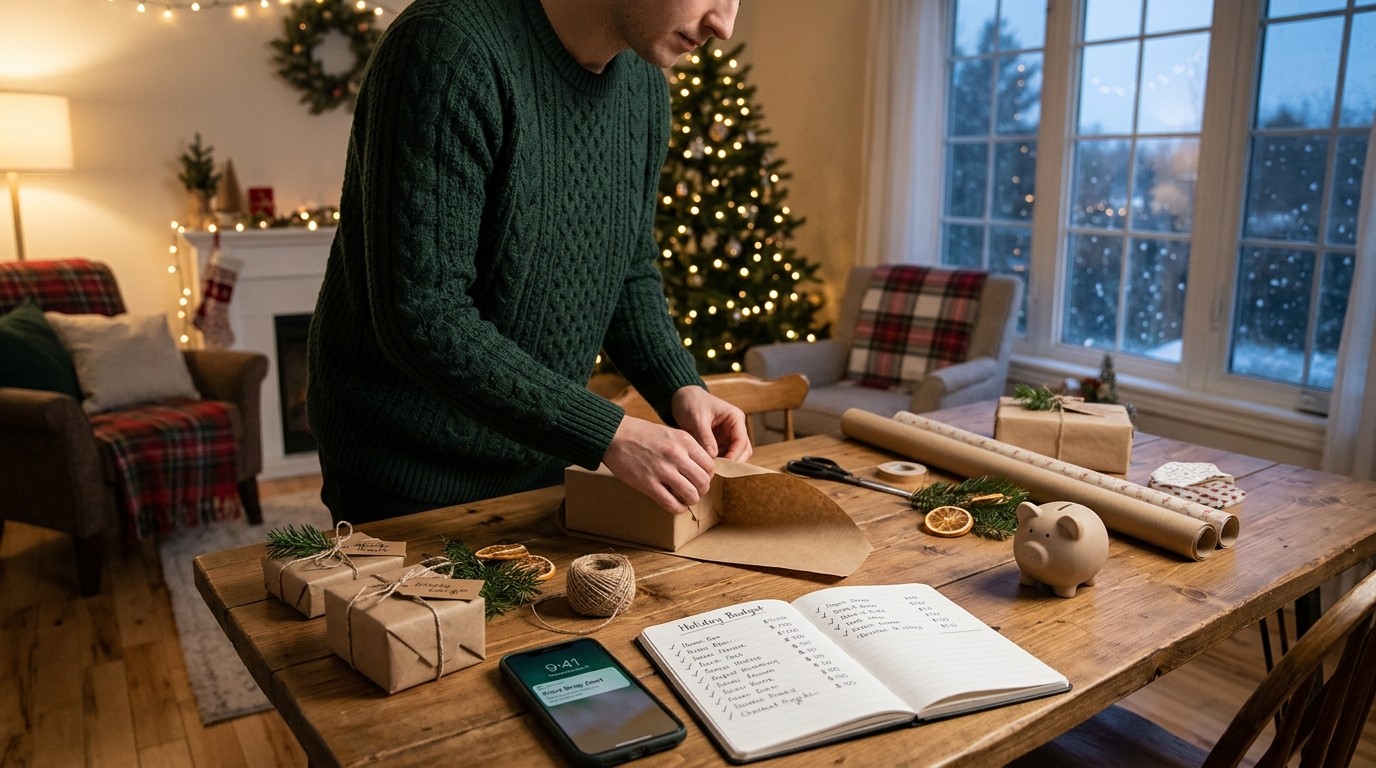
Once the overall amount is set, break it down. Write every name and assign a realistic portion. Leave a small buffer for last-minute needs or shipping costs. The moment you treat the total as fixed rather than flexible, decision-making becomes much easier. You stop asking “what would be nice” and start asking “what fits the amount I have decided.”
Track Every Dollar With Simple Tools
A budget only works if you can see where the money goes in real time. Several free and low-cost apps make this almost effortless. One popular option connects directly to your bank and credit accounts so transactions appear automatically. It sorts spending into categories and sends alerts when you approach the limits you set. Another tool focuses on assigning every dollar a job ahead of time. You can create a dedicated holiday category and watch the available amount decrease as you shop.
I have found that simply seeing the running total changes behavior. When the remaining balance sits right in front of you, impulse clicks lose their power. Set a daily or weekly spending cap inside the app if that helps. The point is visibility. Hidden spending is what usually derails holiday plans.
Create a Dedicated Holiday Savings Account
After the budget number is clear, move the money out of your everyday checking account. Open a separate high-yield savings account and start transferring small amounts regularly. Even modest weekly deposits add up faster than most people expect, especially when the account earns meaningful interest. Several options currently offer rates well above traditional savings accounts with no monthly fees and no minimum balance requirements.
Keeping the holiday fund separate removes temptation. The money is no longer mixed with grocery money or bill money. When shopping season arrives, you simply transfer what you need and the rest stays protected. Starting this habit even a few months ahead makes a noticeable difference. If the holidays are already close, begin anyway. Every bit helps.
Use Price Alerts So You Never Overpay
Online shopping dominates the holiday season for good reason. The downside is that prices bounce around constantly. One of the easiest ways to protect your budget is to set alerts on the specific items you already know you want. Free tools track millions of products and notify you the moment the price drops to a level you choose. You can also review historical price charts to understand whether the current number is actually a good deal or just marketing language.
This approach turns passive waiting into an active advantage. Instead of buying the moment something appears in your feed, you decide the maximum you are willing to pay and let the alert do the watching. Many people discover that waiting two or three weeks saves them twenty or thirty percent on the exact same product. That extra money can either stretch further across the gift list or stay in the savings account.
Consider a Zero Percent Introductory Credit Card Only If You Have a Clear Payoff Plan
Sometimes a larger purchase makes sense and the cash is not immediately available. In those limited cases a credit card that offers a long interest-free introductory period can serve as a short-term bridge. The key phrase is short-term. You must be certain the full balance will be paid before the promotional rate ends. Otherwise the interest that follows can erase any benefit.
Cards currently available provide introductory periods ranging from fifteen to twenty-one months on purchases. That window gives breathing room if you plan to pay the balance in steady monthly chunks. Treat the card like a structured installment plan rather than free money. Calculate the exact monthly amount needed to clear the debt on time and set up automatic payments. Anything less turns a helpful tool into an expensive problem.
Even with a zero percent offer, remember that higher credit utilization can temporarily affect your credit score. Keep total balances low relative to your limits whenever possible. The moment the promotional period ends, any remaining balance begins accruing regular interest rates that are rarely kind.
What You Should Strongly Avoid This Season
Not every financing option is created equal. Some choices create more trouble than they solve. Personal loans for gifts almost always come with interest and strict repayment schedules. Missing a payment can damage your credit for years. High-interest credit cards used without a payoff plan turn a one-time purchase into months or years of extra cost. Buy-now-pay-later services sometimes hide fees and make returns more complicated than necessary.
The pattern is consistent. Any form of debt taken on purely for presents tends to cost more than the original price of the gift. The emotional high of giving fades quickly when January statements arrive. Protecting your future self is one of the kindest gifts you can give.
If you already know the purchase sits outside your current means, forcing it usually starts a series of harder financial decisions later.
Practical Ways To Stretch A Smaller Budget Further
Thoughtful does not have to mean expensive. Many of the most memorable gifts cost little or nothing beyond time and attention. A handwritten letter describing specific reasons you appreciate someone often lands more deeply than any store-bought item. Homemade treats, carefully chosen second-hand books, or experiences you can share later (a planned picnic, a movie night at home with their favorite snacks) frequently outperform pricey gadgets that gather dust.
Consider group gifts for larger families. Pooling resources with siblings or cousins for one meaningful present for parents or grandparents reduces individual pressure while still delivering impact. The same principle works for friend groups. One well-chosen shared experience can replace half a dozen smaller items.
Another approach that works surprisingly well is the “one big, several small” method. Choose one person who receives a slightly larger gift and keep the rest modest. Most people do not track comparative spending across the entire list. They remember how the gift made them feel.
Timing Matters More Than You Might Think
Shopping early removes urgency and expands options. Many retailers run quieter sales in late summer and early fall that rival or beat Black Friday pricing. Waiting until the final weeks almost always means higher prices, limited stock, and shipping premiums. Setting calendar reminders for specific product categories two or three months ahead keeps the process calm.
If you prefer in-person shopping, visit stores during off-peak hours. Midweek mornings often have better staff availability and less chaotic displays. You make clearer decisions when you are not fighting crowds or time pressure.
Involve The Whole Household In The Plan
When children or partners are part of the picture, transparency helps. Explain the overall budget in age-appropriate language. Kids often enjoy helping choose or create gifts once they understand the limits. Partners who share finances benefit from agreeing on the total number together so no one feels surprised later. Shared ownership of the plan reduces last-minute arguments and secret spending.
Some families adopt a simple rule such as “three gifts only” or “homemade plus one store item.” These guidelines create structure without feeling restrictive. The conversation itself often becomes more meaningful than the actual presents.
Handling The Emotional Side Of Holiday Spending
Money stress and holiday expectations form a potent mix. Social media feeds full of elaborate gift unboxings do not help. Remember that most of those images represent carefully curated moments rather than everyday reality. Comparing your situation to someone else’s highlight reel almost always leads to unnecessary pressure.
If certain relationships feel particularly demanding around gift expectations, a gentle conversation ahead of time can reset the tone. Many people feel relieved when someone else suggests scaling back. You might discover that the other person was also feeling stretched and simply did not know how to say it.
Protecting your peace matters as much as protecting your bank account. A calm, present version of yourself is often the best gift you can offer the people around you.
Building Better Habits That Last Beyond December
The systems you put in place for holiday gifts can improve money management year-round. Continuing to use a budgeting app, maintaining a separate savings account for future goals, and practicing price tracking all transfer easily to other large expenses. Birthdays, anniversaries, and back-to-school seasons become less stressful when the same approach is already familiar.
I have noticed that people who treat holiday spending as one more planned category rather than a special exception tend to feel more in control overall. The holidays stop being a financial emergency and become simply another season with its own set of intentional choices.
A Simple Checklist You Can Start Using Today
- Calculate your total available gift budget using one to two percent of take-home pay as a guide
- List every recipient and assign a specific dollar amount to each
- Open or designate a separate savings account and begin transferring money weekly
- Set price alerts on any items you already know you want
- Decide in advance whether a zero percent card makes sense and only if a clear payoff schedule exists
- Identify at least three people who would genuinely appreciate a low-cost or handmade gift
- Schedule shopping sessions early enough to avoid last-minute premiums
Work through the list at a pace that feels manageable. Even completing the first two items creates immediate clarity.
Why This Approach Feels Different
Most holiday money advice focuses on finding the deepest discounts or the best credit card rewards. Those tactics can help at the margins, yet they still assume spending will happen at a certain level. The method outlined here starts earlier. It asks what you can truly afford and then designs the entire experience around that number. The result is less anxiety, fewer January regrets, and gifts that feel chosen rather than forced.
Perhaps the most interesting part is how often people discover they enjoy the process more once the pressure of overspending disappears. Creativity increases. Conversations deepen. The season feels lighter. That outcome is available to anyone willing to set a clear boundary and stick to it.
The holidays will arrive whether or not the budget is perfect. Choosing to meet them with intention rather than impulse is one of the most practical forms of self-care available right now. Your future self will thank you when the credit card statement arrives and the balance looks manageable. The people receiving your gifts will remember the thought far longer than the price tag.
Start with the number you can afford. Protect that number. Shop from it. Everything else becomes simpler. This year can be the one where generosity and financial calm finally share the same season.