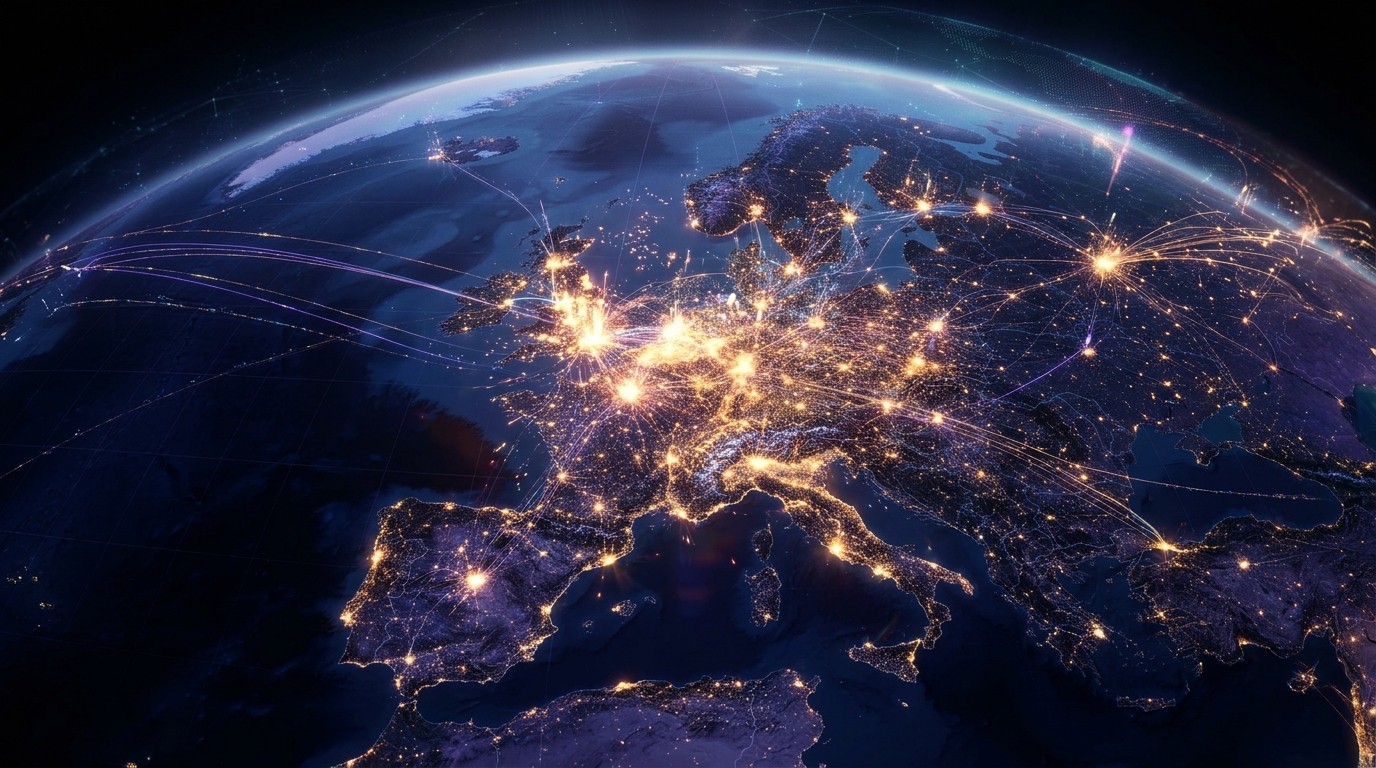

Seventy-two point eight percent. That single number stopped me when I first saw it. Nearly three-quarters of all staked SOL now sits with validators operating inside Europe. Not spread across the continent in some balanced way, but heavily clustered along a corridor running from Amsterdam through Frankfurt and into London. The rest of the world shares the remaining slice. North America holds 16.2 percent. Asia sits at 10.6 percent. South America barely registers at 0.4 percent. When one region carries that much weight, every performance change and every regulatory conversation suddenly feels heavier.
Why Europe Dominates Solana Stake Right Now
The latest quarterly staking analysis makes the geographic picture clear. Validators based in Europe control 72.8 percent of delegated SOL. That is more than four times the combined stake assigned to the other three major regions. The data comes from a careful mapping of operator locations rather than the citizenship of the people who actually own the tokens. Token holders can delegate without handing over ownership, so a validator sitting in Frankfurt does not automatically mean the stake belongs to a German or Dutch investor. Still, the physical location of the machines matters a great deal for latency and reliability.
Amsterdam, Frankfurt and London form the clear spine of this concentration. These cities already host some of the densest internet exchange points on the planet. Low latency, reliable power, and established data-center ecosystems make them natural homes for high-performance validators. Other European cities contribute as well, yet the report does not break the numbers down to individual cities or hosting providers. What we do know is that the overall European share dwarfs every other region.
I have watched Solana’s validator set evolve for a while, and this level of geographic tilt feels more pronounced than in earlier years. Earlier research looked at a different kind of concentration: nineteen validators holding enough stake to cross a thirty-three percent threshold. That older work used different geographic snapshots, so direct comparison is messy. The new figures focus purely on where the hardware sits today. And today, Europe sits firmly in the driver’s seat.
How the Numbers Break Down Across Continents
Let me lay the regional split out cleanly so the scale becomes obvious.
| Region | Share of Staked SOL |
| Europe | 72.8% |
| North America | 16.2% |
| Asia | 10.6% |
| South America | 0.4% |
Europe’s lead is not subtle. North America still holds a respectable second place, yet the gap is wide. Asia’s share sits lower than many people might expect given the size of crypto activity in the region. South America remains almost a rounding error. These percentages describe operator locations only. They say nothing about the nationality of the people who delegated the tokens. That distinction matters when conversations turn toward regulation.
In my view the concentration reflects practical advantages more than any coordinated plan. Fast fiber routes, mature hosting markets, and a critical mass of experienced operators create a gravitational pull. Once a few strong validators establish themselves in a location, others tend to follow because the performance numbers look better there. The result is the map we see now.
Faster Slot Times Change the Game for Distant Validators
Solana has been aggressively shortening its target slot time. The network moved from 400 milliseconds down to 350, then 300, and finally to 250 milliseconds on September 18. Each reduction leaves less room for validators to receive a block, process it, and get their vote back into the network. At the original 400-millisecond setting, more than 98 percent of votes from Europe, North America and Asia arrived inside a single slot. That comfortable margin disappeared once the target hit 250 milliseconds.
Under the new timing, European validators still managed 95.8 percent one-slot vote arrivals. North America came in at 92.8 percent. Asia dropped to 70.7 percent. South America sat at 70.3 percent. The gap between Europe and Asia now stretches more than twenty-five percentage points. That is not a small difference. Operators farther from the dense European internet hubs simply have less time to react.
A four-slot leader window now lasts roughly one second instead of 1.6 seconds. Every millisecond counts. Validators located near the major European exchanges enjoy a structural advantage that becomes more visible as the network pushes toward even faster targets. Talk of a future 200-millisecond slot time is already circulating. If that arrives, the performance spread could widen further.
Nearly all votes still arrive within two slots, which limits the damage to staking rewards. Network skip rates actually improved, falling from a median of 0.08 percent under the older timing to 0.04 percent at 250 milliseconds.
The network as a whole continues to function smoothly. Skip rates remain low. Most votes still land in time to earn rewards. Yet the regional disparity is now measurable and growing. Distant operators face a steeper climb if they want to stay competitive on pure performance metrics.
Does Geographic Concentration Create Regulatory Exposure
Whenever a large share of infrastructure sits inside Europe, questions about MiCA surface quickly. The 72.8 percent figure should not be read as the percentage of the network automatically subject to European Union rules. London sits outside MiCA’s reach. Validator location alone does not determine whether an operator provides a regulated crypto-asset service or holds customer assets under a licensing regime.
Guidance from European securities authorities focuses on firms that combine staking services with custody. Simply running validator hardware on European soil does not automatically trigger authorization requirements. The report itself does not break out an EU-only percentage, nor does it identify which operators offer custodial staking products. Without that finer detail, the regulatory picture stays incomplete.
I find the distinction important. People sometimes treat any European presence as equivalent to full MiCA coverage. Reality is more nuanced. Operators can choose their legal structure, their customer base, and the exact services they offer. Location of the servers is only one piece of a larger puzzle. Still, the sheer scale of the European share means any future clarification of the rules will matter to a large portion of the network’s stake.
Recent Infrastructure Stress Tests the System
Geographic concentration carries practical risks beyond regulation. In August a routing problem at one infrastructure provider took 102 validators offline. Those machines stopped voting. The network continued producing blocks, and the affected validators recovered within roughly forty minutes. During the outage an estimated 28.83 percent of delegated SOL temporarily became delinquent. The incident touched infrastructure in Amsterdam, London, Frankfurt, Singapore and Tokyo. Concentration in a handful of hosting environments can amplify the impact of a single routing failure.
That episode serves as a useful reminder. High geographic density improves average latency for many participants, yet it also creates correlated risk. When multiple high-stake validators share the same upstream provider or the same metropolitan fiber routes, a localized problem can ripple farther than expected. Solana recovered cleanly in that case. Future incidents may not be so forgiving if the share of stake sitting in the same corridors continues to grow.
Staking Economics and Validator Count Trends
Beyond geography, the broader staking picture shows a network that remains heavily committed. Roughly 69 percent of the total SOL supply sits staked at the end of the third quarter. Gross staking yield came in at 5.99 percent, a modest decline from the previous 6.38 percent. Validator count slipped from 696 to 659 during the quarter. Rising operating costs appear to be the main driver of the reduction. Running a competitive Solana validator is not cheap, and tighter margins push some operators out.
Network revenue for the quarter reached 75.7 million dollars. Tracked staker revenue totaled approximately 495 million dollars. Of that amount, 484.4 million dollars came from newly issued SOL and 10.6 million dollars from tips. Those tip numbers exclude other forms of validator income, so the full economic picture is larger still. The combination of high stake participation and respectable yields keeps the system attractive for many delegators even as the validator set contracts slightly.
I have always believed that a shrinking validator count deserves attention, yet the absolute numbers remain healthy. Hundreds of operators still compete. The more interesting question is whether the geographic concentration and the performance pressure from faster slots will accelerate further consolidation among the strongest European players.
What the Performance Gap Means for Future Upgrades
Solana’s developers continue to chase lower latency. The move to 250-millisecond slots already exposed clear regional differences. A potential step down to 200 milliseconds would tighten the window even more. Operators far from the European core will need better connectivity, smarter networking stacks, or both if they want to keep their one-slot arrival rates competitive.
Some distant validators may respond by relocating hardware closer to the major hubs. Others may invest in private interconnects or more aggressive peering. A few may simply accept lower performance metrics and focus on other differentiators such as commission rates or client software diversity. The network’s overall skip rate stayed low even after the latest speed increase, which suggests the system as a whole is coping. Individual operators outside the core, however, face a tougher environment.
Perhaps the most interesting aspect is how these technical choices interact with decentralization goals. Faster blocks improve user experience and can increase throughput. At the same time they reward physical proximity to the densest clusters of existing stake. Balancing those two forces will remain an ongoing challenge.
Practical Takeaways for Delegators and Operators
If you delegate SOL, the geographic story matters mainly through performance and risk. Validators with consistently high vote arrival rates tend to deliver more reliable rewards. European operators currently enjoy an edge on that metric under the faster slot times. At the same time, heavy concentration in a few cities and providers introduces correlated risk that is harder to see from a simple uptime dashboard.
- Check recent vote arrival and skip statistics rather than relying only on advertised commission rates.
- Diversify across a few well-run validators instead of concentrating everything with the single largest operator.
- Watch for any future changes in slot timing that could further widen regional performance gaps.
- Remember that validator location does not equal token-owner location when thinking about regulatory exposure.
Operators outside Europe face a clearer set of choices. Improve connectivity, move closer to the core, or accept a performance handicap and compete on other dimensions. The data shows the handicap is real. Ignoring it will become more costly if the network continues its path toward still shorter slots.
Looking Ahead at Network Resilience
Solana has demonstrated an ability to keep producing blocks even when a sizable share of validators goes temporarily offline. That resilience is valuable. Yet resilience is not the same as optimal decentralization. A network that functions during stress tests can still carry hidden geographic and infrastructure risks. The current 72.8 percent European share is simply the clearest quantifiable expression of those risks today.
Future reports will tell us whether the concentration continues to deepen or begins to ease. Faster slot times may pull more stake toward the low-latency European corridor. Regulatory clarity could push some operators to adjust their legal and operational footprints. Market forces around yields and costs will keep pruning the validator set. All of these currents are moving at once.
I keep coming back to that single statistic. Seventy-two point eight percent is not a crisis. The network continues to process transactions, skip rates are low, and overall staking participation remains high. It is, however, a signal. Geographic distribution is no longer a secondary detail. It sits at the intersection of performance, risk, and future protocol design. Anyone serious about Solana’s long-term health should watch how that number evolves over the next several quarters.
The story of Solana’s stake map is still being written. Europe currently holds the pen. Whether that continues depends on technical decisions, infrastructure investment, and the quiet choices of thousands of token holders who decide where to point their delegations. The data gives us a clear snapshot. What happens next will determine whether the snapshot becomes a lasting portrait or simply a moment in a longer rebalancing process.
For now the numbers stand. European validators control the large majority of staked SOL. Faster blocks have made the performance advantages of that concentration more visible. The network keeps running. And the conversation about what healthy geographic distribution should look like has become harder to ignore.