

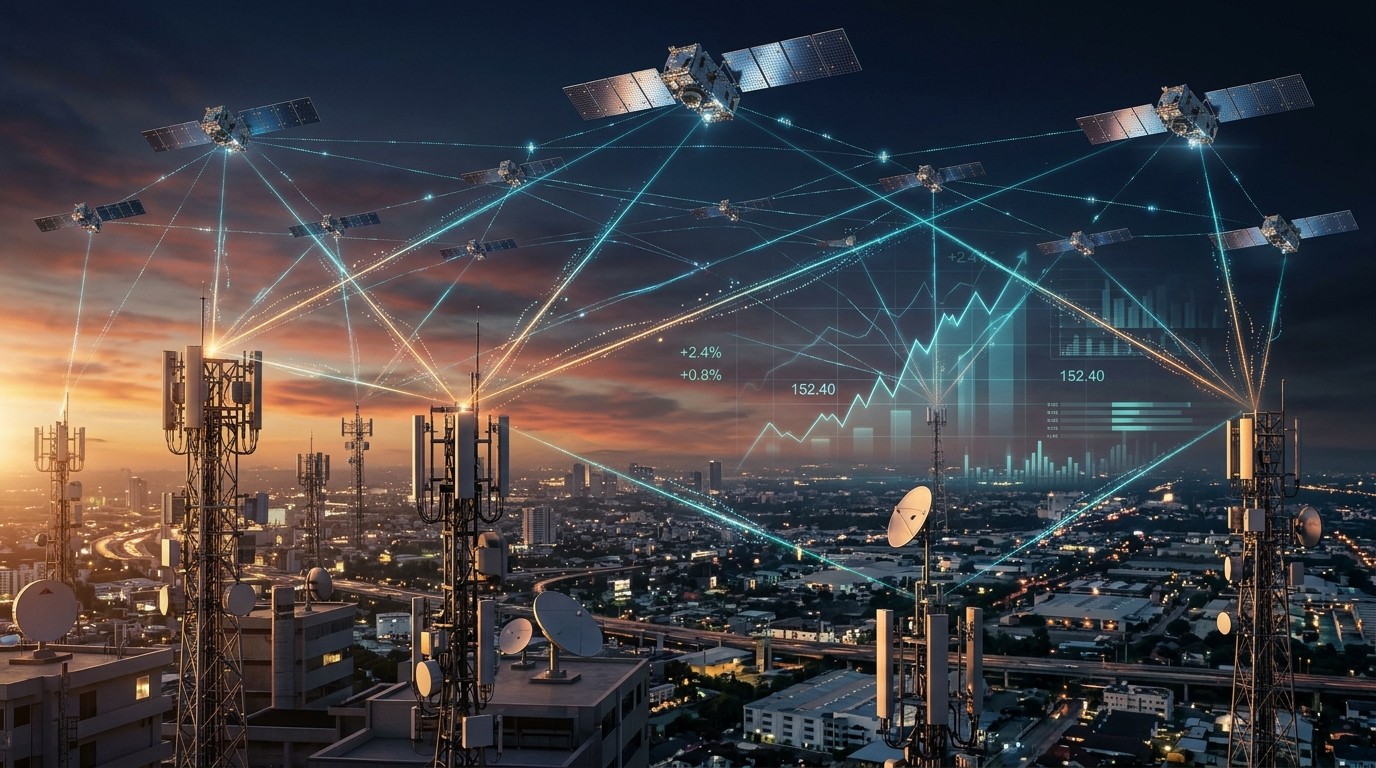
SpaceX Cell Sites Ambitions Catch Wall Street Attention

SpaceX is quietly eyeing tens of thousands of cell sites while Wall Street tries to decode the real play. Tower stocks jump, big telecoms slide, and the strategy looks bigger than anyone first thought. What comes next could reshape outdoor wireless coverage for good.
Financial market analysis from 25/10/2026. Market conditions may have changed since publication.
I’ve been watching the wireless space for years, and every so often a development lands that makes you sit up a little straighter. This latest round of SpaceX activity around cell sites feels like one of those moments. The company appears to be exploring access to a massive number of locations that could support ground-based coverage, and Wall Street has already started drawing lines between the dots. What looks on the surface like a simple real-estate conversation may actually signal a deeper shift in how SpaceX plans to build and control its outdoor network footprint.
Why Analysts Are Paying Close Attention Right Now
The chatter centers on discussions involving tens of thousands of cell sites. At first glance the number alone grabs attention. Dig a little deeper and the real story becomes the distinction many observers are making between traditional cell towers and the broader category of cell sites. That difference matters more than most people realize.
Cell towers tend to be the tall freestanding structures we all picture along highways. Cell sites, however, cover a much wider range of placements. Rooftops, billboards, water tanks, distributed antenna systems, and small cells all fall under the same umbrella. Industry voices have been careful to point out that SpaceX could be looking at a mix of these options rather than only the big macro towers. That flexibility opens doors that pure tower leases might not.
In my view, this nuance is the part worth watching most closely. If the company can place equipment on a variety of existing structures, it gains speed and potentially lower costs. It also avoids some of the political and zoning headaches that often slow traditional tower builds. The approach feels pragmatic rather than flashy, which fits the pattern SpaceX has shown in other businesses.
The Spectrum Puzzle Piece That Changes Everything
Earlier this month SpaceX moved to acquire a sizable portfolio of low-band spectrum in the 800 MHz range. That frequency has a special quality: it penetrates walls and windows better than higher bands. For a company already strong in satellite connectivity, adding this layer creates an interesting hybrid possibility.
One experienced observer noted that the bulk of everyday voice and text traffic could ride on that coverage layer while data-heavy use inside homes gets offloaded onto existing Starlink Wi-Fi. The idea is simple but powerful. Customers who already have a dish at home would lean on their indoor network for most smartphone data, while the new spectrum handles the outdoor and mobility side. It is the kind of complementary setup that can stretch limited resources further than pure cellular builds usually allow.
I find this angle particularly compelling because it builds on what SpaceX already does well. Instead of starting from zero, the company appears to be stitching satellite capability together with terrestrial spectrum and now potentially widespread site access. The combination could let it punch above its weight in coverage quality without matching the decades of infrastructure the established players already own.
How Wall Street Is Interpreting the Moves
Reaction in the markets has been swift and revealing. Shares of major tower companies climbed sharply after the reports surfaced. One of the firms reportedly in talks with SpaceX saw a particularly strong single-day gain. At the same time, the large traditional wireless carriers experienced noticeable pressure. Investors clearly see the possibility of heightened competition and are adjusting positions accordingly.
Several analysts have framed the potential site agreements as evidence that SpaceX is shifting toward greater ownership of its economics. Rather than relying heavily on partners for network reach, the company seems increasingly comfortable building or leasing the pieces it needs directly. That shift carries both opportunity and risk. Control brings flexibility, but it also brings the heavy capital and operational demands that have defined the telecom business for decades.
Entering into large-scale site arrangements would reinforce the direction recent spectrum moves already suggested. The company appears more willing to pursue owner economics instead of depending primarily on partners.
That perspective captures the broader narrative many on the Street are adopting. SpaceX is no longer content to stay purely in the satellite lane. It is assembling the ingredients of a more complete wireless offering, and the market is trying to price what that might mean for everyone else.
Small Cells Versus Macro Sites: The Practical Reality
Not every location under discussion needs to be a full-size tower. Some analysts have openly wondered whether a meaningful portion of the reported sites could involve smaller form factors. Small cells, for instance, can fill coverage gaps in dense areas or add capacity where demand spikes. They are quicker to deploy in many cases and can sit on existing urban infrastructure with less visual impact.
This possibility matters because it changes the competitive dynamic. A pure macro-tower strategy would put SpaceX in more direct confrontation with the established players on their strongest ground. A blended approach that mixes larger sites with smaller, more targeted deployments could let the company pick its battles and focus on areas where satellite-terrestrial hybrid service creates real differentiation.
From where I sit, the blended model looks smarter. SpaceX already has a residential customer base that trusts its equipment. Extending outdoor coverage in a way that feels seamless with the home experience could prove more attractive than trying to match every feature of a traditional nationwide cellular network from day one.
What Established Carriers Are Saying Behind Closed Doors
The big wireless operators have not been silent. During recent earnings discussions, at least one chief executive reminded listeners how many years and how much capital it takes to deliver the performance levels customers now expect. The comment felt like both a statement of fact and a subtle warning. Building reliable, high-quality mobile networks is hard, expensive work that rewards scale and experience.
That perspective is fair. Coverage maps, call reliability, data speeds during peak hours, and seamless handoffs between cells all require continuous investment and fine-tuning. New entrants often underestimate the operational complexity. Yet history also shows that determined newcomers with fresh technology and different cost structures can still carve out meaningful positions, especially when they target specific customer needs the incumbents have under-served.
SpaceX starts with a few advantages the traditional carriers cannot easily copy. Its satellite constellation already delivers broadband to places that were previously uneconomical to reach. Adding terrestrial spectrum and site access could let it offer a more complete package to those same customers while also expanding into denser markets. Whether that package will satisfy the average urban smartphone user remains an open question, but the ambition is clear.
The Residential Customer Angle Few Are Discussing
One of the more intriguing observations circulating among analysts involves how fixed wireless and home Wi-Fi already shape phone behavior. Many households that subscribe to home broadband end up routing the majority of their smartphone data through that network once they are inside. Voice and text may still travel over cellular, but the heavy lifting happens on Wi-Fi.
Apply the same logic to Starlink households and the picture becomes interesting. A customer who already has a dish could treat the outdoor SpaceX coverage primarily as a mobility layer while relying on the home connection for most data. That pattern would reduce the amount of spectrum and capacity the company needs to deliver a competitive experience. It also creates a natural upgrade path: start with satellite broadband, then add the mobile component later.
I have long believed that the companies best positioned in the next decade will be those that stop treating fixed and mobile as completely separate businesses. SpaceX has a chance to treat them as complementary from the beginning. That mindset alone could prove more valuable than any single spectrum license or site agreement.
Tower Companies Suddenly Look More Strategic
The jump in tower-related stocks this month tells its own story. Investors appear to be reassessing the value of existing site portfolios now that a well-capitalized new player is shopping for access. For the tower firms, a large new tenant is almost always good news. Even if the terms differ from traditional carrier leases, incremental revenue and utilization of existing assets usually help the bottom line.
At the same time, the talks raise longer-term questions. If SpaceX ultimately succeeds in building meaningful market share, will it continue leasing or will it eventually seek more ownership of infrastructure? For now the market seems focused on the near-term positive of new demand. That reaction makes sense, yet seasoned investors know relationships in this industry evolve over many years.
Perhaps the most interesting aspect is how the discussions highlight the scarcity value of well-located sites. Zoning, community opposition, and construction costs have made new tower builds harder in many markets. Existing portfolios therefore carry strategic weight that pure financial models sometimes understate. SpaceX’s interest simply makes that reality more visible.
Risks That Could Still Derail the Ambition
None of this is guaranteed to work smoothly. Regulatory approval for spectrum transfers, local permitting for equipment placement, and the sheer complexity of integrating satellite and terrestrial networks all present hurdles. Customer expectations for mobile service are high. Dropped calls, inconsistent speeds, or complicated billing can quickly erode goodwill even if the underlying technology is impressive.
Capital intensity remains another serious consideration. While SpaceX has demonstrated an ability to raise and deploy large sums efficiently in the launch business, the wireless industry has its own steep learning curve. Maintaining thousands of sites, managing interference, and delivering consistent quality require specialized expertise and ongoing investment. Underestimating those costs has tripped up more than one ambitious entrant in the past.
Competition will not stand still either. The established carriers continue to invest heavily in their own networks and have deep relationships with both consumers and enterprises. They also possess marketing machines and retail footprints that take years to build. SpaceX would need a clear value proposition that goes beyond novelty if it hopes to win meaningful share.
A Possible Path Toward Hybrid Network Leadership
Stepping back, the pieces SpaceX is assembling suggest a hybrid model that could prove difficult for pure-play competitors to match. Satellite provides broad coverage and rapid deployment in remote or underserved areas. Low-band spectrum adds indoor penetration and outdoor mobility. Widespread site access supplies the densification needed in higher-traffic zones. Starlink’s existing customer relationships offer a ready audience that already trusts the brand.
If executed well, the combination might allow SpaceX to serve different customer segments with tailored experiences. Rural households could lean more on the satellite side. Suburban and urban users might rely more on the terrestrial layer while still benefiting from seamless satellite backup. The company would not need to win every urban densification battle to create a profitable and differentiated business.
In my experience following infrastructure stories, the winners are often those who refuse to accept the industry’s traditional boundaries. SpaceX has shown that willingness repeatedly. Whether the same approach succeeds in wireless will depend on execution details that are still taking shape. Yet the early signals are clear enough that Wall Street has started adjusting its models.
What Investors Should Watch in the Coming Months
Several milestones will help clarify how serious and how advanced these plans really are. Formal announcements around site agreements would provide concrete numbers and timelines. Regulatory progress on spectrum transfers will signal whether the low-band foundation is secure. Any early technical trials or limited commercial launches would offer the first real performance data.
Tower company commentary on new tenant discussions will also be worth tracking. Even without naming names, management teams often give directional color on demand trends. Similarly, the traditional carriers’ language around competitive intensity and capital spending priorities may shift if they perceive a credible new threat.
- Concrete site lease announcements or partnership details
- Regulatory milestones related to spectrum ownership
- Early technical demonstrations of hybrid satellite-terrestrial service
- Changes in tower company guidance around tenancy and pricing
- Shifts in carrier messaging about network investment priorities
Each of these items will either reinforce or challenge the narrative currently forming on the Street. Patience will be required. Network builds of this scale do not materialize overnight, and markets sometimes overreact to early headlines before the operational reality sets in.
Broader Implications for the Wireless Landscape
Beyond the immediate stock moves, this episode raises larger questions about how connectivity will be delivered in the next decade. The traditional model of three or four national cellular networks competing primarily on coverage maps and price may gradually give way to more varied architectures. Companies that control both space-based and ground-based assets could offer resilience and reach that pure terrestrial players struggle to match.
At the same time, the economics of dense urban coverage remain challenging for newcomers. Spectrum efficiency, site density, and backhaul all favor operators who already possess scale. SpaceX will need to be selective about where it invests heavily and where it relies more on its satellite advantage. That selectivity could define the ultimate shape of its wireless business.
I keep coming back to the residential foundation. If SpaceX can turn its existing dish customers into multi-product households that also use its mobile service, the customer acquisition cost advantage becomes significant. Loyalty built on reliable home internet could translate into willingness to try the mobile offering, especially if the experience feels integrated rather than bolted on.
Balancing Ambition With Operational Realism
Ambition has never been in short supply at SpaceX. Turning that ambition into consistent, high-quality wireless service will test a different set of muscles. The company has proven it can innovate in hardware, software, and operations at scale. Applying those strengths to the messier world of local zoning boards, interference management, and customer support tickets will require cultural as well as technical adaptation.
Still, the strategic logic is hard to dismiss. Low-band spectrum provides the coverage foundation. Site access multiplies the places that coverage can originate. Existing satellite capacity fills gaps and serves remote users. Residential relationships create a ready market. Put those elements together and a coherent long-term vision begins to emerge.
Whether that vision ultimately disrupts the established order or simply forces the incumbents to raise their game remains uncertain. What is already clear is that Wall Street is treating the possibility seriously. Tower valuations have responded, carrier shares have adjusted, and analysts are refining their frameworks to account for a new kind of competitor.
Looking Ahead With Cautious Optimism
The coming quarters will supply more evidence one way or the other. For now the smartest posture is attentive skepticism. The reports of large-scale site discussions are credible enough and consistent enough with prior spectrum moves to deserve close attention. Yet the gap between announcing intent and delivering a competitive mobile experience is wide, and many promising wireless stories have stalled in that gap before.
From an investor perspective, the situation creates both opportunities and risks across several related sectors. Tower companies stand to benefit from new demand. Spectrum holders may find additional buyers or higher valuations. Traditional carriers face the prospect of a well-funded rival with a different cost structure and technology base. And SpaceX itself must prove it can translate engineering excellence into the everyday reliability mobile customers demand.
I have found that the most durable infrastructure stories are those that solve real customer problems in ways the status quo cannot easily match. If SpaceX can deliver outdoor coverage that feels seamless with its home service, reaches places others ignore, and does so at a competitive price, it may earn a lasting place in the market. The cell site discussions currently underway look like an important step toward testing that proposition at scale.
The wireless industry rarely changes overnight. When it does shift, the catalysts often appear years before the full impact becomes visible. Today’s talks about cell sites and spectrum may eventually be remembered as one of those early signals. Or they may fade into a longer list of ambitious plans that never quite reached critical mass. Either way, the conversation has already forced investors, executives, and observers to reconsider assumptions that had grown comfortable over the past decade. That alone makes the current moment worth following closely.
As more details emerge, the picture will sharpen. Until then, the most useful stance is to keep watching the intersection of satellite capability, terrestrial spectrum, and physical site access. That intersection is where SpaceX appears determined to build its next chapter, and Wall Street has taken notice. The outcome will shape not only one company’s trajectory but also the broader competitive landscape for connectivity in the years ahead.
Wealth is the ability to fully experience life.

AI Data Centers Risk Becoming The Next Fannie Mae Crisis

Tech Earnings Week Guide Alphabet Microsoft Amazon Outlook
Related Articles
Trump’s Ultimatum: Hamas Faces Dire Consequences
Trump gives Hamas a stark deadline to free hostages or face "complete obliteration." Will they comply, or is conflict inevitable? Dive into the high-stakes drama...

Signos Expands Dexcom Partnership in AI Driven Weight Loss Tech
With obesity rates climbing and GLP-1 medications dominating headlines, one health tech startup just secured major funding and a stronger alliance with a medical giant. What does this mean for everyday people trying to lose weight sustainably? The answer might surprise you...

Five Stocks to Buy Ahead of Earnings Season 2026
Analysts are bullish on five stocks heading into earnings season, from a tech giant to energy and infrastructure plays. With AI, upgrades and strategic moves in focus, which ones have the most room to run? Read on for the full breakdown...