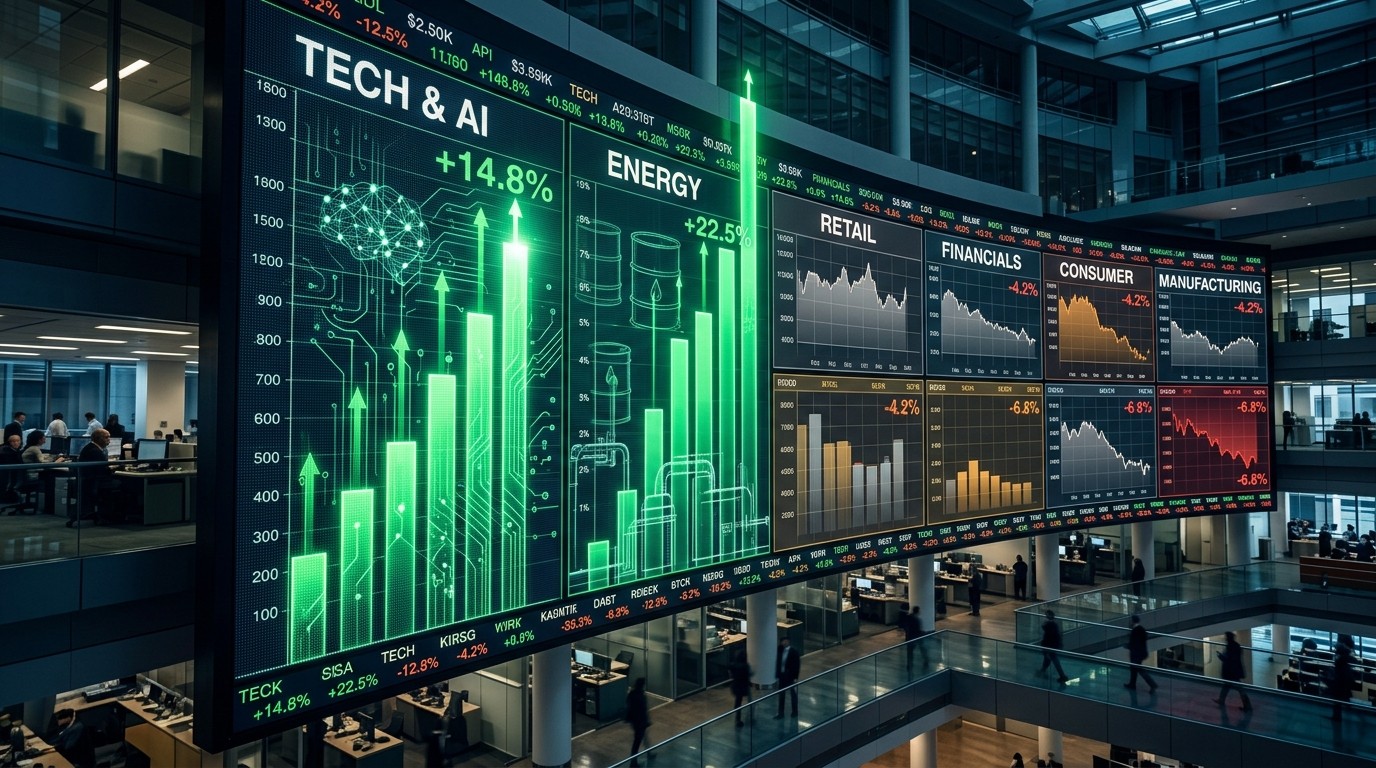

I keep staring at the early numbers coming out of this earnings season and something just does not sit right. On the surface everything looks fantastic. Year-over-year growth for the S&P 500 is tracking close to 30 percent. That kind of figure usually gets people excited. Yet when you peel back the layers you find the bulk of that expansion is coming from only two corners of the market. Tech and energy are carrying the load while almost everyone else is slowing down. It feels a bit like watching a team win because two star players scored all the points and the rest of the roster barely showed up.
Why The Headline Numbers Feel Misleading Right Now
The corporate reporting period has kicked into high gear. Some of the big banks already posted their results. One delivered a rare miss on the bottom line. Another came in mixed. A third beat on earnings but barely cleared the revenue bar. One more posted a solid top and bottom line surprise. Outside the financials, a major health insurer topped estimates and even lifted its full-year outlook. The start has been uneven, no question. Still the overall S&P 500 earnings growth projection remains near that eye-catching 30 percent mark.
Here is the catch I cannot stop thinking about. Most of that growth is expected to arrive from energy and technology. Oil companies are looking at sharp profit jumps because prices have stayed elevated amid ongoing tensions in the Middle East. Tech firms continue to pull in serious cash from the ongoing artificial intelligence buildout. When you strip those two sectors out, the picture changes fast. Growth for the rest of the index is forecast to slow to around 7 percent in the third quarter after sitting at 12 percent the previous quarter. That is a meaningful deceleration.
In my experience this kind of concentration rarely lasts forever without consequences. Investors have already noticed the performance gap. Tech has climbed roughly 36 percent so far this year. Energy has done even better, jumping about 49 percent. Those gains make sense given the earnings power on display. But the expectations baked into the stocks have grown equally ambitious. Chipmakers are projected to deliver something like 130 percent earnings growth. Energy names are looking at around 122 percent. Those are enormous numbers. If either group falls short while the broader market keeps slowing, pressure could build quickly across indexes.
The Real Story Behind The AI Capex Wave
Artificial intelligence spending has been the single biggest narrative driving tech profits. Companies are pouring capital into data centers, specialized chips, and the supporting infrastructure. That investment cycle has been remarkably smooth so far. Revenue has followed. Margins in many cases have held up better than some skeptics expected. Yet the durability of this cycle is now the open question. A higher cost of capital could start to matter. Geopolitical bottlenecks might appear. Supply chains for critical components are not infinite.
I have found that markets often underestimate the interplay between rates, geopolitics, and technology spending until something actually breaks. Right now the story still looks clean. Monetization of AI tools is happening, though the pace varies widely from one company to the next. Some firms are already showing clear returns on their investments. Others are still in the heavy spending phase with the payoff expected later. The risk is that any stumble in either the spending or the monetization side could ripple outward fast because so much of the index-level growth depends on this one theme.
Index earnings remain highly dependent on the durability of the AI capital expenditure cycle and successful monetization. The interplay between geopolitics, interest rates, and tech may still be underestimated.
That observation feels especially relevant right now. A higher cost of capital does not have to stop the cycle cold, but it can slow the pace of new projects. Geopolitical friction can create sudden shortages or force expensive workarounds. Neither of those scenarios is priced as a high probability at the moment. That is precisely why the concentration risk deserves more attention than it is getting.
Energy Profits Riding Geopolitical Winds
Energy is the other major engine. Elevated oil prices linked to conflict in the Middle East have lifted earnings expectations dramatically. Companies in the sector are expected to report sharp year-over-year profit increases. The performance of energy stocks this year already reflects that optimism. A nearly 50 percent advance is hard to ignore. Yet commodity-driven earnings are inherently less predictable than software or semiconductor results. Prices can move quickly on new developments, and those moves do not always stay in one direction.
Perhaps the most interesting aspect is how little room for error currently exists in the consensus forecasts. When a sector is priced for 122 percent growth, even a solid but slightly softer number can trigger a sharp reaction. Combine that possibility with slowing growth elsewhere and the overall market becomes more vulnerable to disappointment. I keep coming back to the idea that the current setup rewards concentration more than diversification. That can work for a while. It rarely works indefinitely.
What Slowing Growth Outside Tech And Energy Really Means
Look past the two star sectors and the numbers get more sobering. The rest of the S&P 500 is expected to grow earnings at roughly half the pace of the previous quarter. That slowdown is not confined to one or two industries. It appears more widespread. Consumer-related companies, industrials, and parts of healthcare are all showing more modest expansion. Some are even looking at flat or slightly negative comparisons once you adjust for one-time items.
This matters because market indexes are capitalization-weighted. When a handful of large names deliver outsized growth they can pull the entire average higher even while the median company struggles. The reverse is also true. If those large names ever miss, the average can fall harder than the typical stock. Right now the market is leaning heavily on that concentration. Investors who focus only on the headline growth rate risk missing the underlying fragility.
- Tech and energy are expected to drive the vast majority of S&P 500 earnings expansion this quarter
- Growth excluding those two sectors is projected to slow from 12 percent to around 7 percent
- Chipmakers face forecasts of roughly 130 percent year-over-year earnings growth
- Energy companies are looking at approximately 122 percent growth
- Any shortfall in either group could put broader index pressure on the table
Those points are not meant to sound alarmist. They simply describe the current arithmetic. The market can continue to climb on the strength of a few sectors for longer than most people expect. History shows that. At the same time, history also shows that extreme concentration eventually creates its own vulnerabilities. I prefer to keep both realities in view rather than leaning too hard on either one.
How Elevated Expectations Change The Risk Profile
Expectations have a way of becoming their own risk factor. When the bar is set this high, beating it becomes harder and missing it becomes more painful. Chipmakers and energy producers are not just expected to grow. They are expected to grow at rates that leave little margin for ordinary operational hiccups. Supply chain delays, higher input costs, or simply a pause in customer spending can quickly turn a strong quarter into a disappointment relative to those lofty forecasts.
In my view the more interesting question is not whether tech and energy will continue to report solid numbers. Most of them probably will. The question is whether those numbers will be solid enough relative to what is already priced in. Markets care about the difference between results and expectations far more than they care about absolute levels. That gap is where volatility often starts.
Consider the AI capital expenditure cycle again. It has been smooth. Spending has translated into revenue for the key suppliers. Yet any sign that the next wave of projects is being delayed or scaled back could shift sentiment quickly. The same is true on the energy side. A sudden easing of geopolitical tensions that brings oil prices lower would immediately pressure the growth rates currently embedded in forecasts. Neither scenario is the base case right now. Both remain possible.
The Quiet Slowdown In The Broader Market
While the spotlight stays on the two booming sectors, the rest of the market is dealing with a different reality. Demand in some traditional industries has moderated. Cost pressures have not fully disappeared. Pricing power is less uniform than it was a couple of years ago. The result is that earnings growth outside tech and energy has cooled. That cooling is visible in the sequential slowdown from 12 percent to the projected 7 percent.
I have noticed that this kind of divergence often lasts longer than the average investor expects. Momentum can keep the leaders leading and the laggards lagging. Portfolio construction becomes trickier in that environment. Owning only the winners feels comfortable until the moment it stops working. Spreading exposure more evenly can feel like leaving performance on the table. There is no perfect answer, only trade-offs.
One practical way to think about it is to watch the breadth of earnings growth rather than the average. When a larger share of companies is participating in the expansion, the foundation tends to be more stable. When participation narrows, the foundation becomes more dependent on the continued success of fewer names. Right now participation is relatively narrow. That is the key trend the headline numbers are masking.
What Could Shift The Current Dynamic
Several factors could change the picture over the coming quarters. A sustained drop in oil prices would reduce the energy contribution. Any meaningful delay in AI-related capital spending would hit the tech contribution. On the positive side, a reacceleration in broader economic activity could lift growth outside the two star sectors and reduce the concentration risk. Interest rate moves will matter as well. Lower rates generally support higher valuations and can encourage more capital investment. Higher rates do the opposite.
Geopolitics remains the wild card. The same tensions that have supported oil prices also create uncertainty for global supply chains. Technology companies rely on complex international networks for manufacturing and materials. Any escalation that disrupts those networks would affect both the energy and tech stories at the same time. That dual exposure is worth keeping in mind.
- Monitor sequential changes in earnings growth excluding tech and energy
- Track actual AI capital expenditure trends versus earlier guidance
- Watch oil price movements and their direct impact on energy forecasts
- Pay attention to any shift in the cost of capital for large projects
- Observe whether more sectors begin to participate in earnings expansion
These are not complicated steps. They simply require looking past the headline index growth rate and focusing on the composition of that growth. The composition is where the real information sits right now.
A More Balanced View Of The Current Setup
None of this means the market is on the verge of a major downturn. Strong profits in two large sectors are still strong profits. They support valuations and provide real cash flow. The point is simply that the quality of the growth matters as much as the quantity. Growth that is highly concentrated carries different risks than growth that is broadly distributed. Investors who understand that distinction are better positioned to adjust when conditions eventually change.
I tend to favor a posture that respects the current momentum while remaining alert to the underlying narrowness. That means giving the leaders room to run without assuming the rest of the market will automatically catch up. It also means watching the expectations gap carefully. When forecasts become extreme, even good news can sometimes fail to move stocks higher because the good news was already assumed.
The earnings season still has a long way to go. Many important companies have not yet reported. The early indications, however, already highlight the disparity. Tech and energy are doing the heavy lifting. Everyone else is contributing less than they did a quarter ago. That is the key trend the impressive headline growth rate is currently masking. How long that pattern continues will shape the market’s path more than most of the daily noise.
Practical Implications For Portfolio Thinking
From a portfolio perspective the current environment rewards selective exposure. Owning the companies that are actually delivering the growth makes sense. At the same time, maintaining some ballast outside those areas can reduce the impact if the leaders ever stumble. The exact mix depends on individual time horizons and risk tolerance. There is no universal formula.
One approach that has worked for me in similar periods is to size positions according to the durability of the earnings drivers rather than pure momentum. AI-related capital spending has clear momentum, yet its long-term durability still depends on successful monetization and manageable costs of capital. Energy profits tied to elevated commodity prices have a different set of drivers and a different set of risks. Treating them as separate decisions rather than a single “growth” bucket can improve clarity.
It also helps to remember that markets can stay concentrated longer than many expect. Fighting the prevailing trend purely on valuation or concentration grounds has been a costly strategy more often than not. Respecting the trend while preparing for eventual broadening or rotation tends to produce better outcomes over full cycles.
Looking Ahead To The Rest Of The Season
As more companies report, the picture will sharpen. We will learn whether the projected 7 percent growth outside tech and energy holds up or deteriorates further. We will see whether the AI spending plans remain intact or begin to show signs of caution. We will also get clearer data on how energy companies are converting elevated prices into actual free cash flow and shareholder returns.
Those details will matter more than any single beat or miss. The market is already aware that tech and energy are strong. What it is still discovering is how much of the overall growth depends on that strength continuing at the currently expected pace. Any deviation from that path will likely produce larger price reactions than similar deviations would in a more balanced growth environment.
For now the numbers still look good at the index level. The composition of those numbers tells a more nuanced story. Paying attention to both is the difference between riding the current wave and understanding where the vulnerabilities might eventually appear. That understanding will not eliminate risk, but it can keep surprises from becoming complete shocks.
The coming weeks will test how durable the current concentration really is. If tech and energy continue to deliver against elevated expectations while the rest of the market stabilizes, the headline growth can remain impressive. If either of those conditions fails to hold, the masking effect will fade and the slower underlying trend will become harder to ignore. Either outcome is possible. Preparing for both seems like the more practical stance.
I will be watching the sequential trends outside the two big sectors as closely as the absolute results from the leaders. That is where the quieter signal sits. And right now that quieter signal is the one most worth hearing.