
Have you noticed how quickly the rules of global money movement keep shifting these days? One moment foreign firms face high walls in certain markets, the next they receive careful openings that change the entire landscape. That is exactly the feeling I got when news broke about Tencent and Visa deciding to broaden their long-running cooperation right after a string of fresh regulatory nods in China. It is not just another memorandum of understanding. It feels like a quiet but meaningful signal that parts of the world’s second-largest economy are becoming more accessible again for selected international players.
Why This Expanded Partnership Matters Right Now
In my view the timing could hardly be more interesting. After years of cautious steps, both companies have chosen this particular window to push harder on cross-border payments, international money transfers and even emerging forms of AI-driven shopping. The agreement lands just as Visa itself received permission to start preparing a domestic bank card clearing operation and another major American institution secured approval for a fully owned securities business. Taken together these moves paint a picture of gradual, selective opening rather than sudden transformation.
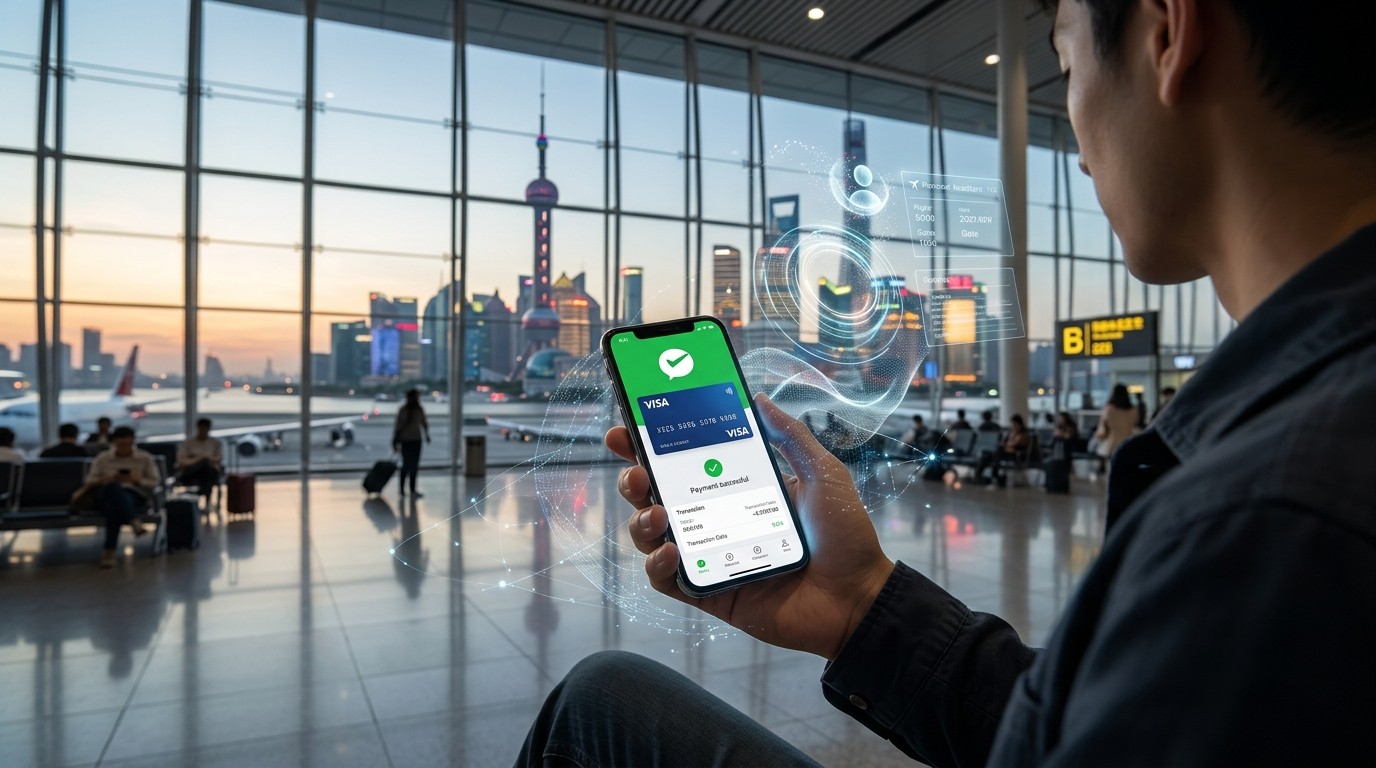
Travelers heading into or out of China stand to notice the difference first. The two firms plan to explore smoother ways for visitors to pay at participating merchants by linking Tencent’s Weixin Pay ecosystem with Visa’s global network. Subject to all the usual regulatory checks, of course. They also want to make it simpler for people overseas to send funds straight into Weixin Pay accounts through Visa Direct. These are practical improvements that address real friction points many of us have experienced when trying to move money across borders.
A Partnership That Already Had History
This is not a brand-new relationship. Cooperation between the two has been visible since at least 2019, when arrangements first allowed international Visa cardholders to settle payments through WeChat Pay while inside China. What we see now is a clear deepening of that earlier foundation. Instead of stopping at basic acceptance, the latest memorandum of understanding reaches into money transfers, AI-powered commerce experiences and traveler-friendly payment flows.
Dowson Tong, who leads Tencent’s Cloud and Smart Industries Group, framed the collaboration as a chance to combine the company’s artificial intelligence strengths with Visa’s worldwide reach. The goal, as he put it, is to create more seamless commerce experiences for consumers and fresh opportunities for businesses both inside China and beyond its borders. That language feels measured yet optimistic, which matches the careful tone that usually accompanies these kinds of announcements.
We hope to create more seamless commerce experiences for consumers and new opportunities for businesses, both in China and internationally.
I find that statement particularly revealing because it places equal weight on domestic and international benefits. Many earlier partnerships focused mainly on helping foreign visitors spend inside China. This one looks outward as well, aiming to help Chinese users and overseas recipients interact more easily through the same networks.
The Regulatory Backdrop That Made It Possible
None of this happens in isolation. Earlier this month Visa received approval from China’s central bank to begin preparations for a domestic bank card clearing business. That single green light brings the company closer to participating more fully in the local payments market after more than four decades of presence in the country. At the same time another major American financial group obtained permission to set up a wholly owned securities venture based in Shanghai. The new entity is expected to offer equities brokerage, underwriting, research and principal trading once remaining procedures are completed.
These approvals arrive against a broader backdrop of selective market opening. Conversations between senior officials from both sides earlier this year reportedly touched on access questions for several large payment and financial firms. The latest decisions appear consistent with that gradual approach rather than a sudden policy shift. From where I sit, the message seems clear: certain carefully chosen doors are opening a little wider, provided the applicants meet the required standards and demonstrate long-term commitment.
Practical Benefits for Everyday Users
Let’s talk about what this could mean for ordinary people. Imagine landing in a Chinese city after a long flight and discovering that paying at a local restaurant or store no longer requires juggling multiple apps or hunting for cash. If the planned merchant solutions materialize, a traveler holding a Visa card could complete the transaction through the Weixin Pay interface more smoothly than before. That kind of friction reduction matters more than most of us admit until we are standing at a counter trying to settle a bill.
On the other side of the equation, someone living outside China who wants to send money to a relative or friend using Weixin Pay may find the process less cumbersome. Expanding the use of Visa Direct in this direction aims to shorten the chain of steps involved in international transfers. Anyone who has ever waited days for funds to clear or paid multiple intermediate fees will appreciate even modest improvements here.
- Smoother payment options for inbound and outbound travelers
- Easier inbound money transfers into the Weixin Pay ecosystem
- Potential reduction in friction for cross-border merchant acceptance
- Foundation for more advanced AI-assisted shopping experiences
These are not abstract benefits. They address daily pain points that frequent travelers and diaspora communities encounter regularly. In my experience, the companies that succeed in this space are the ones that solve those small but persistent annoyances rather than chasing flashy headlines alone.
The Rise of Agentic Commerce
Perhaps the most forward-looking part of the announcement involves what the companies call agentic commerce. This refers to an emerging style of online shopping in which artificial intelligence agents help consumers discover, evaluate and purchase products or services with less manual effort. Instead of scrolling endlessly through pages, a user might simply describe a need and let an AI agent handle the comparison and transaction steps within certain guardrails.
Combining Tencent’s AI capabilities with Visa’s global payment rails could, in theory, make those agent-driven purchases work more reliably across borders. Think about an AI assistant that not only finds the right product but also settles the payment securely whether the buyer and seller sit in different countries. We are still in the early stages of this technology, yet the partnership signals that both firms want a seat at the table as the model develops.
I remain cautiously optimistic about how quickly agentic commerce will move from demonstration to everyday use. Technical challenges around trust, liability and regulatory compliance remain substantial. Still, the fact that a major technology platform and a leading payments network are exploring the space together suggests the conversation is advancing beyond pure theory.
How This Fits Into Broader Financial Opening
Looking at the bigger picture, the Tencent-Visa expansion sits alongside other recent steps that expand foreign participation in Chinese financial markets. The securities approval granted to another large American institution is a useful parallel. That venture will focus on brokerage, underwriting, research and trading services for both domestic and international clients once it becomes operational. Together these developments illustrate a pattern of controlled, case-by-case access rather than blanket liberalization.
For global companies the message is mixed but not discouraging. Progress is possible when firms demonstrate patience, local partnerships and willingness to meet regulatory requirements. Visa’s long presence in the country, spanning more than forty years, likely played a role in building the trust needed for the latest clearing preparation approval. Tencent’s deep domestic footprint supplies the local expertise and user base that make the cooperation commercially attractive.
It is worth remembering that China already operates sophisticated domestic payment systems used by hundreds of millions of people every day. Any foreign entrant must find ways to complement rather than simply compete with those systems. The current partnership model—linking global card networks with established local platforms—appears designed precisely for that complementary role.
Potential Implications for Businesses
Merchants stand to gain as well. Businesses that attract international visitors or sell to overseas customers may eventually benefit from more flexible payment acceptance options. A restaurant or hotel that can reliably take both domestic mobile payments and international cards through a more integrated interface reduces the chance of lost sales. E-commerce sellers who deal with cross-border buyers could see similar advantages if agentic tools and streamlined transfers take hold.
Of course nothing happens overnight. Regulatory requirements still apply to every new solution the companies develop. Implementation will require technical work, testing and ongoing compliance. Yet the direction of travel is clearer than it was a few years ago. Firms that prepare for smoother cross-border payment flows may find themselves better positioned when those flows become routine.
| Area of Focus | Current Status | Potential Near-Term Impact |
| Traveler Payments | Exploring integrated solutions | Reduced friction at participating merchants |
| Money Transfers | Expanding Visa Direct links | Faster inbound funds to Weixin Pay |
| AI Commerce | Early collaboration stage | Foundation for agent-assisted purchases |
| Domestic Clearing | Preparation approval received | Closer participation in local card market |
That simple overview helps clarify where the most immediate activity is likely to appear. Travelers and transfer users may notice changes first, while deeper AI applications will take longer to mature.
Looking at Parallel Moves by Other Players
Tencent has not limited itself to a single international partner. Late last year its international payments platform worked with another major card network to integrate click-to-pay technology and enhanced security features into overseas solutions. The aim there was faster and safer online transactions for users outside China. These parallel efforts show a consistent strategy: connect local strengths with global networks wherever regulatory space allows.
From an observer’s perspective this multi-partner approach makes sense. No single network covers every market or every use case equally well. By working with several global players, Tencent can offer more complete coverage while still keeping its own ecosystem at the center of the user experience. Visa, for its part, gains deeper access to a vast user base and the opportunity to test new service models in a high-volume environment.
I’ve found that the most durable cross-border arrangements tend to follow this pattern of mutual complementarity rather than zero-sum competition. Each side brings something the other cannot easily replicate on its own.
Challenges That Still Lie Ahead
It would be unrealistic to pretend the path forward is completely smooth. Regulatory scrutiny remains high, and any new product or service must clear multiple review stages. Technical integration between different payment rails always carries complexity, especially when real-time settlement and fraud prevention are involved. Consumer trust in AI-driven purchasing will also need careful cultivation. People want convenience, yet they also want clear control over what an automated agent can spend on their behalf.
Currency controls, data localization rules and varying consumer protection standards across jurisdictions add further layers of complexity. Companies operating in this space must navigate those differences continuously. The fact that both Tencent and Visa have chosen to move forward suggests they believe the remaining obstacles are manageable within the current policy environment.
One personal observation: partnerships of this kind often succeed or stall based on execution quality rather than the initial announcement. The memorandum of understanding sets direction, but the real test comes when actual products reach users and perform reliably under everyday conditions.
What Travelers and Businesses Should Watch
For frequent travelers the practical advice is simple. Keep an eye on announcements about pilot programs or expanded merchant acceptance in major Chinese cities. Early implementations often begin in high-traffic locations such as airports, hotels and popular shopping districts before spreading more widely. Anyone who regularly sends money to contacts in China may want to monitor updates on Visa Direct capabilities linked to Weixin Pay accounts.
Businesses that serve international customers should review their current payment acceptance mix. Adding more seamless options for both domestic mobile wallets and international cards can reduce abandoned transactions. Those exploring AI-assisted sales tools might find the emerging agentic commerce conversation relevant as the technology matures.
- Monitor pilot launches for traveler payment solutions
- Review existing cross-border transfer options for cost and speed
- Assess readiness for potential AI-assisted commerce features
- Stay informed about broader regulatory developments affecting foreign financial firms
These steps require little immediate investment yet position individuals and companies to respond quickly when concrete services become available.
Longer-Term Perspectives on Market Access
Stepping back further, the latest developments form part of a longer conversation about how open Chinese financial markets will become to foreign participants. Progress has been uneven over the years, with periods of greater openness followed by tighter controls and then selective easing again. The current phase appears to favor firms that already maintain substantial local relationships and can demonstrate clear value for Chinese consumers and businesses.
Visa’s preparation approval for domestic clearing represents one of the more significant steps in recent memory for a foreign card network. Combined with the securities venture approval granted to another institution, it suggests authorities are willing to allow deeper participation in carefully defined areas. Whether this pattern continues will depend on many factors, including overall economic conditions, bilateral relations and the performance of the newly authorized entities.
In my experience watching these markets, the firms that treat market access as a multi-decade commitment rather than a short-term opportunity tend to navigate the cycles more successfully. Both Tencent and Visa have already demonstrated that kind of staying power.
The Human Side of Cross-Border Money
Behind all the corporate language and regulatory details sits a simple human reality. People want to pay for things without unnecessary hassle, send money to family without excessive fees or delays, and explore new products with reasonable confidence that the transaction will complete smoothly. Every technical partnership and policy approval ultimately succeeds or fails based on how well it serves those everyday needs.
When I travel I still notice the small moments of friction that good payment design can remove. Standing at a counter while the merchant and I both fumble with different systems is never pleasant. Watching funds take three or four days to reach a relative feels unnecessarily slow in an age of instant messaging. The current collaboration aims, at least in part, at shrinking those moments of friction. That goal is worth supporting even if full realization takes time.
Agentic commerce raises similar human questions. Will people feel comfortable letting an AI agent complete purchases on their behalf? How much oversight will users demand? The answers will shape how quickly the technology moves from laboratory interest to mainstream habit. Partnerships that combine strong payment security with thoughtful AI design stand a better chance of earning that trust.
Putting the Pieces Together
Taken as a whole, the expanded Tencent-Visa understanding, the domestic clearing preparation approval and the parallel securities venture green light form a coherent set of signals. Certain parts of China’s financial sector are becoming more accessible to established foreign firms that meet regulatory standards and work through local partnerships. The focus on practical user benefits—smoother traveler payments, easier money transfers and early exploration of AI-assisted commerce—gives the announcements real substance beyond pure corporate positioning.
None of this guarantees rapid transformation. Implementation will take time, regulatory reviews will continue, and user adoption will depend on actual performance. Yet the direction feels more constructive than it has in some previous periods. For anyone who follows global payments, cross-border commerce or the gradual evolution of market access rules, these developments deserve close attention.
I plan to watch how the first concrete products emerge from the memorandum of understanding. Early traveler payment pilots and any expansion of Visa Direct capabilities into the Weixin Pay ecosystem will offer the clearest evidence of progress. The agentic commerce work may take longer to surface in consumer-facing form, but even preliminary demonstrations would indicate seriousness about the longer-term opportunity.
In the end the story is less about any single announcement and more about the steady accumulation of small openings that, over time, can change how money and commerce flow between China and the rest of the world. That process remains incomplete and subject to many variables. Still, the latest chapter written by Tencent, Visa and the relevant regulators feels like a meaningful step rather than mere rhetoric. For travelers, businesses and anyone who cares about practical improvements in cross-border finance, that is news worth following.
The coming months will reveal how quickly these plans move from signed papers to working services. Until then the most useful stance is attentive optimism—recognizing the progress while remaining clear-eyed about the work still required. In a sector where trust and reliability matter more than flashy promises, that measured approach seems the only sensible one.