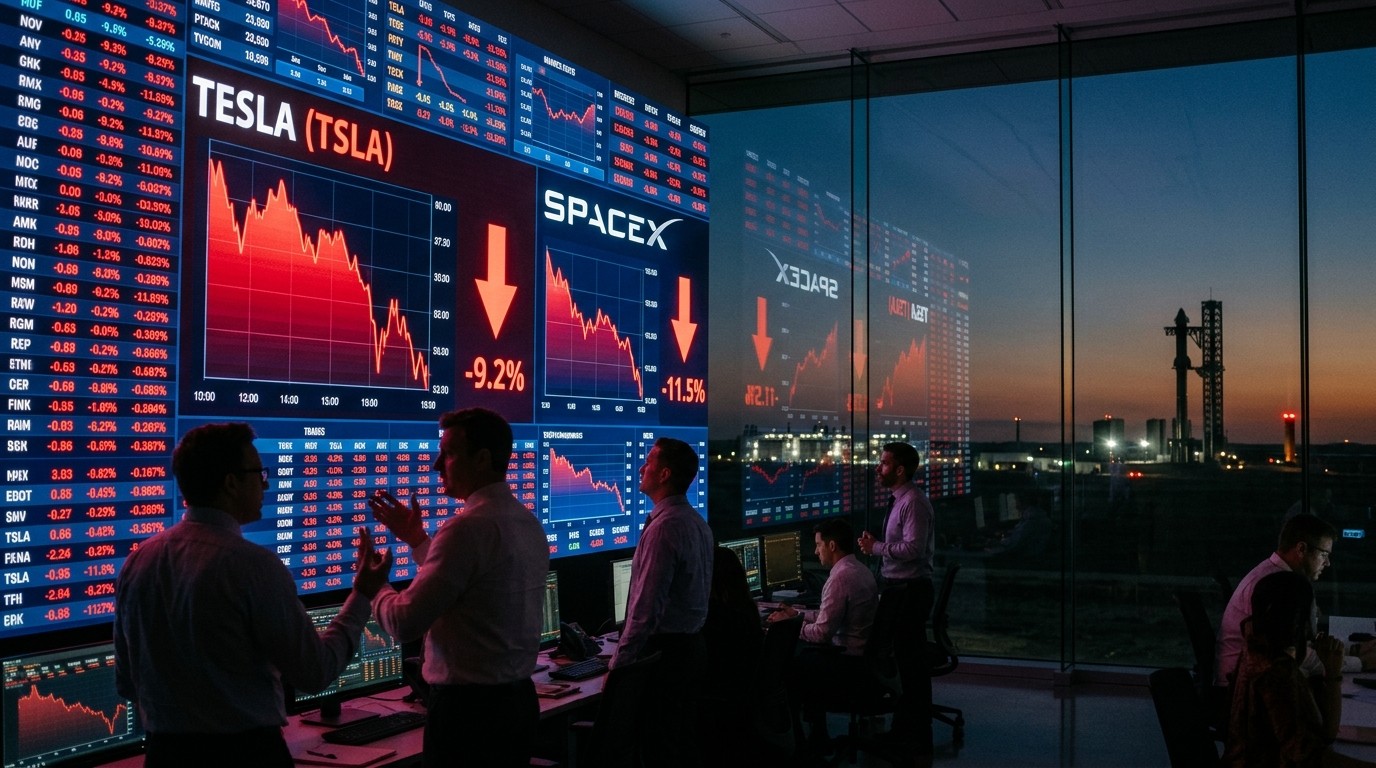

Watching nearly half a trillion dollars vanish from two of the most closely followed companies in the world in just a couple of trading sessions feels surreal. Yet that is exactly what unfolded after the 2026 midterms. Tesla and SpaceX together shed more than $420 billion in market value as investors quickly recalibrated their expectations around regulation, political influence, and the future of large-scale AI infrastructure projects.
The speed of the move caught many off guard. Shares of Tesla dropped roughly 9 percent while SpaceX declined about 11 percent on the day, continuing a slide that began right after the election results became clear. What started as a broad tech sell-off quickly took on a more specific narrative centered on one high-profile executive and the shifting balance of power in Washington and Texas.
How Political Results Triggered A Rapid Repricing
Investors rarely react this forcefully to midterm outcomes unless they believe the policy environment is about to change in meaningful ways. In this case, the combination of Democratic control of both chambers of Congress and a notable shift in Texas created exactly that perception. Suddenly the regulatory path for ambitious AI and aerospace plans looked steeper, and the possibility of closer congressional scrutiny felt more concrete.
I’ve followed these stocks long enough to know that political risk often sits in the background until an election forces it into the foreground. This time the signal was loud. Market participants began pricing in higher compliance costs, potential delays to major capital projects, and a less favorable climate for any large corporate combination involving the two companies.
The Scale Of The Market Cap Loss
Losing over $420 billion in combined value within two days is not a routine fluctuation. It reflects a genuine reassessment of risk rather than simple profit-taking. Tesla’s valuation has always carried a premium tied to growth expectations in autonomy, energy, and robotics. SpaceX’s private valuation, recently elevated after its public listing, rested heavily on the assumption of continued regulatory support for satellite constellations, launch cadence, and massive compute builds.
When those assumptions came under pressure, the adjustment was swift. The broader technology sector moved lower as well, but the magnitude of the declines in these two names stood out. Liquidity remained solid, yet the tone of trading suggested institutions were reducing exposure rather than adding on weakness.
Wealth Impact And Broader Sentiment
The personal fortune of the chief executive of both companies also moved sharply lower. After reaching the trillion-dollar mark earlier in the year following SpaceX’s public debut, the figure has now slipped below $800 billion. A drop of roughly $90 billion in a single week is eye-catching even by the standards of the ultra-wealthy. Still, the individual remains the richest person on the planet, which says something about the concentration of value in these enterprises.
What matters more for ordinary investors is the signal this sends about risk appetite. When high-profile growth names take this kind of hit, portfolio managers often reassess other holdings that share similar regulatory or political exposure. That secondary effect can linger longer than the initial price move.
Political Backing And Election Outcomes
One element that intensified the market reaction was the scale of political support provided by the executive. Contributions exceeding $470 million made him the largest individual backer of Republican candidates and causes during the cycle. Most of those candidates did not prevail. The contrast between the size of the financial commitment and the eventual results amplified the sense that influence had limits.
In Texas, the outcome carried extra weight. Both companies maintain major operations and ambitious expansion plans in the state. The new governor-elect and senator-elect defeated long-standing allies, raising the possibility of a different approach to economic development incentives, environmental permitting, and local control over large industrial projects.
While policy is naturally hard to predict, we could envision SpaceX facing some incremental headwinds in this type of backdrop.
That measured observation from a major bank research note captured the cautious mood that settled over the market. Analysts were not forecasting catastrophe, yet they clearly saw a higher probability of friction.
Texas Data Center Ambitions Under Review
Perhaps the most immediate operational concern involves the massive AI infrastructure projects both companies have outlined in Texas. Plans for a large facility known as Terafab in Grimes County would combine a data center with an extensive semiconductor manufacturing operation. SpaceX has also signaled intentions to develop significant compute capacity at its Starbase site.
The incoming state leadership has made data centers a campaign priority. Calls for a temporary pause on new approvals until stronger rules address water consumption, electricity pricing, local authority, and incentive structures have already circulated. For companies racing to secure power and land for AI training clusters, any delay carries real cost.
In my view, the market is correctly treating these projects as sensitive to state-level politics. Capital expenditure plans may need revision. Power purchase agreements and permitting timelines could stretch. None of this is fatal, but the friction raises the bar for execution and could pressure margins or timelines that investors had previously taken for granted.
Regulatory Scrutiny Beyond Texas
Federal dynamics add another layer. With Democrats controlling both the House and Senate, the likelihood of formal inquiries has risen. One area already drawing attention involves restrictions placed on a military version of the Starlink satellite service during the conflict in Ukraine. Preservation of records has been requested, according to reports citing congressional staff.
Separately, any discussion of combining SpaceX and Tesla faces a more complicated path. The idea has been floated publicly, with the important caveat that shareholder approval would be required. Under a different regulatory climate, antitrust and national-security reviews could become more probing. Investors appear to be discounting the probability of a smooth combination in the near term.
These developments do not occur in isolation. They interact with ongoing debates about the role of large technology platforms in critical infrastructure, the allocation of spectrum, and the environmental footprint of energy-intensive AI facilities. The midterm results simply accelerated the timeline for those conversations.
Broader Technology Sector Context
It would be misleading to claim the declines were entirely company-specific. A wider technology sell-off provided the backdrop. Higher interest-rate expectations, rotation out of growth names, and general post-election volatility all played roles. Still, the relative underperformance of Tesla and SpaceX suggests investors layered additional risk premia on top of the sector move.
Liquidity in both names remained healthy, which is typical for high-profile equities. What changed was the narrative. Growth stories that once traded primarily on technological progress and operational execution now carry a heavier political discount. That shift can persist even after the initial price adjustment fades.
What Investors Are Weighing Next
Several questions now dominate discussions among portfolio managers. How quickly will state-level permitting rules evolve? Will federal oversight translate into formal investigations or simply heightened monitoring? Can the companies adapt their capital plans without sacrificing competitive positioning in AI and space?
I’ve found that markets often overreact in the first few sessions after a political surprise and then settle into a more measured assessment. The current environment feels consistent with that pattern. The initial $420 billion reduction in value may prove excessive if practical obstacles turn out milder than feared. Conversely, if concrete delays or inquiries materialize, further pressure remains possible.
- Monitor Texas legislative sessions for data-center policy language
- Watch for any formal congressional requests related to satellite operations
- Track updates on large capital projects and power agreements
- Assess management commentary on regulatory engagement during upcoming earnings
- Compare relative performance against other high-growth technology names
None of these items will resolve overnight. The coming months will reveal whether the political shift produces material operational friction or remains largely a sentiment story.
Longer-Term Strategic Implications
Stepping back, the episode highlights a broader reality for companies that operate at the intersection of advanced technology, national infrastructure, and public policy. Scale brings visibility, and visibility brings scrutiny. When one individual sits at the center of multiple high-profile enterprises and also participates actively in electoral politics, the market eventually prices that concentration of risk.
Both Tesla and SpaceX have demonstrated remarkable operational resilience in the past. Vehicle production ramps, launch cadence improvements, and satellite constellation growth have repeatedly surprised skeptics. That track record provides a foundation. Yet the regulatory and political environment has become a more important variable in the valuation equation than it was even a year ago.
For long-term holders the key question is whether the companies can navigate the new landscape while continuing to execute on their core technological roadmaps. For shorter-term traders the focus remains on near-term catalysts and the possibility of further volatility as policy details emerge.
Investor Positioning And Risk Management
In practical terms, many professional investors are reviewing position sizes and hedging strategies. Concentrated exposure to a single executive’s political fortunes is now harder to ignore. Diversification across the broader technology and industrial complex has gained appeal for some. Others see the sell-off as an opportunity to accumulate shares of companies they still believe possess durable competitive advantages.
There is no single correct response. Risk tolerance, time horizon, and existing portfolio construction all influence the decision. What has changed is the set of factors that must be monitored. Political and regulatory developments now sit alongside production numbers, launch schedules, and AI model progress on the list of material variables.
Perhaps the most interesting aspect is how quickly the market absorbed the new information. Two sessions were enough to reprice hundreds of billions of dollars of equity value. That efficiency is a reminder of how sensitive modern markets have become to shifts in the policy environment surrounding transformative technologies.
Looking Ahead With Measured Expectations
The coming weeks and months will test whether the initial reaction proves justified. Concrete policy proposals in Texas, the tone of any congressional activity, and management’s ability to communicate a clear path through potential obstacles will all matter. Equity prices will continue to adjust as those pieces of information arrive.
For now the story remains fluid. Tesla and SpaceX retain substantial technological and operational strengths. Their valuations, however, have begun to incorporate a more complex political and regulatory overlay. Investors who understand both the promise of the underlying businesses and the new sources of friction are better positioned to navigate the period ahead.
Markets rarely move in straight lines after political surprises. The sharp decline that followed the 2026 midterms has already rewritten near-term expectations. The longer-term trajectory will depend on how skillfully the companies adapt to a landscape that suddenly looks less predictable than it did only a few days earlier.
In the end, this episode serves as a case study in the growing intersection of technology, capital markets, and politics. The numbers are large, the personalities are prominent, and the stakes for both companies and their investors remain high. Watching how the next chapter unfolds should prove instructive for anyone following growth equities in an increasingly politicized environment.
The $420 billion reduction in combined market value stands as a clear marker of changed sentiment. Whether it marks the beginning of a more sustained period of pressure or simply a short-term overreaction will become clearer with time. Until then, caution and careful monitoring of policy developments appear warranted.
One final observation: companies that operate at this scale rarely escape the consequences of political realignments for long. The midterm results simply made those consequences visible faster than many expected. The market has delivered its initial verdict. The companies now have the opportunity to respond through execution, engagement, and adaptation.
That response, more than any single election outcome, will ultimately determine how investors value Tesla and SpaceX in the months and years ahead. The current price action has set a new baseline. Building from it will require navigating both technological ambition and the practical realities of a shifted political map.