

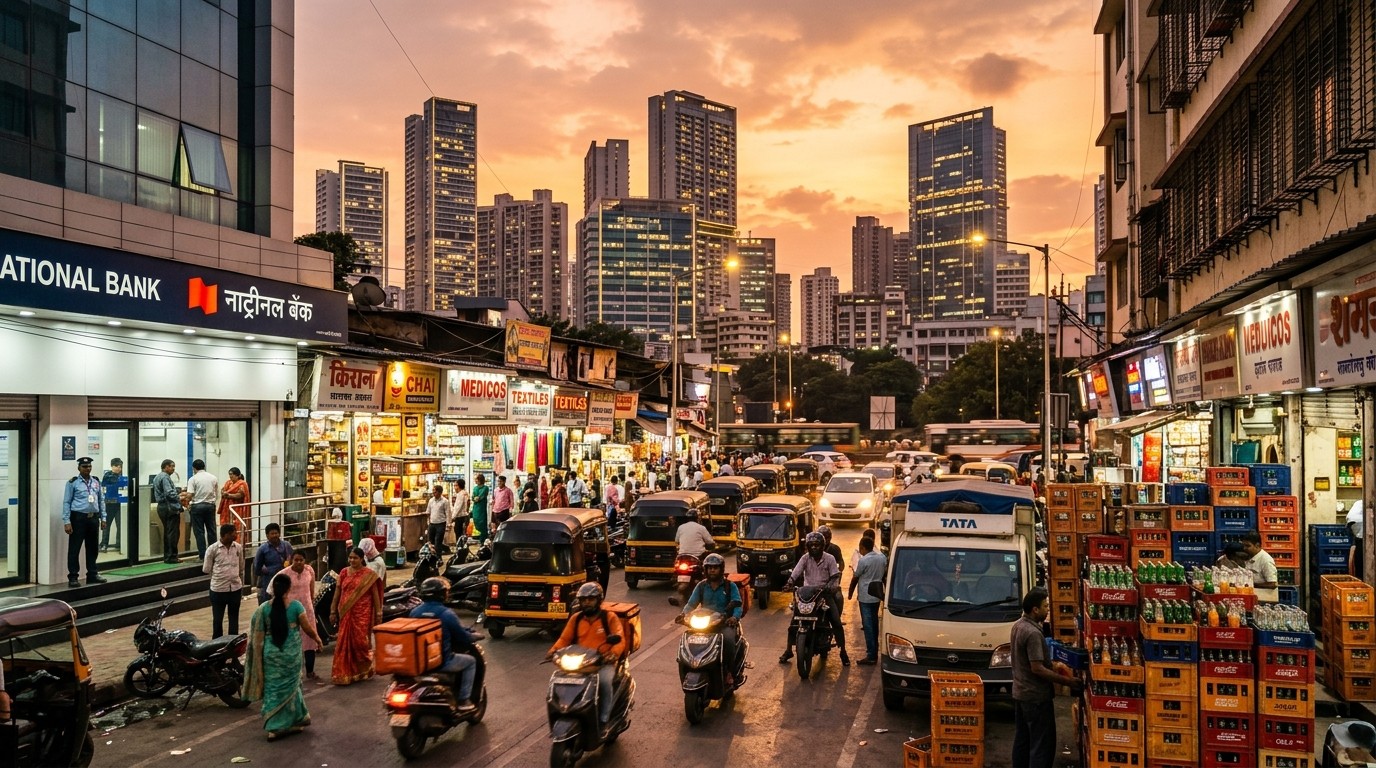

Have you noticed how quickly a market that looked unstoppable can suddenly feel cheap? That is roughly where India sits right now. After a stretch of rapid gains, a bout of selling has left some of the country’s better businesses trading at prices that, in my view, look more interesting than the headlines suggest. I keep coming back to a simple thought: a weaker tape does not cancel a long story about incomes, cities, phones, and changing habits.
Why A Soft Patch In Indian Stocks Can Still Be A Gift
India has spent years near the front of the global growth pack. That is not a slogan. It shows up in how people shop, eat, save, and insure their families. More households are crossing into a middle-income band. More of them live in towns and cities. More of them treat a smartphone as ordinary, not exotic. When those three things move together, spending patterns change in ways that compound over a decade, not a quarter.
I find the recent weakness useful precisely because it forces a slower look. Fast markets make people lazy. Soft markets make people picky. The names that still look attractive after a pullback tend to share a few traits: a brand people already trust, a distribution machine that is hard to copy overnight, and a product that still has room to penetrate a huge population.
A crowded country with rising wages is not automatically a good stock market. The opportunity sits in the firms that can turn that wage growth into repeat spending.
That last point matters. Plenty of businesses will exist in a growing economy. Far fewer will take a rising share of the wallet. The three ideas below sit in different corners of daily life: convenience food and groceries, family protection and savings, and branded drinks. They are not a complete portfolio. They are a way to think about how consumer and financial habits may evolve if incomes keep climbing.
What Rising Incomes Actually Change
People do not jump from subsistence to luxury in one leap. They start paying for time. They start paying for predictability. They start paying for a name they recognize on a bottle or an app. That sounds obvious, yet it is easy to underplay how early India still is in several of those categories.
Take eating out or ordering in. A generation ago, that was a rare treat for many families. Now it is becoming a weekday habit in large cities, then a weekend habit in smaller ones. Or take insurance. Plenty of households still lean on gold, cash, and informal networks. That is not ignorance so much as habit. Habits loosen when pay packets stabilize and when a trusted bank branch is already part of the weekly routine.
Soft drinks sit in a similar place. Per-person consumption remains modest next to many other large markets. That gap is not a guarantee of growth. It is a map of unused demand if distribution keeps improving and if the weather, festivals, and youth culture keep doing what they usually do.
- More urban jobs tend to raise demand for speed and convenience.
- More formal saving tends to raise demand for simple protection products.
- More branded consumption tends to raise demand for drinks people already know.
- Scale in logistics or branches can turn a small ticket into a durable franchise.
In my experience, the mistake is to treat all of this as one “India trade.” It is not. A delivery platform, a life insurer, and a bottler live on different clocks. One is still fighting for unit economics and habit formation. One is compounding through a bank network. One is squeezing efficiency out of plants and routes. Mixing them without that distinction is how investors get surprised.
Eternal And The Convenience Habit
The first name trades in Mumbai under the parent banner Eternal, better known to most people through its food-delivery brand. The core idea is simple enough: connect hungry customers with restaurants and a large pool of riders. The less simple part is doing that at national scale, then layering on rapid grocery delivery as city life gets faster and less patient.
I have always thought food delivery looks messy from the outside. Margins wobble. Incentives come and go. Riders are a moving piece. Restaurants complain, then come back, then complain again. And yet the customer habit, once formed, is sticky in a way that spreadsheet skeptics sometimes miss. After a long day, people do not want a lecture about unit economics. They want dinner in forty minutes.
What stands out here is reach. A wide restaurant network plus hundreds of thousands of delivery partners is not something a new app copies over a weekend. Density matters. In a dense city, every extra order can make the next order cheaper to fulfill. That flywheel is ugly in the early years and elegant later, if management does not get drunk on growth for its own sake.
Then there is the grocery adjacency. Rapid delivery of everyday items is a different promise from a late-night burger. It is more frequent, more practical, and more likely to sneak into the weekly budget. Rising smartphone use helps. So do dual-income households that would rather pay a small fee than lose an hour in traffic. I would not call that a sure thing. I would call it a real demand curve, not a fad invented on a pitch deck.
Convenience is not a luxury product. In a crowded city it becomes a form of self-defense against time.
The risks are not subtle. Competition can turn vicious. Fuel, labor, and cloud costs can eat the model. Regulation around gig work can shift. Investors who treat this as a bond with a logo will have a bad decade. Investors who treat it as a platform that still has to earn the right to keep its customers may find the current valuation debate more useful than the last one, when optimism was louder.
Perhaps the most interesting aspect is not the app itself. It is the slow cultural shift underneath it. Ordering in used to signal a special night. Now it can signal a Tuesday. That change does not reverse easily once kitchens, riders, and customer expectations have all adapted.
SBI Life And The Quiet Protection Gap
The second idea is less flashy, which is part of why I like thinking about it. SBI Life Insurance sells protection and savings products into a country where insurance is still used less than the size of the economy would imply. That under-penetration is the whole thesis, provided the company can keep reaching people who would not walk into a specialist insurer on their own.
The practical edge is distribution. A close link with one of the country’s largest banks gives the insurer a map of branches and a river of existing customers. That sounds dull until you remember how most households actually buy financial products. They buy them from someone they already see. Trust, in this market, often looks like a familiar counter and a known name on the passbook.
I have found that insurance stories fail when people confuse “should buy” with “will buy.” Households should protect income. Many still do not. The conversion happens when incomes become regular, when a child arrives, when a parent falls ill, or when a banker explains a product without making it sound like homework. A wide branch network is not magic. It is a series of those conversations, repeated at scale.
- Identify households that already bank with a trusted institution.
- Offer simple protection and savings products rather than exotic wrappers.
- Use the branch relationship to lower the friction of the first purchase.
- Keep customers long enough for persistency to do the compounding.
Rising financial awareness helps, but I would not overstate how fast culture moves. Gold still has emotional weight. Property still has social weight. Insurance has to earn its place beside those older stores of value. That is why a company that already grows faster than many peers is more interesting than a theoretical “underpenetrated market” slide.
The risks here are quieter than in delivery, which does not make them smaller. Product mix can drift toward lower-quality savings if growth is chased too hard. Capital rules can tighten. Claims experience can surprise after a bad year. Equity-linked products can make reported growth look better than the underlying protection engine. A careful owner watches persistency and product quality, not just new business headlines.
Still, if the middle class keeps expanding, more families will want a formal answer to a blunt question: what happens if the main earner is gone? That question does not need a boom. It needs time, income, and a salesperson who is already in the room.
Varun Beverages And The Everyday Treat
The third name is Varun Beverages, the country’s largest bottler for a well-known global soft-drink group. It makes and moves brands people already recognize: cola, lemon-lime, citrus, the usual summer cast. The growth argument is almost embarrassingly straightforward. People still drink less of this stuff, per person, than in many other places. As pay rises, treats rise. As routes improve, availability rises. As plants get bigger, costs per case can fall.
I like businesses that sound simple and then reveal a hidden industrial layer. Bottling is that kind of work. You need plants in the right places, trucks that show up, cold space in small shops, and a sales force that understands a maze of towns. India’s retail landscape is not a neat supermarket grid. It is a scatter of kirana stores, highway stops, stadiums, and village counters. Winning that map is a decade-long project, not a campaign.
Scale helps twice. First, it gets the drink closer to the customer before a competitor does. Second, it spreads manufacturing and logistics costs over more bottles. That second effect is easy to ignore until a hot month arrives and the company that can restock fastest takes the sale. Execution records matter here more than slogans. A bottler that keeps opening capacity without losing discipline is doing a harder job than the brand on the label suggests.
| Business | Demand Driver | Key Advantage |
| Delivery platform | Urban convenience | Network density |
| Life insurer | Protection gap | Bank distribution |
| Bottler | Low per-person use | Plant and route scale |
There is a health debate around sugary drinks, and it would be silly to pretend it does not exist. Categories can shift toward lower sugar, water, juices, and energy formats. A bottler with a wide line-up can bend with that. A bottler married to one flavor of nostalgia cannot. I would watch mix as closely as volume.
Input costs are the other recurring headache. Resin, sugar, fuel, and power can all spoil a good summer. Currency moves can spoil a good year if equipment or concentrate pricing sits offshore. None of that cancels the long runway. It just means this is an operating company, not a theme park ride labeled “emerging consumer.”
How These Three Fit One Broader Story
Look at them side by side and a pattern appears. Each one sells something people buy more of as life gets a little more formal and a little more hurried. Dinner arrives through a phone. Protection arrives through a bank. A cold bottle arrives through a route that already exists when the temperature spikes.
That is not the whole of India. Infrastructure, manufacturing, and digital public goods matter too. I am not arguing that consumer names are the only door in. I am arguing that consumer and household-finance names are where the social change is easiest to see in revenue lines.
Quality, in this context, is not a vibe. It is pricing power plus distribution plus a balance sheet that can survive a dull year. The delivery platform has to prove that density eventually beats discounting. The insurer has to prove that bank traffic becomes persistency. The bottler has to prove that more plants do not mean sloppy capital allocation. Those are living tests, not slogans.
Long-term investing in a fast country still comes down to patient ownership of a few machines that already work.
Valuation, Timing, And The Urge To Wait For Perfection
Pullbacks create a mental trap. People wait for the “clean” entry after the dust settles. Dust rarely settles on a schedule. A market can look cheaper and still not be cheap in every name. That is why I prefer to separate the country view from the stock view. India can keep growing while a particular multiple stays too rich. The reverse can also be true for a quarter or two.
I have found it more useful to ask three plain questions. First, is the habit still spreading? Second, does the company still control a scarce pipe, whether that pipe is riders, branches, or trucks? Third, would a normal recession or a regulatory shove break the story or only slow it? If the answers stay decent while the price has come in, the work gets easier. If the answers weaken, a lower price is not a gift. It is a warning.
Currency is another quiet variable for anyone investing from outside. A strong local growth story can look average once translated. A weak patch in the share price can look worse than it is if the currency is doing the damage. None of that is a reason to avoid the market. It is a reason to size positions like an adult.
Risks That Do Not Fit On A Slide
Politics can change tax treatment, labor rules, or advertising norms. Weather can change beverage volumes. Food-delivery economics can change if cities restrict two-wheelers or if fuel spikes. Insurance growth can change if households get nervous and cling to cash. These are not exotic tail risks. They are ordinary facts of operating in a large, uneven country.
There is also the human risk of falling in love with a narrative. “Rising middle class” has launched a thousand mediocre investments. The phrase is not false. It is incomplete. The middle class can rise and still spend on unlisted housing, gold, school fees, and weddings before it spends on your favorite listed ticker. The companies that win are the ones sitting in the path of that spending, not the ones giving speeches about it.
- Policy shifts around gig work and data.
- Input-cost spikes in packaging and energy.
- Household preference for physical assets over policies.
- Competitive discounting that resets customer expectations.
- Execution slips when capacity grows faster than talent.
I would add one more, because it is unfashionable. Success itself can become a risk. A platform that grows too famous attracts copycats and politicians. An insurer that grows too fast attracts questions about product quality. A bottler that keeps posting neat volume numbers attracts complacency. Good businesses die of indigestion more often than of starvation.
A Practical Way To Think About Position Size
If these names belong in a long-term sleeve, they probably do not belong as a concentrated bet on a single app cycle. A modest basket that mixes convenience, protection, and staples can express the household story without pretending any one firm has a monopoly on India’s future. That sounds conservative. Good. Conservatism is underrated after a strong multi-year run.
Rebalancing matters more than people admit. A delivery name can double on sentiment and then spend two years going sideways while the insurer quietly compounds. A bottler can have a blistering summer and a dull monsoon. Letting winners become the whole thesis is how a diversified idea turns into an accidental single-stock fund.
Household growth sleeve, in plain terms:
  Convenience platforms
  Protection and savings
  Branded everyday products
None of this replaces homework on filings, capital allocation, and competitive maps. It is a frame. Frames are useful when markets get noisy and every commentator suddenly becomes an India expert for a week.
What I Keep Watching From Here
For the delivery business, I watch order frequency more than splashy user counts. Repeat behavior is the tell. For the insurer, I watch persistency and the mix between protection and noisier savings products. For the bottler, I watch route expansion, capacity discipline, and whether category mix is drifting toward healthier or at least more varied formats.
I also watch the street’s mood, though not because the street is wise. When everyone is bored with India, good assets can drift. When everyone is breathless, even decent assets get expensive. The recent softness feels closer to the first camp than the second, at least for high-quality consumer and financial names that still have runway.
Will every one of these three work? Of course not. Business is not a museum of perfect exhibits. One may stumble on regulation. One may overpay for growth. One may face a shift in taste. The point of looking at them together is not prophecy. It is pattern recognition. A country getting richer tends to buy time, safety, and small pleasures. These firms sell versions of those three things.
If you strip away the ticker symbols, that is the investment case in one sentence. Rising incomes change what a normal week looks like. The companies that already sit inside that normal week have a chance to turn national growth into shareholder returns. The ones that only talk about the theme do not. I know which group I would rather own after a messy few months in the market.
And if the tape gets messier still? Then the same questions apply, only with better prices attached. That is not bravado. It is the unglamorous job of long-term stock picking in a place that is still early in several everyday categories. The story is not that India cannot fall. The story is that a fall can, now and then, put the right machines on sale.



