

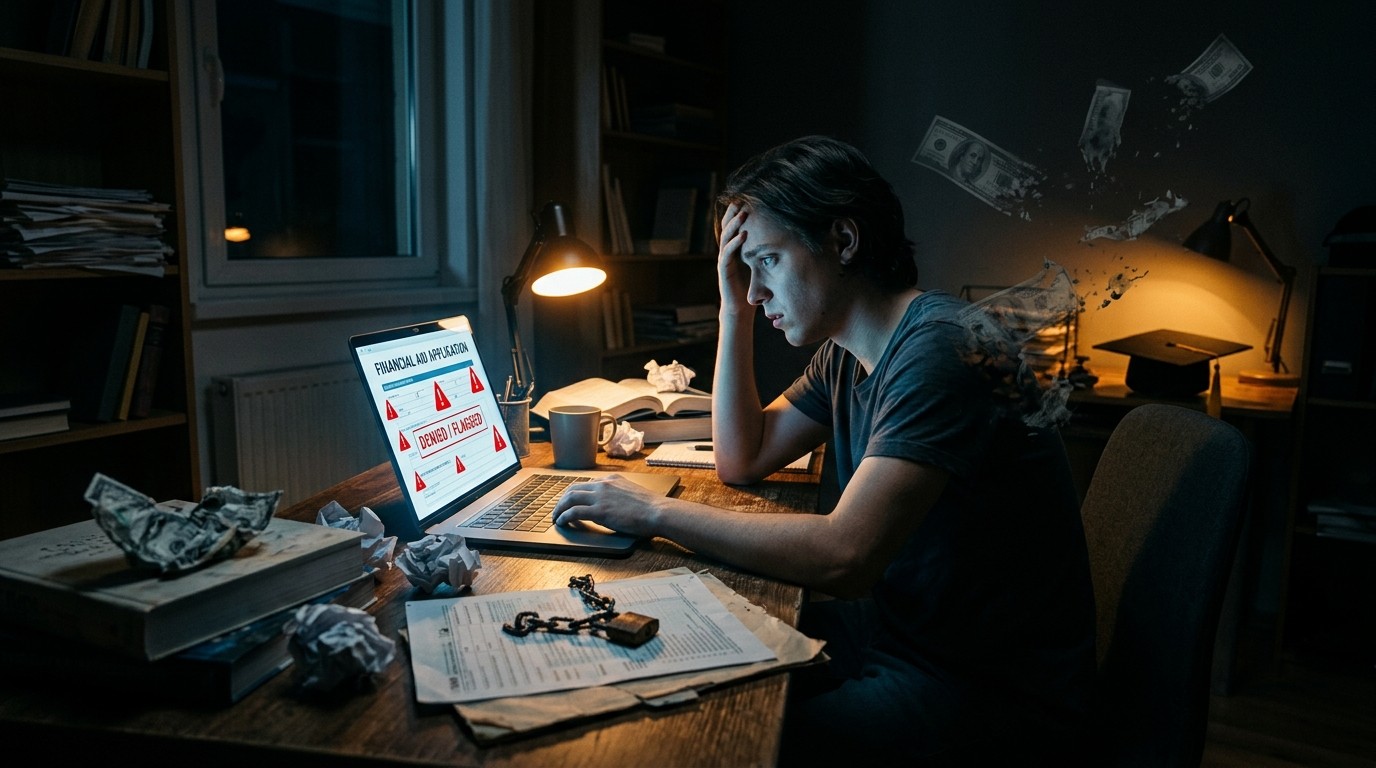
Treasury Uncovers 270 Million In Student Aid Fraud Schemes

Imagine discovering your identity was used to collect thousands in student aid you never applied for. Officials just flagged 270 million dollars in suspicious activity. The real cost to students and taxpayers might be even higher.
Financial market analysis from 20/10/2026. Market conditions may have changed since publication.
I was chatting with a friend the other day who still carries a hefty student loan balance years after finishing school. She mentioned how careful she is with her personal details online, almost paranoid about it. That conversation stuck with me when I came across recent findings about large-scale problems in federal student aid. It got me thinking about how easily systems meant to help people can be turned against them. The scale of what officials have been looking into is hard to ignore, and it raises questions about who ends up paying the price when things go wrong.
Federal student aid programs exist to open doors. They are supposed to give people a shot at education they might not otherwise afford. Yet when fraud creeps in, those same programs can end up supporting the wrong people while leaving real students and taxpayers holding the bag. Recent work by financial investigators has brought this into sharper focus. They reviewed a wave of reports and uncovered hundreds of millions of dollars in activity that looks suspicious. It is the kind of number that makes you pause and wonder how much of the system is operating as intended.
How Investigators Uncovered Hundreds Of Millions In Suspicious Activity
Financial crime units have been paying closer attention to patterns that do not quite add up. After sending out an alert earlier this year asking banks and other institutions to watch for certain red flags, they started receiving a flood of reports. The volume was striking. More than twenty thousand transactions raised enough concern that they were flagged for further review. When investigators added up the amounts involved, the total approached two hundred seventy million dollars. That figure represents money that was moving in ways that did not match normal student aid activity.
These are not random one-off mistakes. The reports came in after a specific request for institutions to look for activity connected to student aid programs. That focused attention produced results quickly. Officials then passed the information along to federal investigators so they could dig deeper. The process shows how financial institutions sit at an important intersection. They see the money moving, and when they are asked to look for particular patterns, they can surface problems that might otherwise stay hidden.
I find it interesting that the alert went out in July and the review covered activity going back to February. That suggests the issues were already building before the formal call for reports. Perhaps the most useful aspect of this approach is the way it turns everyday banking data into a early warning system. It is not perfect, of course. Not every suspicious report turns out to be actual fraud. Still, the sheer volume makes it clear that something larger is happening across the system.
Understanding Ghost Student And Straw Student Schemes
Two patterns keep coming up when people describe how student aid fraud typically works. The first is what investigators call ghost student schemes. In these cases, someone steals another person’s personal information and uses it to enroll in classes. The real person often has no idea any of this is happening. Aid money gets disbursed, and the fraudster collects it. By the time the victim notices unusual activity on their credit or receives unexpected bills, the damage is already done.
The second approach involves straw students. Here, the fraudster pays actual people to enroll and then takes most or all of the financial aid that follows. Sometimes the person who agrees to this knows they are participating in something questionable. Other times they may not fully understand the longer-term consequences, such as loans they will eventually be expected to repay. In a few reported situations, employees inside schools have allegedly played a role, which makes the schemes harder to spot from the outside.
Both methods exploit the same basic weaknesses. Enrollment processes and aid applications rely heavily on self-reported information and digital verification that is not always as robust as it needs to be. When someone has access to a Social Security number, a date of birth, and a few other details, they can sometimes move through the system before anyone questions the application. The result is aid flowing to people who never intended to attend class or who never existed in the first place.
- Ghost student fraud typically relies on stolen identities and creates victims who discover the problem later.
- Straw student arrangements involve willing or semi-willing participants who enroll on behalf of someone else.
- Both can involve multiple schools and multiple states at the same time.
- School employees have occasionally been implicated, complicating internal detection.
These schemes are not new, but the volume of reports suggests they may be scaling up. Criminals appear to be treating federal aid as a relatively low-risk way to extract money. Compared with other types of fraud that require more direct confrontation, applying for aid using someone else’s information can feel safer to the people running the schemes. That calculation changes once investigators start connecting the dots across institutions and across states.
Concrete Examples From Recent Prosecutions
Prosecutors have already secured convictions that illustrate how these operations can grow. In one case, a man from the Detroit area was sentenced to more than seven years in federal prison. He and others had submitted fraudulent aid claims involving more than twelve hundred individuals. The total they collected exceeded ten million dollars. The activity touched roughly one hundred schools spread across more than twenty states. That geographic reach shows how organized groups can exploit the fact that aid programs are national while individual schools often operate with limited visibility into each other’s data.
In another matter, a former professor admitted to participating in a scheme that used fraudulent applications. More than one hundred false filings were made at various colleges and universities in Texas. The details of that case are still working their way through the system, but the admission itself is notable. When someone who has worked inside higher education is involved, it raises the possibility that insider knowledge helped the fraud continue longer than it otherwise might have.
Federal student aid is intended to expand educational opportunities, not line the pockets of fraudsters who steal from students pursuing their education and hardworking taxpayers.
– Statement from a senior Treasury official
Those two examples are public and have already resulted in formal action. They probably represent only a fraction of what investigators are looking at. The twenty thousand suspicious transactions mentioned earlier include many that have not yet led to charges. Some of those reports may turn out to be explainable. Others may point to additional networks that are still operating. The gap between what has been flagged and what has been fully prosecuted is one reason officials are emphasizing the need for continued reporting from financial institutions.
The Real Costs For Students, Schools, And Taxpayers
Fraud of this kind does not just move money from one place to another. It creates concrete problems for people who are trying to use the system legitimately. Grant money is finite. When it goes to ghost or straw students, less is available for applicants who meet the requirements and plan to attend. In some cases, fraudulent enrollments can also occupy seats in classes. A real student who is waitlisted or shut out of a course because of that has lost an opportunity that is difficult to quantify in dollars alone.
Identity theft victims face an additional layer of difficulty. They may discover student loan debt they never took on. Clearing that up requires time, documentation, and often legal or credit-repair help. Meanwhile, the debt can affect credit scores, housing applications, and future borrowing. Some victims only learn about the problem when they try to apply for aid themselves or when a collections notice arrives. By then, months or years may have passed.
Taxpayers ultimately fund the programs. Every dollar that is disbursed fraudulently is a dollar that either increases the overall cost of the programs or reduces the amount available for intended purposes. Officials have noted that education authorities have already blocked nearly two billion dollars in attempted fraud. That prevention number is large, yet the two hundred seventy million still flagged for investigation shows that not every attempt is stopped before money moves. The difference between those two figures is worth thinking about. Prevention is clearly happening, but the residual problem remains substantial.
From a personal standpoint, I have always believed that systems designed to help people should be as resistant to abuse as possible. When they are not, the people who suffer most are often the ones who can least afford another setback. Students already managing part-time work, family responsibilities, or limited savings do not have much margin for error if their aid is delayed or reduced because of fraud elsewhere in the system. The same is true for taxpayers who support these programs in the expectation that the money reaches the intended recipients.
| Type of Impact | Who Is Affected | Typical Consequence |
| Reduced grant availability | Legitimate students | Less aid or delayed disbursement |
| Occupied class seats | Enrolled and waitlisted students | Missed courses or delayed graduation |
| Unexpected debt | Identity theft victims | Credit damage and repayment demands |
| Higher program costs | Taxpayers | Increased overall spending or reduced efficiency |
What Officials Are Doing To Respond
The current effort involves multiple parts of the government. Financial investigators have shared the suspicious activity reports with agencies that can pursue criminal cases. At the same time, a task force focused on fraud more broadly is involved. That coordination matters because student aid fraud often overlaps with other forms of identity theft and benefit fraud. Sharing information across agencies can help investigators see larger patterns that would be invisible if each office worked only with its own data.
Education officials have also held meetings specifically about fraud in higher education. Participants have discussed detection methods, verification improvements, and ways to share warnings more quickly. One official noted that nearly two billion dollars in attempted fraud had already been stopped. That figure suggests that existing controls are catching a meaningful share of attempts. The remaining challenge is closing the gaps that still allow substantial amounts to move.
Encouraging people who see suspicious activity to come forward is another part of the response. Whistleblowers inside schools or financial institutions can provide details that transaction data alone does not capture. When those tips lead to recovered funds or stopped schemes, they create a deterrent effect that pure data analysis cannot match. The combination of automated reporting from banks and human tips appears to be the practical approach officials are taking right now.
- Financial institutions report suspicious patterns after receiving targeted alerts.
- Investigators review the reports and forward promising cases to prosecutors.
- Education agencies improve verification and share information with other departments.
- Whistleblowers provide additional context that helps prioritize investigations.
None of these steps is especially glamorous. They involve reviewing large volumes of data, coordinating across agencies that do not always share information easily, and following up on leads that may or may not pan out. Still, the results so far show that the work is producing concrete numbers. The two hundred seventy million dollars already identified is evidence that the process can surface problems at scale. Whether that leads to a lasting reduction in fraud will depend on how consistently the follow-up continues.
Practical Steps Students And Families Can Take
While larger systemic changes are underway, individuals still need to protect themselves. Universities have begun reminding students about basic precautions. One institution advised people to share personal information only on trusted, secure sites. That sounds obvious, yet phishing messages and fake portals continue to catch people off guard. The recommendation to treat emails, texts, and even voicemails with extra skepticism is worth taking seriously. Messages that create urgency or offer something that seems too good to be true are classic warning signs.
Monitoring credit reports regularly is another practical step. Many identity theft victims first notice a problem when a new account or inquiry appears. Setting up free credit monitoring or checking reports at least a few times a year can shorten the time between when fraud occurs and when it is discovered. The sooner the issue is reported, the easier it usually is to limit the damage. Some people also place fraud alerts or credit freezes if they have reason to believe their information has been exposed.
I have found that the people who avoid the worst outcomes are usually the ones who stay slightly more vigilant than average without becoming overwhelmed by it. Checking a credit report once a quarter takes very little time. Being cautious about which websites receive a Social Security number is mostly a matter of habit. Those small practices do not eliminate risk, but they raise the odds that a problem will be caught early. In a system where fraudsters are actively looking for openings, that difference can matter.
Treat digital content, like emails, texts, voicemails, and website content, with increased scrutiny, especially if the materials or resources they provide or advertise seem too good to be true or appear designed to create a sense of urgency.
– Guidance issued by a public university
Families who are helping students navigate aid applications can also play a role. Talking through what official communications look like, and what they do not look like, reduces the chance that a fake message will succeed. Keeping records of applications and disbursements makes it easier to spot discrepancies later. None of these steps is complicated, yet they address the most common entry points fraudsters use.
Broader Questions About Accountability And System Design
Looking at the numbers, it is reasonable to ask whether current verification methods are sufficient for the volume of applications the system handles. Digital processes have made it faster and easier to apply for aid, which is generally a good thing. At the same time, those same processes can make it faster and easier for fraudulent applications to move through if the checks are not strong enough. Finding the right balance between accessibility and security is not simple. Too many barriers and legitimate students face delays or denials. Too few and fraud increases.
The involvement of financial institutions is a relatively new emphasis. Banks see the actual movement of money, so they are well positioned to notice when disbursements do not match expected patterns. Their willingness to report suspicious activity, and the government’s willingness to act on those reports, will determine how effective this layer of oversight becomes. Early results are promising, but sustaining that effort requires ongoing attention from both sides.
Perhaps the most interesting aspect of the current situation is the public acknowledgment that the problem is large enough to warrant coordinated action. When senior officials state that aid should not line the pockets of fraudsters, they are setting an expectation. Meeting that expectation will require continued investigation, prosecution where warranted, and improvements in how applications are verified. It will also require schools and financial institutions to keep sharing information rather than treating each case as an isolated incident.
From what I have seen in other areas of government benefit programs, fraud tends to concentrate where verification is weakest and the potential payoff is highest. Student aid appears to meet both conditions for some operators. Closing those gaps will not eliminate every scheme, but it can raise the cost and risk enough to reduce the overall volume. The two hundred seventy million dollars already identified shows both the size of the opportunity criminals see and the ability of current tools to surface problems when they are used deliberately.
The conversation I had with my friend about her student loans ended on a practical note. She checks her credit regularly and is careful about which sites she trusts with her information. Those habits will not stop every fraudster, but they give her a better chance of noticing a problem before it grows. On a larger scale, the same principle applies. Officials have tools that can identify suspicious activity at volume. Using those tools consistently, following up on the reports, and tightening verification where it is weakest are the steps that determine whether the two hundred seventy million dollars is a one-time finding or the start of a sustained reduction in student aid fraud. The difference matters for every student who is counting on the system to work as intended and for every taxpayer who funds it.
Additional reporting and continued coordination between financial institutions and investigators will likely produce more numbers in the months ahead. Some of those numbers will represent funds recovered. Others will represent schemes that were stopped before money moved. Either outcome is preferable to allowing the activity to continue unnoticed. The current findings have already demonstrated that the scale is large enough to justify the effort. What remains is the less visible work of turning those findings into lasting changes in how aid is verified and how suspicious patterns are pursued. That work is underway, and the results so far suggest it is capable of identifying problems that would otherwise stay hidden.
In the end, the programs exist to help people gain skills and credentials. When fraud diverts resources, it undermines that purpose for everyone else. The recent focus on suspicious transactions is a practical response to a documented problem. Whether it leads to a meaningful drop in the amount of aid that is misused will depend on how thoroughly the follow-up continues and how effectively verification improves. Those are measurable outcomes, and the next set of reports from investigators should give a clearer sense of whether the current approach is closing the gaps or simply documenting them.
In investing, what is comfortable is rarely profitable.


Stock Futures Rise On Earnings Optimism Amid Market Volatility

France Riots Media Coverage And Immigration Debate Explained
Related Articles

Why Companies Reject Airlines New Basic Business Class Fares
Companies expected to embrace cheaper business class options but many are saying no thanks. The reason might surprise you as flexibility becomes the real battleground in corporate skies...
Tech Outages: Impact on Online Dating Trust
Tech outages hit online dating hard, shaking user trust. How do platforms recover, and what can users do to stay connected? Dive into the impact...

Sparkassen Crypto Trading Launch For Five Major Tokens
Germany’s massive Sparkassen network just opened crypto trading to millions of everyday customers. Five major tokens are now available inside the familiar banking app, yet the real story goes deeper than the launch itself.