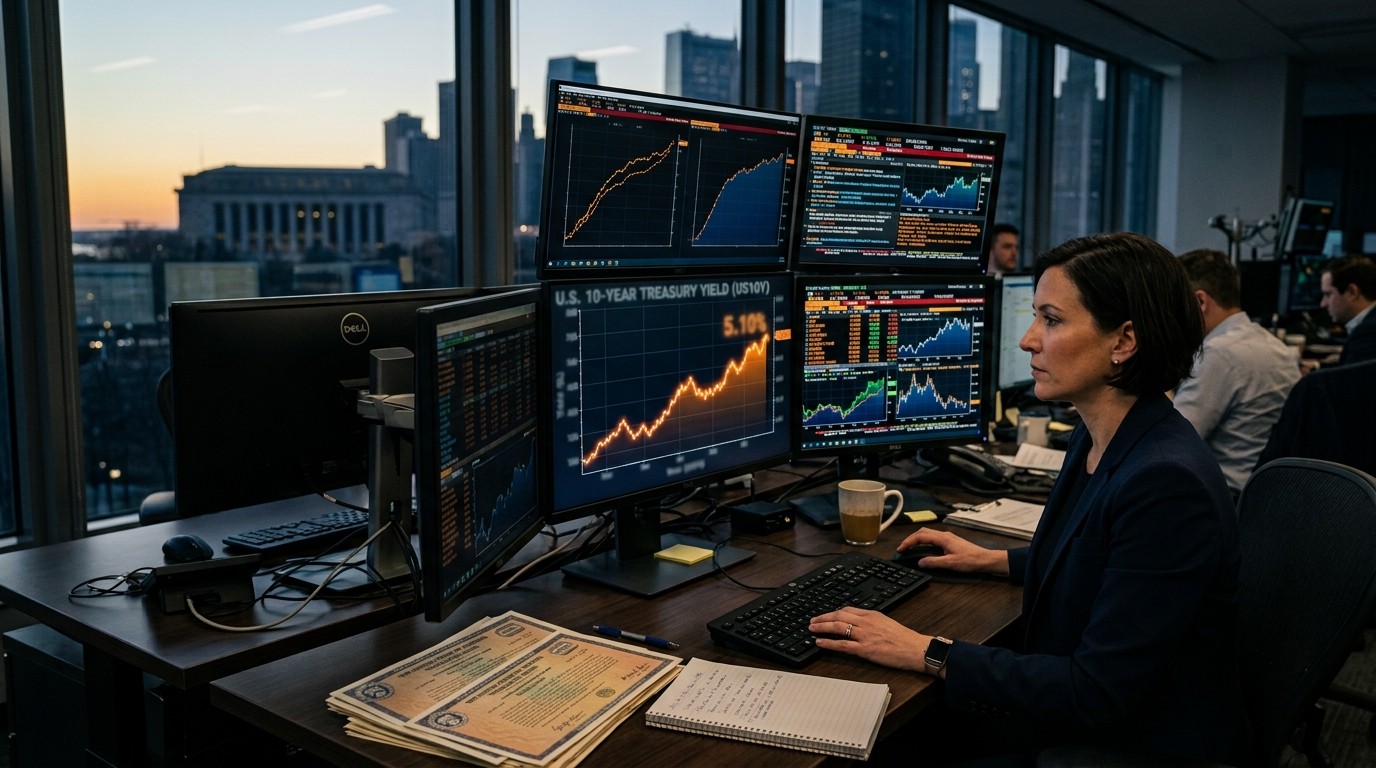

Have you checked the 10-year yield lately and felt that little twist in your stomach? I have. Watching a benchmark that spent years near historic lows push through a 19-year high is the kind of market moment that changes conversations at dinner tables and in portfolio reviews. The climb did not stop overnight. Early Thursday the yield added another basis point, sitting near 5.124% after Wednesday’s jump of more than 13 basis points to 5.104%. That is not a rounding error. That is the market rewriting the cost of money in real time.
Why Treasury Yields Are Still Rising After A 19-Year High
Yields and prices move in opposite directions. When investors sell government bonds, prices fall and yields rise. That simple mechanic is doing a lot of work right now. The 30-year bond yield ticked higher as well, moving over a basis point toward 5.42%. The 2-year note was almost unchanged near 4.895%. In my experience, that mix tells you something useful. The long end is still absorbing the shock, while the front end is already priced for a policy path that looks tighter than many people expected a few weeks ago.
One basis point equals 0.01%. It sounds tiny until you multiply it across trillions of dollars of debt, mortgages, and corporate borrowing. Suddenly the “tiny” move is not tiny at all. I keep coming back to that because casual commentary often treats yield spikes like weather. They are not weather. They are the price of time, risk, and inflation expectations colliding in one number.
Strong Business Activity Changed The Rate Story Fast
The spark this week was a batch of activity readings that came in hotter than expected. Services activity jumped to 58.7 in September, the strongest print in almost five years. Manufacturing climbed to 56.7, a level not seen in more than four years. Those are not recession numbers. Those are expansion numbers with some heat still in them.
Markets did what markets do. They updated the odds. Traders last assigned roughly a 70% chance of another policy increase at the October meeting. That is a meaningful shift. When growth looks resilient, the case for waiting around gets weaker. A Federal Reserve official also said further policy adjustments are likely if inflation is going to be brought back to target. No drama. Just a reminder that the job is not finished.
The main driver was a strong batch of activity data, along with a rebound in oil prices, which both led to mounting speculation about faster rate hikes.
– Market desk note circulating Thursday morning
That line matches what I saw on screens. Resilient growth does not automatically mean runaway inflation. It does mean policymakers have more room to stay restrictive. That distinction matters. Plenty of people still want a clean “pivot” story. The data this week did not cooperate.
Oil Prices Added Fuel To The Bond Selloff
Energy is never just energy when you are pricing bonds. International benchmark crude eased a bit early Thursday, down about 0.54% near $103.66 a barrel. U.S. crude for November slipped 0.6% to $92.68. Those are still elevated levels. High oil works its way into inflation expectations, shipping costs, and household budgets. Bond investors notice.
I’ve found that oil spikes do not need to last forever to move the 10-year. They only need to keep the “stickier inflation” narrative alive for another few weeks. That is enough to lift term premium and push long-duration paper out the door. You can argue about second-round effects later. The first-round effect is already in the price.
This Is Not Just A U.S. Story
Look abroad and the picture is equally restless. Japan’s 10-year government yield jumped 8 basis points to 3.055%, the highest since August 1996. That is a generation of market memory getting rewritten in a single session. U.K. gilts and German bunds also moved higher. When several large government markets sell off together, you stop calling it a local quirk.
Perhaps the most interesting aspect is the synchronization. Different central banks, different fiscal pictures, same direction in yields. Global investors do not need identical stories. They need correlated risk. Once U.S. Treasuries lurch higher, duration everywhere gets marked to a new discount rate. That is how a domestic data surprise becomes a worldwide bond event.
| Market | Recent Move | Why It Matters |
| U.S. 10-year | Near 5.124% after a 19-year high | Sets mortgage and corporate borrowing tone |
| U.S. 30-year | Around 5.42% | Long-duration portfolios feel the hit first |
| U.S. 2-year | Near 4.895% | Tracks near-term policy expectations |
| Japan 10-year | 3.055%, highest since 1996 | Signals a broader global reset in yields |
What Higher Yields Mean For Everyday Borrowing
Let’s talk about kitchens and car lots, not just trading floors. Mortgage rates take their cue from the 10-year more than from overnight policy. When the benchmark climbs, home loans get more expensive, refinancing slows, and monthly payments stretch. New home sales data due later in the week will be watched for a reason. Housing is rate-sensitive in a way stock indexes sometimes pretend not to be.
Auto loans, small-business credit lines, and floating-rate debt all feel the same pressure with a lag. I would not pretend every household tracks basis points. People track the payment. That is the transmission channel that eventually shows up in spending. It is also why a strong activity print can look like good news and still tighten financial conditions at the same time.
- Homebuyers face higher monthly costs when the 10-year stays elevated.
- Companies rolling over debt pay more for the same balance sheet.
- Savers finally see more income on cash and short Treasuries.
- Long-bond funds can show paper losses even if coupons look attractive.
There is a split personality in this market. Cash is useful again. Duration is expensive again. That split is healthy if you planned for it. It is painful if your portfolio assumed 2020 would last forever.
How Investors Are Repricing The October Meeting
Rate-hike odds near 70% for October are not a guarantee. They are a live bet. Markets can overshoot. Data can cool. A single soft labor print can yank those odds back down. Still, you do not get to 70% by accident after a 19-year high in the 10-year. Something in the growth-inflation mix forced a rewrite.
Weekly jobless claims are on deck. So are August new home sales. Those two releases will not settle the debate by themselves. They will either feed the “economy can handle higher rates” camp or give the “this is getting too tight” camp a little oxygen. I tend to watch claims for cracks and housing for confirmation. That pairing has been more honest than a lot of narrative spinning.
Resilient growth would enable policymakers to keep tightening in order to deal with inflation.
That is the core tension. Strength is not automatically bullish for risk assets when it raises the discount rate. Equity investors sometimes cheer good data and then notice the bond market is selling the same news. The second reaction is often the one that lasts.
The Quiet Math Behind A Basis Point
People glaze over when you mention duration. Fair. Here is the plain version. A longer-maturity bond falls more in price when yields rise. A 30-year note is a long stream of fixed payments. Discount that stream at 5.42% instead of 5.20% and the present value drops. Funds that hold a lot of that paper mark it down. That is not default risk. That is rate risk doing its job.
Short paper behaves differently. The 2-year already embeds a lot of near-term policy. If the next hike is widely expected, the 2-year can sit still while the 10-year and 30-year keep adjusting term premium. That is one reason the curve can look messy in weeks like this. It is not broken. It is arguing with itself about how long restriction lasts.
Quick yield snapshot in plain English:
  2-year  ~ policy path
  10-year ~ growth, inflation, term premium
  30-year ~ long-run discount rate and duration pain
What This Means For Stocks, Credit, And Cash
Higher risk-free yields compete with equities. That sentence is old and still true. A 5% Treasury is an alternative. It does not make stocks worthless. It does raise the bar for valuations that assumed cheap money as a permanent feature. Growth names with cash flows far in the future feel that bar first. Banks can benefit from higher net interest margins, at least until credit quality wobbles. It is never one trade.
Credit spreads can stay calm even while government yields jump. That combination is interesting and a little dangerous. Calm spreads say investors are not panicking about defaults. Rising Treasuries say the risk-free hurdle is moving. Corporate borrowers still pay the sum of both. I would rather see honest widening than fake calm, but markets rarely give you the tidy version.
- Revisit duration. Long bonds can recover later, but the mark-to-market sting is real now.
- Respect cash. Short yields near 5% are not a rounding error in a household budget.
- Stress-test floating-rate debt. Payments can creep even if the headline policy rate pauses later.
- Do not treat one hot activity print as a full-year forecast. Data series wiggle.
- Watch housing and claims before declaring victory for either camp.
A Personal Read On The Mood In Rates
I’ve sat through enough rate cycles to know the language changes before the policy does. A few months ago the conversation was about when cuts begin. This week it is about whether another hike is still on the table. That swing is not random. It is what happens when activity refuses to roll over and oil refuses to behave.
Is the market overreacting? Maybe a little. Markets do that. Is the direction surprising if you actually read the activity numbers? Not really. An economy that prints services activity near 59 and manufacturing near 57 is not begging for easier money. It might still need time. Time is not the same thing as a cut.
I also think people underestimate how global this reset feels. A Japanese 10-year at a three-decade high is not a footnote. It is a reminder that the era of suppressed yields was a policy choice, not a law of nature. When that choice gets revisited in several places at once, the adjustment can look violent even if the destination is simply “more normal.”
Inflation, Policy, And The Temptation To Call The Top
Calling the top in yields is a popular sport. It is also a good way to get humbled. Inflation does not need to reaccelerate sharply to keep the 10-year bidless for a while. It only needs to stay sticky enough that policymakers refuse to ease. High oil helps that stickiness. Strong services activity helps it too, because services inflation is often slower to roll over than goods inflation.
Further policy adjustments, in the phrasing used this week, is a careful sentence. It does not promise a hike at every meeting. It does reject the idea that the work is done. Markets heard that. They sold duration. That is not mysterious.
Could yields fall quickly if claims spike and housing slumps? Of course. Rates markets are forward looking and occasionally dramatic. The honest stance is not “yields only go up.” The honest stance is “the easy-money discount rate is no longer the base case.” That is a bigger shift than any single basis point.
How Different Investors May Respond Without Panicking
If you are a retiree living on coupons, higher yields are not a villain. New purchases can lock in better income than you could get for years. The pain is in older, lower-coupon holdings that reprice lower. Laddering can help. So can accepting that mark-to-market and cash flow are not the same thing.
If you are a homebuyer, the math is uglier. Affordability was already stretched. Another lift in the 10-year does not help. Waiting for a perfect dip in mortgage rates is a strategy a lot of people have tried. Sometimes it works. Sometimes the house you wanted is gone and rates are still high. I do not have a cute answer for that. I only have the observation that housing markets clear on payments, not on wishes.
If you run a company, refinancing calendars suddenly matter more than slogans about “cheap capital forever.” Locking some fixed-rate funding while markets are orderly is boring. Boring is underrated when the 30-year is printing above 5.4%.
The Week Ahead Still Has Room To Surprise
Thursday’s claims and home sales will not end the argument. They can tilt it. A firm claims number plus decent housing would reinforce the “growth can take it” camp. A sharp rise in claims would give bond bulls a chance to buy the dip in prices. Either way, the 19-year high already happened. That fact sits on the chart whether the next print is hot or cold.
I keep a simple checklist on weeks like this. Did activity surprise to the upside? Yes. Did a policymaker sound finished? No. Did oil stay high enough to bother inflation math? Yes. Did other major bond markets join the move? Yes. That is a lot of boxes for one selloff. You can still fade it. Just know what you are fading.
A Longer View: Why This Cycle Feels Different
For more than a decade, many portfolios were built on the idea that yields had a ceiling and a habit of falling whenever growth wobbled. That habit trained people. It also trained algorithms, target-date funds, and casual commentary. Breaking a 19-year high is not only a statistic. It is a challenge to that training.
Fiscal supply is part of the backdrop too, even when a given session is driven by activity data. Large government borrowing needs a buyer. Higher yields are how you find more buyers. That is uncomfortable if you liked cheap deficits. It is straightforward if you remember that markets clear on price.
In my view, the more useful question is not “will the 10-year hit 5.2% tomorrow.” It is “what business models still work if 4.5% to 5.5% is a normal neighborhood rather than a crisis print.” Companies, households, and funds that answer that question early will look lucky later. They will not have been lucky. They will have been paying attention.
Practical Takeaways Without The Noise
You do not need a 40-page strategy note to act like an adult in this tape. Know your duration. Know your floating-rate exposure. Know whether your stock holdings assume discount rates from another era. Then decide if the 70% October hike odds feel rich or cheap given the activity data you just saw.
None of this requires panic. Bond selloffs happen. They feel worse when they arrive after a long period of sleepwalking. The 10-year at 5.12% is a live market. It is also a reminder that the cost of waiting, borrowing, and promising future cash flows has gone up. That reminder is the story. The rest is commentary.
If the next data batch cools, yields can reverse hard. If it does not, the 19-year high may look like a waypoint rather than a peak. I will not pretend I know which one we get. I will say this much. Ignoring a global government-bond selloff because it is inconvenient is a choice. It is rarely a good one.
When the risk-free rate moves, every other asset has to introduce itself again.
That is the sentence I keep taped near the screen this week. Strong activity. Hawkish-leaning comments. High oil. A 10-year at a 19-year high that refused to roll over the next morning. Add a Japanese yield at a 30-year high and you have more than a headline. You have a market trying to remember how to live with expensive money. Some investors will adapt. Some will wait for the old regime to come back. Only one of those approaches treats the tape as real.