
I still check Treasury yields before I check the weather. That sounds odd until you live through a week when a two-basis-point move on the 10-year note can rearrange mortgage quotes, corporate funding plans, and the mood on a trading floor. Early Tuesday, those yields eased again. Not a collapse. Not a celebration. Just a small, careful step lower while everyone waited for fresh jobs numbers and another round of central-bank talk.
Why The Bond Market Went Quiet Before The Data
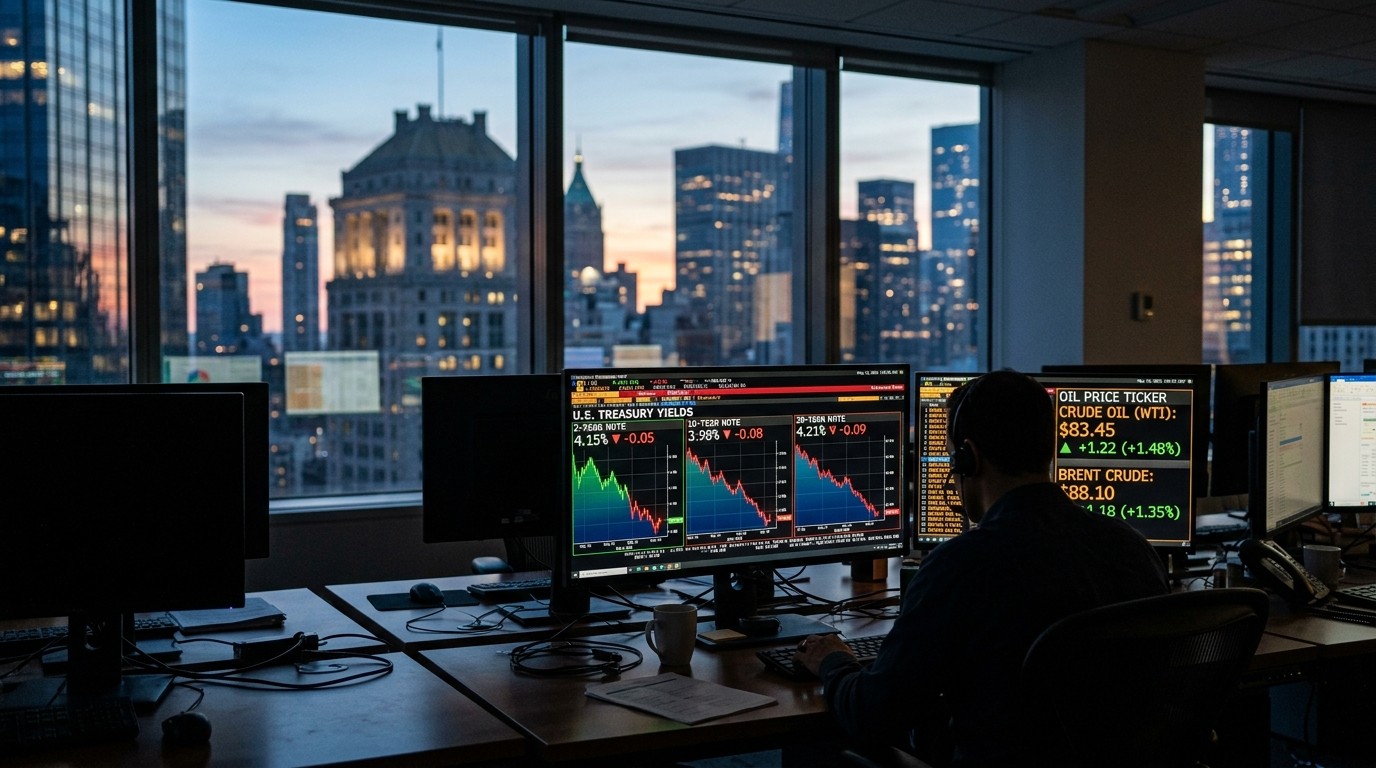
Shortly after 5 a.m. Eastern, the benchmark 10-year Treasury yield was down about two basis points near 4.943%. The 2-year note slipped one basis point to 4.741%. The 30-year bond yield fell two basis points to 5.272%. A basis point is one hundredth of a percentage point. Prices and yields move in opposite directions, which is the first thing new bond watchers forget and the last thing veterans stop repeating.
That kind of move is small on a chart and large in a portfolio. In my experience, the market often does this right before a data print: it leans a little, then waits. Nobody wants to be the person who sold the long bond five minutes before a soft jobs number, or bought it five minutes before a hot one.
The Calendar That Is Driving The Tape
Investors are watching weekly private employment figures due in the early afternoon. Those numbers are not the official government payrolls report, but they have become a useful warm-up. They can shift rate expectations for a few hours and, on a nervous day, for a few sessions.
Policy voices are also on the schedule. A senior Fed official is set to speak at a Treasury market conference in the morning. Another governor speaks Wednesday at a housing affordability event. Housing and Treasuries are cousins. When long rates stay high, monthly payments stay high. When monthly payments stay high, demand cools. That feedback loop is why bond desks listen to housing speeches even when the topic sounds domestic and dull.
If demand overheats, there is no ambiguity about how the Fed needs to respond.
That line, from a regional Fed president speaking in London, is the kind of sentence traders underline. It is not a rate-cut speech. It is a reminder that the committee still sees a two-sided risk: inflation that refuses to settle, and growth that could run hotter than the economy can absorb.
The Inflation Calendar That Keeps Slipping
Perhaps the most interesting part of that London appearance was not the hawkish tone. It was the calendar of disappointment. Forecasters, he noted, have spent more than a year pushing back the date when inflation was supposed to peak and start falling. First it was late 2025. Then early 2026. Then the second quarter, the third, the fourth. Now some of the talk points into 2027. That is not a comforting pattern. I have found that markets can live with high rates. They struggle with moving goalposts.
He also said he was especially attuned to elevated inflation in service-sector industries, and to any sign that heavy construction around artificial-intelligence data centers is spilling beyond its own lane. In plain English: if a boom in one corner of the economy starts bidding up labor, materials, and power across the board, policy cannot treat it as a cute one-off.
That is why the 10-year yield sitting near 4.94% still matters. It is not just a number on a screen. It is the market’s running estimate of growth, inflation, and the path of official rates, all mashed into one price.
What A Softening Curve Usually Means
When the 2-year, 10-year, and 30-year all ease together, the message is usually simple. Traders are a bit more willing to own duration. They are a bit less sure that the next surprise will be hotter inflation or a firmer labor market. They are not declaring victory. They are reducing the cost of being wrong overnight.
- The 2-year yield tracks policy expectations more closely than the long end.
- The 10-year yield is the workhorse for mortgages, corporate benchmarks, and fund models.
- The 30-year yield tells you how much compensation investors demand for locking money away for a generation.
A one-basis-point dip in the 2-year is a shrug. A two-basis-point dip in the 10-year and 30-year, on the same morning, is a mild bid for safety and a mild fade of the most aggressive inflation scare. Mild is the key word. This is not a regime change.
Oil Is Back In The Bond Conversation
Energy prices did not sit still. Crude futures rose after comments that all Iranian airlines would be shut down from Wednesday. Brent for November delivery last traded more than 1% higher near $101.53 a barrel. West Texas Intermediate advanced about 0.7% near $96.45. Those are not quiet numbers.
Oil and Treasuries have a messy relationship. Higher crude can feed headline inflation. Headline inflation can keep official rates higher for longer. Higher-for-longer usually supports bond yields. But risk-off headlines from the Middle East can also send money into government paper. So you can get rising oil and falling yields on the same morning. It looks inconsistent until you remember that traders are pricing two different clocks: the inflation clock and the geopolitical clock.
I’ve found that the first hour after an energy shock is often the least useful hour to over-interpret the bond tape. People hedge first. They think later.
Politics, Diplomacy, And The Price Of Duration
World leaders are gathering in New York against the backdrop of an ongoing conflict in the Middle East. Bond markets do not vote. They do price uncertainty. When diplomacy is noisy and energy supply looks fragile, the long end of the Treasury curve can behave like a pressure valve. Sometimes it rallies. Sometimes it sells off because inflation risk wins the argument. Tuesday’s early dip in yields suggests the first impulse was caution, not a sudden burst of growth optimism.
Does that mean investors expect a peaceful week? Not really. It means they wanted a little more ballast before the data and the speeches. Ballast is underrated.
How Ordinary Investors Should Read A Two-Basis-Point Move
If you do not trade bonds for a living, two basis points can sound like trivia. It is not trivia if you are refinancing, buying a home, or sitting in a bond fund that marks to market every day. A small decline in yields lifts existing bond prices a little. It also trims the income available on new purchases a little. Same move, two feelings.
Here is the practical split I keep coming back to.
- If you need cash in the next year, short bills and notes still do the job. The 2-year near 4.74% is not pocket change.
- If you are building a longer ladder, the 10-year near 4.94% remains a serious income level compared with the decade after the financial crisis.
- If you want maximum sensitivity to a future rate-cut cycle, the 30-year near 5.27% is where the drama lives. It can make you look brilliant or reckless in the same quarter.
None of those choices should be made because yields ticked lower before breakfast. They should be made because the income, the duration, and the sleep-at-night factor fit the rest of your life.
Services Inflation And The Data-Center Question
Services inflation is sticky for a reason. Rents, insurance, medical care, and wages do not fall just because a goods-price shock fades. That is the boring truth behind a lot of fancy forecasts. Add a construction boom around data centers and you get a new twist. Concrete, electricians, transformers, and local housing markets can tighten even if the rest of manufacturing looks mixed.
Is every crane a national inflation event? Of course not. The warning was more precise than that. Watch for spillover. Watch for demand that outruns what the broader economy can absorb. If that spillover shows up in wages and core services, the bond market will not need a speech to reprice. It will just lift the term premium and move on.
Originally inflation was supposed to roll over late last year. Then this year. Then next year. A slipping timetable is itself a signal.
That is why I treat “transitory” as a word that should be earned, not assumed. Markets have been burned by neat stories.
What The Jobs Print Can Change By Lunch
Private payroll estimates can be noisy. They can also set the tone for the rest of the week. A firm number would make this morning’s yield dip look like a false start. A soft number would invite another bid for duration and more chatter about when official rates can finally move. A number that lands right on forecast may leave the curve exactly where it is, which is its own kind of statement: the market already did the work.
I care less about the headline than about the revisions and the wage flavor, when those details exist. Hiring can stay positive while the quality of that hiring deteriorates. Bond traders have learned to look under the hood. You should too, even if you only glance once a month.
Fed Speak Is Not Background Noise
Speeches at a Treasury market conference tend to be more technical than a lunch-time panel. That can be useful. Officials sometimes talk about market functioning, liquidity, and the plumbing that keeps auctions from getting sloppy. When the Treasury market is the subject, a stray sentence about term premium or balance-sheet policy can move the long end faster than a generic inflation paragraph.
The housing speech the next day is a different animal. Affordability is where monetary policy becomes dinner-table policy. If a governor spends time on shelter costs, listeners will hunt for clues about how long restrictive rates need to stay in place. Shelter is a huge slice of consumer inflation. It is also the slice families feel when they scroll listings they cannot bid on.
In my view, the honest risk is not that officials suddenly turn dovish. The honest risk is that they keep repeating the same delayed-disinflation story while oil and services keep the pressure on. Bond investors have heard the story. They want evidence.
| Tenor | Early Tuesday Yield | Change | What It Reflects |
| 2-year note | 4.741% | Down 1 bp | Near-term policy path |
| 10-year note | 4.943% | Down 2 bp | Growth, inflation, mortgages |
| 30-year bond | 5.272% | Down 2 bp | Long-run term premium |
A Quick Word On Price Versus Yield
Every cycle, someone asks why falling yields are described as a rally. Because the price of the existing bond went up. If you already own the note, you had a green morning. If you were waiting to buy, your future income just got a haircut. Both things can be true at once. That is not a contradiction. That is the product.
New buyers should not chase a two-basis-point dip as if it were a clearance sale. They should ask whether 4.9% on the 10-year still compensates them for inflation risk, fiscal supply, and the chance that official rates stay high. For many income investors, the answer is still yes. For traders who need a fast mark-to-market win, the answer depends on the next headline.
Supply, Deficits, And The Unseen Weight On Long Bonds
Even on a quiet Tuesday, the long end lives with a structural question: how much paper is coming. Large deficits mean large auctions. Large auctions mean the market has to clear a lot of duration. That can keep the 30-year yield elevated even when growth worries appear. It is one reason the long bond can ease two basis points and still look historically high.
I do not treat every auction as a crisis. I do treat repeated heavy supply as a reason not to assume that yields will glide back to the old 2% neighborhood just because inflation cools a little. The buyer base has changed. Foreign demand is less automatic. Domestic funds are more price sensitive. That mix supports a higher equilibrium than the one many models still carry in their rearview mirror.
Mortgages, Corporates, And The Quiet Spillover
When the 10-year yield slips, mortgage-backed spreads do not always follow on a one-for-one basis. Sometimes the government bond rally is faster than the credit rally. Sometimes corporates catch a bid because the risk-free rate did the heavy lifting. Tuesday’s early tape was too thin to crown a winner. Still, households and chief financial officers live in that spillover.
A company refinancing five-year paper cares about the belly of the curve. A family locking a 30-year mortgage cares about the long end plus the spread a lender charges for prepayment risk. The headline Treasury yield is the starting line, not the finish line. Anyone quoting “the” rate without the spread is telling half the story.
How To Watch The Rest Of The Session
Forget the urge to predict the exact print. Watch the reaction function.
- If yields fall and then keep falling after the jobs figures, the market is buying a softer labor story.
- If yields bounce the moment the number hits, this morning’s dip was just positioning.
- If oil keeps climbing while bonds also climb, geopolitics is overpowering the inflation impulse for now.
- If officials sound more concerned about services and capacity than about growth, the long end may give back the easing.
That checklist is not fancy. It works. Markets tell you what they believe after the number, not before it.
A Personal Bias, Stated Clearly
I am more patient with high starting yields than I am with forecasts that keep sliding to the right. A 10-year near 5% can be a gift for people who need income and can tolerate price swings. It is less of a gift if inflation in services stays lively and energy adds a second act. The right stance, at least for me, is to own some duration, refuse to bet the house on an imminent easing cycle, and let the data argue.
That sounds cautious because it is cautious. Bond bull markets that begin with “the peak is definitely next quarter” have a habit of arriving late and leaving early.
What “Easing Yields” Does Not Mean
It does not mean inflation is finished. It does not mean official rates are about to be cut at the next meeting. It does not mean the 30-year bond has become cheap or expensive by itself. It means a handful of traders decided, before dawn, that they would rather be a little long than a little short into a data point and a microphone.
Those decisions get rewritten all day. That is the job. The rest of us should take the information and leave the adrenaline on the floor.
Putting The Pieces On One Page
Yields slipped. Jobs data is next. Officials will talk about markets and housing. Oil jumped on a geopolitical headline. A Fed voice warned that inflation’s expected turning point keeps getting postponed and that demand cannot be allowed to overheat. World leaders are in the same city as the trading desks that will digest all of it.
If you only remember one thing, remember this: a two-basis-point move is a weather report, not a climate change. The climate is still a world of high starting yields, sticky services prices, heavy government supply, and an energy market that can reprice in an afternoon. That climate can still reward patient income investors. It can punish anyone who treats a quiet Tuesday morning as proof that the hard part is over.
So yes, I will keep checking yields before the weather. The sky will do what it does. The 10-year note will keep telling a more expensive story about what money is worth, and for how long. On a morning like this, that story eased. It did not end. The next chapter arrives with the jobs figures, the speeches, and whatever crude does after the open. That is the part worth staying awake for.