
Ever watch a market that spent days climbing a wall, then quietly step off the ledge before most people have finished their coffee? That is roughly how Monday’s bond tape felt. Treasury yields eased as global borrowing costs tumbled, and the move looked small on a screen until you remembered where the 10-year note had been sitting only a few sessions earlier.
What Monday’s Yield Drop Actually Signaled
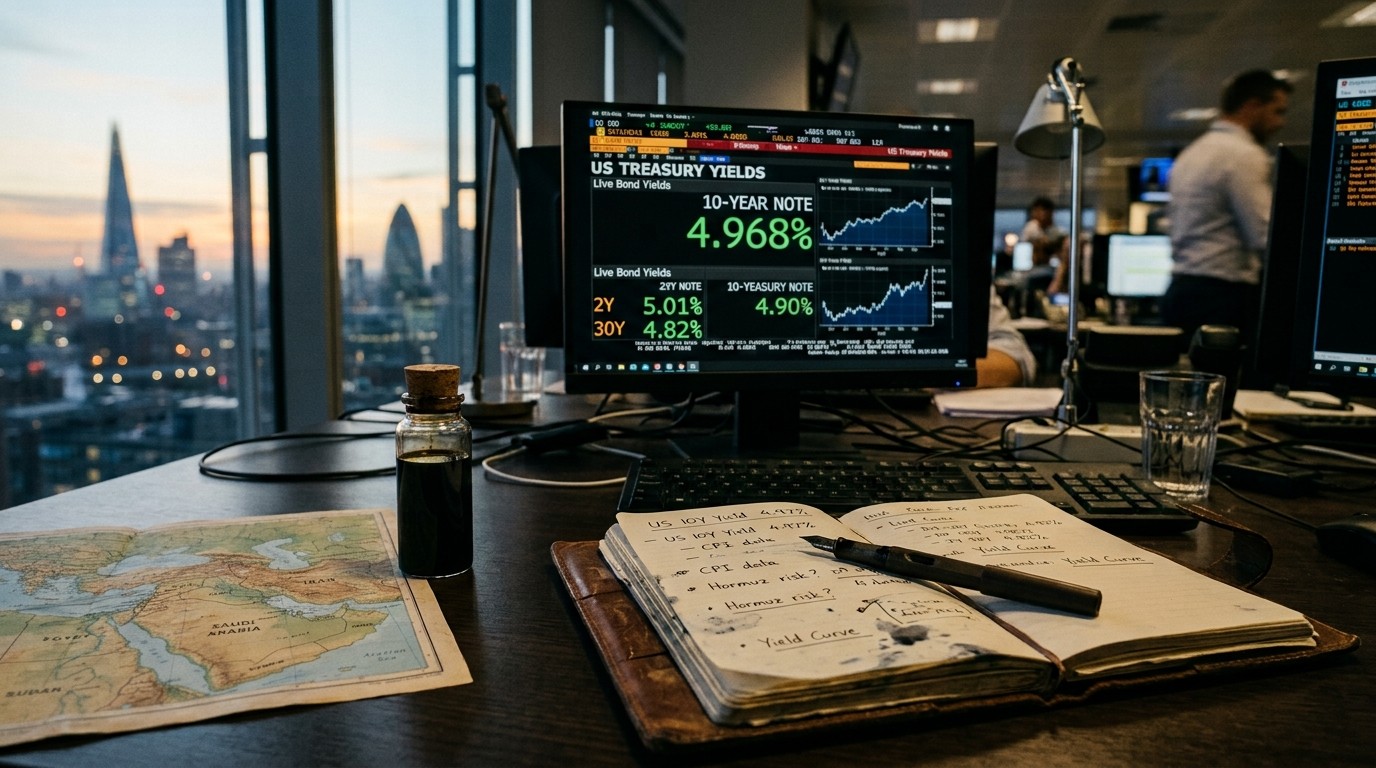
The benchmark 10-year Treasury yield slipped by about three basis points to 4.967%. Last week it had printed 5.041%, a level that sent a lot of people digging through old charts. A basis point is one hundredth of a percent. Yields and prices still move in opposite directions, which is the part newcomers keep having to relearn when headlines flip from “rates up” to “bonds bid.”
The 2-year note was barely softer, down around one basis point at 4.729%. The 30-year bond yield fell three basis points to 5.306%. That is not a collapse. It is a pause with a pulse. I’ve found that the market often does its most honest work in these modest sessions, when nobody is forced to invent a narrative bigger than the numbers.
Europe joined the easing. The German 10-year bund, the euro area’s reference bond, dropped about five basis points. U.K. 10-year gilts did the same. Japanese markets were closed, which matters more than it sounds. Tokyo has become a kind of global metronome for duration. When that clock stops for a holiday, the rest of the orchestra still plays, just a little off-tempo.
Yields and prices move in opposite directions. Forget that for five minutes and the whole story reads backward.
Oil Prices Set The Mood More Than Headlines Did
Sentiment got a lift from cheaper crude. Equities pushed higher even while fighting in the Middle East continued. That pairing always looks strange until you remember how energy feeds inflation expectations, and how inflation expectations feed the discount rate that sits inside every bond.
If oil cools, the market can tell itself a simpler story: maybe the next stretch of inflation data will not be as hot as the last one. Maybe the path of policy rates is a little less steep. Maybe long-duration paper does not need quite as much yield to compensate for the risk of being paid back in weaker money. None of that is guaranteed. It is just the mental shortcut traders use when a barrel of oil is cheaper than it was on Friday.
There is still a geopolitical overlay that refuses to stay in the background. Diplomacy sits high on the calendar as leaders gather for the United Nations General Assembly. Washington has also turned up the pressure on Tehran over a deal that could ease trade through the Strait of Hormuz. That waterway is not a trivia fact. It is a choke point. When markets talk about “trade flows,” they are talking about whether tankers can pass without the world repricing energy overnight.
In my experience, energy shocks do not need to become full-blown crises to move bonds. They only need to keep the option of a crisis alive. Monday’s oil dip trimmed that option premium, at least for a session.
The Federal Reserve Hike Is Still Being Digested
Investors are still chewing on last week’s quarter-point increase from the Federal Reserve. The question is not whether the hike happened. It did. The question is whether another one shows up before year-end. Markets love a clean map. Policy makers keep handing them a sketch.
The European Central Bank also raised rates this month. The Bank of England chose a hold last week. Three major central banks, three slightly different postures, one shared problem: inflation that has been stubborn enough to keep official rates high, and growth that is uneven enough to make the next step feel dangerous.
That mix is why a three-basis-point dip in the 10-year can feel like news. After a 19-year high, even a small retreat looks like the market asking for a second opinion. Perhaps the most interesting aspect is how little the front end moved. The 2-year is usually the note that lives closest to policy. If it barely budges while the long end eases, you are looking at a curve that is whispering about growth and term premium more than about an imminent cut.
- A 10-year yield near 4.97% still prices a world of tight financial conditions.
- A 2-year near 4.73% still treats policy as restrictive, not finished.
- A 30-year near 5.31% still demands a real premium for locking money away for decades.
Those levels are not “cheap” in the casual sense. They are simply less expensive than they were at last week’s peak. Language matters here. A rally in bonds is a fall in yields. A fall in yields is a rise in prices. If you write that sentence three times, it starts to stick.
Why Global Borrowing Costs Moved Together
Government bonds do not live in separate rooms. When U.S. yields jump, foreign debt often follows because capital can move, because inflation can travel, and because relative value desks never sleep. When U.S. yields ease, the same pipes work in reverse, at least until local politics or local inflation data slam the valve shut.
Germany and the United Kingdom easing by five basis points on the same morning as Treasuries is not a coincidence. It is correlation doing what correlation does. Cross-border investors compare real yields, swap spreads, and the simple question of where they get paid for duration. If oil is softer and risk appetite is a touch better, the bid can show up in more than one capital at once.
Japan being closed removed a usual source of flow commentary. That absence is easy to ignore until you remember how often Tokyo sessions set the tone for U.S. futures. A quiet Asia desk does not cancel the story. It just leaves fewer fingerprints on it.
What The Calendar Will Test This Week
Data will not wait for the bond market to finish its mood swing. S&P Global Purchasing Managers’ Index figures land on Wednesday. Initial jobless claims arrive on Thursday. In between, speeches from New York Fed President John Williams, Richmond Fed President Tom Barkin, and other officials will be parsed for commas.
PMI prints are not poetry. They are temperature checks on factories and services. A hot reading can revive the “higher for longer” line. A soft reading can feed the idea that last week’s peak in the 10-year was an exhaustion point rather than a new floor. Claims work the same way on the labor side. One week never settles an argument. A trend can.
Official speeches are a different sport. After a hike, every adjective gets weighed. “Restrictive” versus “sufficiently restrictive.” “Ready to act” versus “data dependent.” I’ve sat through enough of these cycles to know the market often hears what it wants. That does not make the words useless. It makes them a Rorschach test with a press secretary.
| Item | Timing | Why Bonds Care |
| PMI surveys | Wednesday | Growth pulse and pricing power clues |
| Jobless claims | Thursday | Labor tightness versus cooling |
| Fed speakers | Through the week | Hints on another hike before year-end |
| Energy tape | Every session | Inflation expectations and risk premia |
How To Read A 19-Year High Without Getting Dizzy
A 19-year high in the 10-year yield is a headline that does real work. It tells you the cost of long-term money has not looked like this since a different era of deficits, demographics, and inflation memory. It does not tell you the next print must be higher. Markets love round numbers and historical tags. They also love mean reversion when a move gets crowded.
Think of last week’s 5.041% as a weather report, not a verdict. Heat arrived. Some of it came from policy. Some of it came from supply of government paper. Some of it came from investors demanding more compensation for uncertainty. Monday’s slip to 4.967% is a cloud passing over that heat. Maybe the temperature breaks. Maybe it does not.
Households feel this in mortgage quotes. Companies feel it in refinancing calendars. Governments feel it every time they roll debt. That is why “borrowing costs” is not a Wall Street-only phrase. It is the price of time. When that price jumps, plans shrink. When it eases, plans get dusted off. The change does not have to be dramatic to change behavior at the margin.
Stocks Rose, Bonds Caught A Bid, And The Mix Felt Familiar
Equity markets moving higher on cheaper oil while yields ease is a classic risk-on pairing, with a caveat. True risk-on usually wants credit spreads tighter, volatility lower, and a curve that is not screaming recession. Monday offered pieces of that picture, not the whole canvas.
There is a version of this tape that is simply mechanical. Oil down, inflation fears down a notch, discount rates down a notch, stock multiples breathe. There is another version where geopolitics is only napping. If shipping risk returns in the Strait of Hormuz, energy can reprice faster than a PMI survey can soothe anyone.
That is why I keep coming back to the idea of optionality. Markets are not only pricing the base case. They are pricing the chance of a worse case. When that chance looks smaller for a morning, yields can fall three basis points and everybody can write a tidy recap. The tidy recap is the dangerous part. The world rarely stays tidy until Friday.
A small yield decline after a multi-year peak is less a celebration than a question: was that the high, or just a high?
The Curve Still Has A Story To Tell
Look at the three points we have. Two-year at 4.729%. Ten-year at 4.967%. Thirty-year at 5.306%. The curve is not a dramatic inversion in those snapshots, and it is not a steep bullish mountain either. It is a market that still wants to be paid for time, just a little less urgently than last week.
Curve watchers will argue about term premium, about foreign buying, about coupon supply. Fine. Those debates are real. For a general reader, the practical point is simpler. Short rates are anchored by the Fed. Long rates are anchored by growth, inflation, and how much paper the Treasury needs to sell. When those forces pull in different directions, the middle of the curve becomes a tug-of-war.
Monday’s modest flattening-or-easing mix, depending on which pair you watch, fits a market that is not ready to declare victory on inflation and not ready to panic about growth. That in-between zone is where a lot of money gets bored and a lot of money gets hurt. Boredom is underrated as a risk.
Central Banks Are Not Marching In Lockstep
The Fed hiked. The ECB hiked this month. The Bank of England held. That split is easy to flatten into a single “global tightening” slogan. It should not be flattened. Domestic inflation paths differ. Labor markets differ. Political tolerance for higher mortgage rates differs. Currency effects differ.
Still, the direction of travel has been the same for a long stretch: official rates far above the emergency lows of the last cycle. Markets now live in the messy last mile. Last miles produce false peaks in yields and false dawns in risk assets. If that sounds like a hedge, good. It is meant to.
When officials speak this week, listen less for a secret rate path and more for how they describe the balance of risks. Are they more worried about doing too little on prices or too much on jobs? That emphasis tends to leak into the 2-year first and the 10-year second.
Energy, Diplomacy, And The Bond Market’s Short Memory
Hostilities in the Middle East did not vanish because crude slipped. They simply stopped dominating the intraday narrative for a few hours. Diplomacy at the United Nations can look ceremonial until it is not. Pressure over Hormuz can look like talking points until a shipping insurer changes a premium.
Bonds have a short memory for geopolitics when the oil number cooperates. They have a long memory when it does not. That is not cynicism. It is cash-flow math. Energy is an input. Inputs become consumer prices. Consumer prices become wage talks. Wage talks become core inflation. Core inflation becomes the term premium. You can skip steps in a column. You cannot skip them in a supply chain.
So yes, Monday felt calmer. Calmer is not closed.
What Everyday Borrowers Should Take From A Three-Basis-Point Move
If you are not a trader, three basis points can sound like noise. Fair. You will not refinance a house because the 10-year yielded 4.967% instead of 4.997%. You might, however, use the week as a reminder to separate headline yields from the rate you are actually offered.
Mortgage spreads, credit-card APRs, and corporate coupons do not move one-for-one with Treasuries. They move with Treasuries plus a pile of other stuff: bank funding, risk appetite, regulation, and the simple willingness of lenders to compete. A global easing in government borrowing costs is a tailwind. It is not an automatic discount at the branch.
- Watch the 10-year as a benchmark, not a personal quote.
- Watch oil if your budget or your industry eats energy.
- Watch claims and PMI if you care whether the hiking cycle has another chapter.
- Watch official language for whether “further rises” stay on the table.
That list is not exciting. It is usable. Exciting market writing often fails the usable test.
A Practical Way To Think About Duration Right Now
Duration is just sensitivity to yield changes. Longer bonds jump around more when yields move. After a 19-year high, some investors want to reach for that longer paper because the coupon looks generous next to cash from a few years ago. Others want to stay short because they think another hike, or another inflation scare, is still in the deck.
Neither camp has a monopoly on sense. The honest middle is ugly and adult: size positions so that a return trip toward 5% on the 10-year does not force a sale at the worst moment, and so that a drift toward the mid-4s does not leave you earning nothing but regret.
I have a bias, and I will own it. After a spike that grabs a historical label, I would rather add duration slowly than all at once. Markets can stay expensive to borrowers longer than a catchy recap can stay accurate. That is not a forecast of 6%. It is a respect for how sticky official rates have been.
The Difference Between A Tumble And A Dip
The phrase “global borrowing costs tumble” does useful work in a headline. In the actual numbers, Monday was more dip than tumble. Five basis points in Europe is notable. Three in the U.S. long end is noticeable. One in the 2-year is a shrug with a pulse.
Why lean on the stronger verb at all? Because context is the multiplier. Coming off 5.041%, even a modest retreat feels like air after a climb. The market is allowed to exhale without calling it a regime change. Readers should be allowed the same courtesy.
If Wednesday’s surveys come in hot, that exhale can reverse before the week is done. If claims jump and speakers sound cautious, the bid for duration can build. Either path would still sit inside the same larger story: policy rates are high, energy is a swing factor, and diplomacy around a critical shipping lane is not a side quest.
How Professional Desks Will Frame The Session
On a desk, Monday gets filed under “follow-through after a yield spike, helped by oil.” The note to clients will mention Europe’s larger move, Japan’s holiday, the Fed hangover, and the week’s data. Somebody will mention the curve. Somebody else will mention supply. A third person will mention positioning, which is the polite word for “we might be crowded.”
None of that is wrong. It is incomplete if it skips the human layer. Pension funds, insurers, and households do not mark to market the way a relative-value book does. They feel higher yields as a better entry for new money and a worse mark for old holdings. Both feelings can be true in the same building.
Monday snapshot, plain language:
  10-year: eased about 3 bp to 4.967%
  2-year: eased about 1 bp to 4.729%
  30-year: eased about 3 bp to 5.306%
  Bunds and gilts: about 5 bp lower
  Oil: softer, equities firmer
  Japan: closed
Why This Still Matters After The Screens Go Dark
Bond yields are the quiet plumbing of modern finance. They set discount rates for stocks, hurdle rates for projects, and the mood music for housing. When they ease after a long climb, it is tempting to write a victory lap. When they spike, it is tempting to write an obituary for risk assets. Both temptations should be resisted.
The better habit is slower. Ask what oil is doing to inflation expectations. Ask whether the Fed still has another hike in its pocket. Ask whether Europe’s larger yield drop is leadership or just a catch-up. Ask whether Hormuz risk is priced or merely paused. Then look at Wednesday and Thursday before you decide Monday was a turning point.
Turning points usually announce themselves later than we want and earlier than we admit. That sentence is not clever. It is just how these cycles tend to feel when you have watched a few of them without the benefit of a perfect chart in hindsight.
A Closing Read On The Tape
Treasury yields eased. Global government borrowing costs followed, especially in Germany and the United Kingdom. Oil helped. Stocks liked the combination. The Fed hike from last week is still sitting in the room like a guest who has not decided whether to stay for dessert. Officials will talk. Surveys will print. Claims will print. Diplomacy will try to look like progress.
If you only remember one number, remember 4.967% on the 10-year and the 5.041% that preceded it. The gap between those prints is small. The argument inside that gap is not. Is the market done stretching the cost of long-term money for now, or did it simply blink?
I would not bet the week on a blink. I also would not ignore a market that finally found a bid after a 19-year high. Hold both thoughts. Check the energy complex. Listen to Williams and Barkin without treating every clause like a coded hike. And if the 2-year stays sticky while the long end wiggles, take that as a reminder that policy is still the anchor, even when oil writes the opening paragraph.
Monday did not settle the year. It did something more ordinary and, frankly, more useful. It showed that borrowing costs can ease in several countries at once when the inflation scare takes a coffee break. Whether that break lasts will be the real story, and that story is still being written in barrels, in labor forms, and in the careful sentences of people who set interest rates for a living.