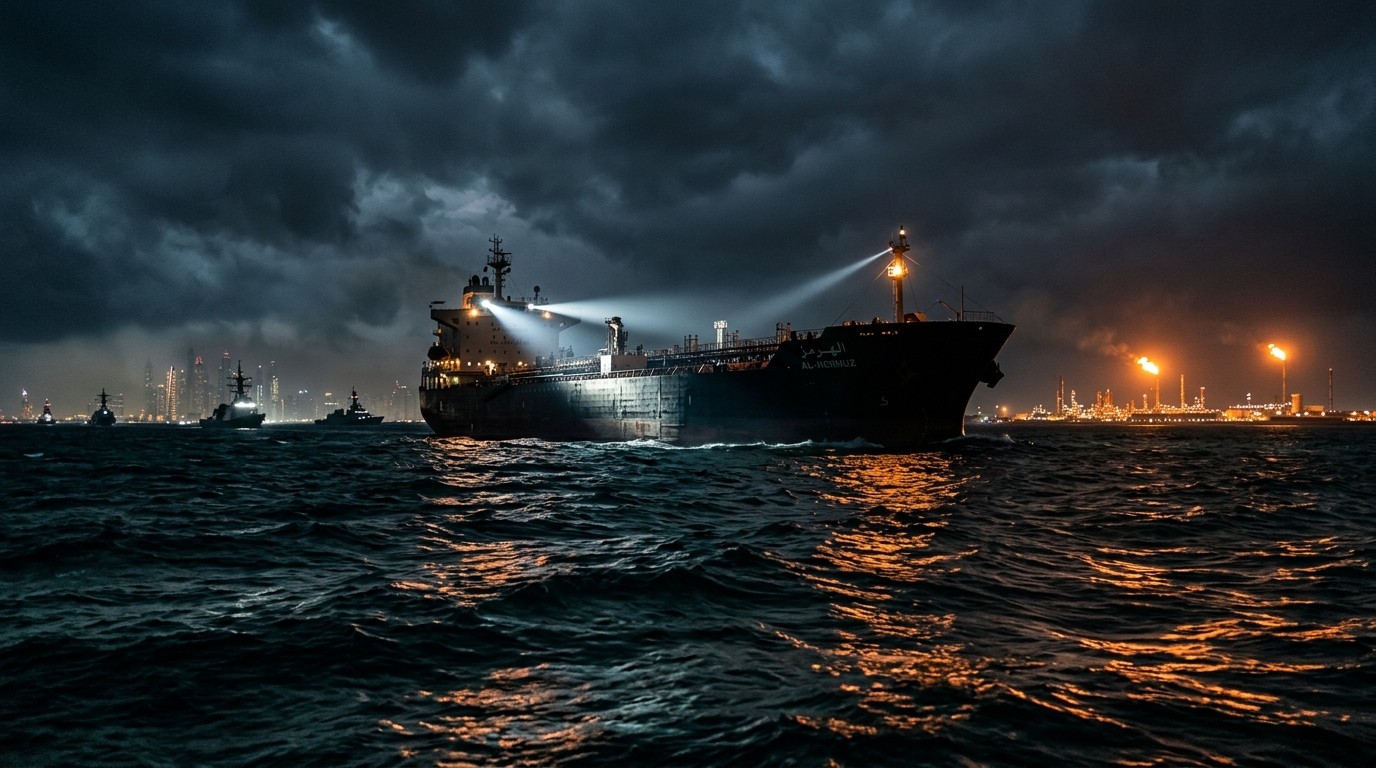

Have you ever watched a market try to price two futures at once? One future looks like a handshake in New York. The other looks like a fire that jumps from port to port. That is where energy traders woke up this week, staring at a president talking about wiping a country out or letting its economy rot, while Iranian commanders promised a painful answer across the region. I have covered enough of these cycles to know the language is rarely accidental. It is meant to squeeze a room before the world’s leaders share the same hallway.
What The Latest Escalation Actually Changes
The seven-month fight did not start this weekend. A June memorandum fell apart. Both sides dug in. Now a diplomatic team led by Iran’s president is heading to the United Nations General Assembly, and the American president told a Sunday television interview that the only options on the table were destruction or decay unless a deal appears. He also said he was in deciding mode. That phrase is doing a lot of work. It keeps every option alive without putting a date on any of them.
Iran’s military, speaking through its central headquarters, said intelligence pointed to a new large-scale strike being prepared by the United States and partners. The warning was blunt. A mistake against the Islamic Republic would bring sustained, effective, and painful attacks on American positions and interests in the region. Countries that backed such a strike would be treated as parties to the conflict. In plain terms, the map just got wider.
If the other side makes any mistake, all its positions and interests in the region will be targeted by sustained, effective and painful attacks.
– Iranian military statement via semi-official media
I do not treat every statement as a countdown clock. Still, the timing is not casual. Sideline meetings are scheduled. The Iranian president will sit with other leaders. The American president said he would be open to a meeting, then added the deciding-mode line. Diplomacy and threat live in the same sentence. Markets hate that mix almost as much as they hate a closed waterway.
Why The United Nations Week Matters More Than The Soundbites
New York in late September is a theater. Leaders walk the same corridors. Cameras wait. Phone calls become meetings, or they do not. A security alert from the State Department told Americans to stay vigilant, watch for flight cancellations, and expect possible airspace closures. That is not a travel blog footnote. That is a government saying the next surprise may not be scheduled.
Houthi militants claimed missile and drone attacks on Riyadh on Saturday. Saudi authorities said they intercepted a ballistic missile. No casualties. No damage reported. It was still the first air-raid alert in the capital since fighting intensified in July. Coalition forces said other attempts against civilians and infrastructure were stopped. When the kingdom’s air defenses become part of the daily tape, oil desks stop pretending this is a contained quarrel.
Perhaps the most interesting aspect is how both capitals are using the calendar. Tehran wants talks only when it feels it has the upper hand on the battlefield. Iran’s parliament speaker said the country must keep fighting and negotiating at the same time, and save softer diplomacy for later. Washington is stacking pressure before the same week of handshakes. I have found that this kind of dual track rarely produces a clean headline. It produces a range.
Oil Prices Are Not Calming Down For The Reason You Think
Brent futures slipped about 1.7 percent to $102.15 a barrel. West Texas Intermediate dropped about 1.8 percent to $98.46. On a screen that looks like relief. In a notebook it looks like a pause. Traders hoped Saudi shipments might recover. They also watched reports of progress moving barrels through the Strait of Hormuz. Progress is not the same as plenty.
A team of political-risk analysts argued that prices will stay high even if more oil sneaks through the strait. Any rebound in flows would not close the overall market deficit. Their working band for Brent through year-end sits roughly between $90 and $110. That is a wide street. It is also a street that keeps inflation sticky and keeps central bankers glancing at the Middle East instead of only at payrolls.
Tehran has said the strait stays closed to its satisfaction until Washington honors the collapsed June memo: lift the naval squeeze on Iranian ports, ease sanctions, unfreeze assets, and stop the military threats. That list is not a footnote. It is the price of a waterway that still carries a huge share of seaborne crude. If you trade energy, you already know the choke point. If you do not, picture a narrow door that the whole neighborhood uses to leave the house.
| Market Signal | Recent Print | What It Implies |
| Brent crude | Near $102 after a 1.7% dip | Soft tape, hard floor |
| WTI crude | Near $98 after a 1.8% dip | U.S. grade still elevated |
| Year-end band (analyst view) | $90–$110 Brent | Deficit outruns a partial reopening |
| Shipping risk | Tanker harassment and proxy strikes | Insurance and delays stay expensive |
In my experience, a one-day dip after a scary weekend is not a regime change in the oil market. It is a breath. The structure still looks tight. Inventories in key hubs have not flashed a surplus large enough to shrug off a missed cargo. Refiners still pay up for certainty. Certainty is scarce when drones fly toward a capital and presidents talk about eliminating leadership.
The Strait, The Proxies, And The Slow Squeeze
Iran does not need to sink every tanker to move the price. It needs enough harassment to keep insurers nervous and captains cautious. Proxy groups can poke at ports, cities, and shipping lanes while official statements stay just short of a formal wider war. That is an old playbook. It still works because markets price probability, not poetry.
- Missile and drone claims against Riyadh raise the political cost for Gulf partners.
- Tanker incidents, even failed ones, lift war-risk premiums.
- A threatened large-scale strike, even if it never launches, freezes some commercial decisions.
- Talk of treating regional backers as combatants expands the list of assets that could be hit.
The United States has tried to keep some oil moving through the strait. Fine. Analysts still say the rebound would not fix the deficit. That sentence should sit on every trading desk this month. Volume coming back is not the same as volume coming back on time, fully insured, and repeatable next week.
Tehran’s internal arguments do not change the external strategy, at least not yet. Leadership, according to the same risk note, will stick with resistance even while factions quarrel. That is a polite way of saying do not wait for a sudden soft landing just because two officials disagree on television.
How A Deal Could Look Without Anyone Calling It A Deal
Nobody has to sign a thick treaty on camera. A quieter package can still move barrels. Think sequenced steps. A pause in certain threats. A measured reopening of lanes. A partial unfreeze that can be reversed. The June memo already sketched the outline: ports, sanctions, assets, military language. The collapse of that memo is why we are here. Rebuilding it in public may be impossible. Rebuilding it in pieces may not be.
Would a hallway conversation in New York be enough? Maybe not. It could still change the tone of the next seventy-two hours. I have watched thinner conversations move front-month crude by several dollars when the alternative was a weekend of drones. The bar is not peace. The bar is fewer surprises before inventories are counted again.
Iran must keep fighting and negotiating, and only lean on diplomacy when it holds the advantage on the ground.
– Iranian parliamentary leadership, paraphrased from weekend remarks
That stance makes a clean bargain harder. It also makes a messy bargain more likely. Messy bargains are what oil markets actually trade. They do not wait for perfect language. They wait for a tanker that sails without a new siren.
What Households And Investors Should Watch This Week
If you do not sit on a crude desk, this still reaches you. Gasoline, jet fuel, and heating oil all drink from the same well of risk. A higher band for Brent through December is not an abstract chart. It is a budget line. Airlines hedge. Truckers pass costs. Central banks keep one eye on energy even when they talk about services inflation.
- Listen for any confirmed contact between the two presidents on the sidelines.
- Track whether Houthi or other proxy attacks widen beyond intercepted shots.
- Watch freight and insurance quotes on Middle East loadings, not just the headline barrel price.
- Note official language about the strait. Reopening talk without verification is just talk.
- Treat a sharp one-day drop in crude as a question, not an answer.
Equity investors should not pretend energy is a side character. Integrated majors, refiners, and some shippers live on these headlines. So do airlines and chemicals on the other side of the cost ledger. A $90 to $110 Brent world is a different operating environment than a $70 world. You do not need a war-game model to see that. You need a calendar and a willingness to admit the deficit is still the deficit.
The Human Tone Behind The Strategic Noise
It is easy to flatten this into two men and a map. That is lazy. There are crews on tankers who would rather not become a symbol. There are families in cities that heard air-raid sirens for the first time in months. There are diplomats who will smile for a photo and then argue over a clause that decides whether a port opens. I keep coming back to that because markets forget the people until a price spike reminds them.
Is the rhetoric theater? Some of it, sure. Theater can still burn a set. When a leader says the choices are wipeout or rot, allies hear a warning and adversaries hear a dare. When commanders promise painful, sustained hits on every regional interest, insurers hear a surcharge. Words move money long before missiles do.
I will say this plainly. A meeting that produces only a bland communique would still be better than a week of unanswered threats. Ambiguity is expensive. Clarity, even ugly clarity, lets people plan. Right now planning looks like extra inventory, extra hedges, and extra caution on any route that kisses the Gulf.
A Closer Look At The June Breakdown
The memorandum that failed in June was not poetry. It was a checklist. Naval pressure off Iranian ports would ease. Sanctions would loosen in defined ways. Frozen assets would start to move. Military threats would be dialed down. In return, shipping through the strait would stop being a daily gamble. When that bargain died, each side returned to the tool it trusts. Washington reached for isolation and force language. Tehran reached for proxies and the waterway.
Why does that history matter this week? Because every New York conversation will be measured against that checklist. If officials only recycle the old points, traders will treat the assembly as scenery. If even one item on the list twitches, the front month will notice. Markets are rude that way. They do not clap for speeches. They clap for barrels.
Some readers will ask whether domestic politics inside Iran change the math. Factional noise is real. It rarely cancels the external posture overnight. Resistance as a brand is sticky. That does not mean a tactical pause is impossible. It means a pause will be sold at home as strength, not surrender. Language will stay sharp even if tankers start moving again.
Energy Balances, Not Just Headlines
Strip away the quotes and you still have a physical market. Spare capacity among big producers is not infinite. Strategic stocks can be used, then they need to be refilled. Refinery maintenance windows do not care about summit schedules. When analysts say a rebound in Hormuz flows would not erase the deficit, they are doing arithmetic, not punditry.
Simple way to hold the picture:
  Tight balances
  + proxy risk
  + political deadlines
  = a high, wide price band
Not a single magic number.
That is why $102 Brent after a down day is not cheap. Cheap is relative. Relative to last month’s panic, maybe. Relative to a world that needs more barrels than it is comfortably getting, not really. I keep repeating the band because bands are how grown-ups plan. Point forecasts make good television. Bands make better budgets.
Regional Partners And The Wider Blast Radius
Saudi air defenses worked on Saturday, according to official accounts. Good. Working once is not the same as working every night. The warning from Iranian command that regional backers of a strike would be treated as parties to the war is the sentence that should keep defense ministries awake. It turns a bilateral crisis into a neighborhood problem.
Gulf energy infrastructure is concentrated. That is not a secret. It is a map. When militants say they aimed at civilians and infrastructure in several parts of the kingdom, even failed attempts change the risk model. Ports, pipelines, and export terminals do not need to be destroyed to matter. They need to be doubted.
American positions in the region are numerous enough that “all interests” is a long list. Bases, logistics hubs, contractors, and commercial affiliates sit inside that phrase. A campaign described as sustained and painful is designed to sound open-ended. Open-ended campaigns are hard to price and easy to fear.
What A Responsible Reader Should Not Do
Do not treat a television quote as an order that has already been signed. Do not treat an intercepted missile as proof that the next one will also miss. Do not assume New York automatically produces a thaw. Do not assume it produces a smash either. The honest stance is uncomfortable: elevated odds of both a corridor conversation and a sharper incident, living side by side.
Also, skip the fantasy that oil can ignore politics because “the market is efficient.” Efficiency includes fear. Fear is information. When freight rates twitch and flight advisories appear, that is the market doing its job. You can dislike the job and still read the tape.
A Practical Framework For The Next Ten Days
Think in three layers. Layer one is diplomacy visible in New York. Layer two is kinetic activity in the Gulf and the Red Sea approaches. Layer three is the physical movement of crude and products. All three can diverge for a day. They rarely diverge for a month without the price catching up.
- Diplomatic layer: meetings, tone, any hint of sequenced steps on ports and sanctions.
- Security layer: alerts, intercepts, claims of new strike preparations.
- Commodity layer: loadings, delays, insurance, the $90–$110 conversation.
If layer one improves and layer two stays hot, crude may chop. If layer two cools even a little, the dip you saw this week can extend. If layer two heats up while New York smiles, the smile will not last on the screen. That is not cynicism. That is how these weeks usually travel.
Why I Keep Returning To Language
Wipe out. Rot. Painful. Deciding mode. These are not technical terms. They are pressure tools. In a negotiation, extreme language can create room for a smaller landing. It can also box a leader in. Once a public has heard wipe out, a modest bargain can look like a climb-down. That is the trap. Both capitals know it. Both may walk into it anyway because walking away looks weaker in the short run.
Readers sometimes want a hero and a villain. Markets want a schedule. The schedule this week is crowded: assembly speeches, sideline sit-downs, security notices, and a crude market that already used up some of its panic and still refuses to look cheap. If that sounds unfinished, it is. Unfinished is the honest ending until a ship sails or a door slams.
So here is where I land, without pretending to hold a secret cable. The threats are real enough to keep risk premia in the barrel. The diplomacy is real enough to keep a meeting on the table. The oil balance is tight enough that neither words nor a partial reopening automatically delivers cheap energy. Watch the hallway in New York. Watch the water in the Gulf. And do not confuse a Monday pullback with a new era. The era is still the one where a narrow strait and a loud week can reroute the year’s price path before anyone writes the final communique.