
Have you ever wondered what happens when a major Asian economy decides the world’s busiest energy chokepoint is simply too risky to keep relying on? That quiet shift just got a very public spotlight. A long-planned project in Alaska suddenly finds itself at the center of a multi-decade energy commitment that could rewrite how certain countries think about natural gas imports for a generation.
Why Alaska Suddenly Looks Like the Safer Bet
The announcement landed with the kind of bold language that tends to grab headlines. A substantial offtake arrangement from Taiwan covering roughly thirty percent of planned output for twenty years, plus an equity stake measured in the billions. On paper it sounds straightforward. In practice it signals something deeper about how energy buyers are rethinking risk.
I’ve followed energy infrastructure stories for years, and this one stands out because it ties together three things that rarely align so cleanly: political will, commercial interest, and a genuine geographic advantage. Alaska’s North Slope holds vast natural gas reserves that have sat underutilized for decades. Moving that gas south to a coastal liquefaction plant and then shipping it across the Pacific avoids the most congested and politically sensitive waterways on the planet. That alone changes the risk calculus for any importer worried about sudden disruptions.
The Core Numbers Behind the Commitment
Let’s look at the scale without getting lost in jargon. The project itself has been described as a fifty-billion-dollar infrastructure effort. Taiwan’s reported interest involves purchasing around six million tons of liquefied natural gas each year once operations begin. Deliveries are projected to start as early as the early 2030s if construction stays on track. On top of the volume commitment sits an equity investment of several billion dollars, turning Taiwan into both a customer and a stakeholder.
That dual role matters. When a buyer puts real capital into the upstream side of a project, incentives stay aligned for a long time. It’s not just a purchase contract that can be renegotiated or walked away from when prices swing. It’s a deeper partnership. South Korea had earlier signaled interest in the same development, though later comments suggested any participation would hinge on commercial viability. Taiwan’s move appears more concrete at this stage, even while officials note that final binding terms are still under discussion.
Securing long-term volumes from a source that never has to navigate the most contested maritime corridor in the world is the kind of quiet insurance policy energy planners dream about.
In my experience watching these deals, the non-binding stage often lasts longer than outsiders expect. Letters of intent get signed, ministries issue statements, and then the lawyers and commercial teams grind through the details. The public announcement still carries weight because it signals intent at the highest levels.
Geography as Strategy
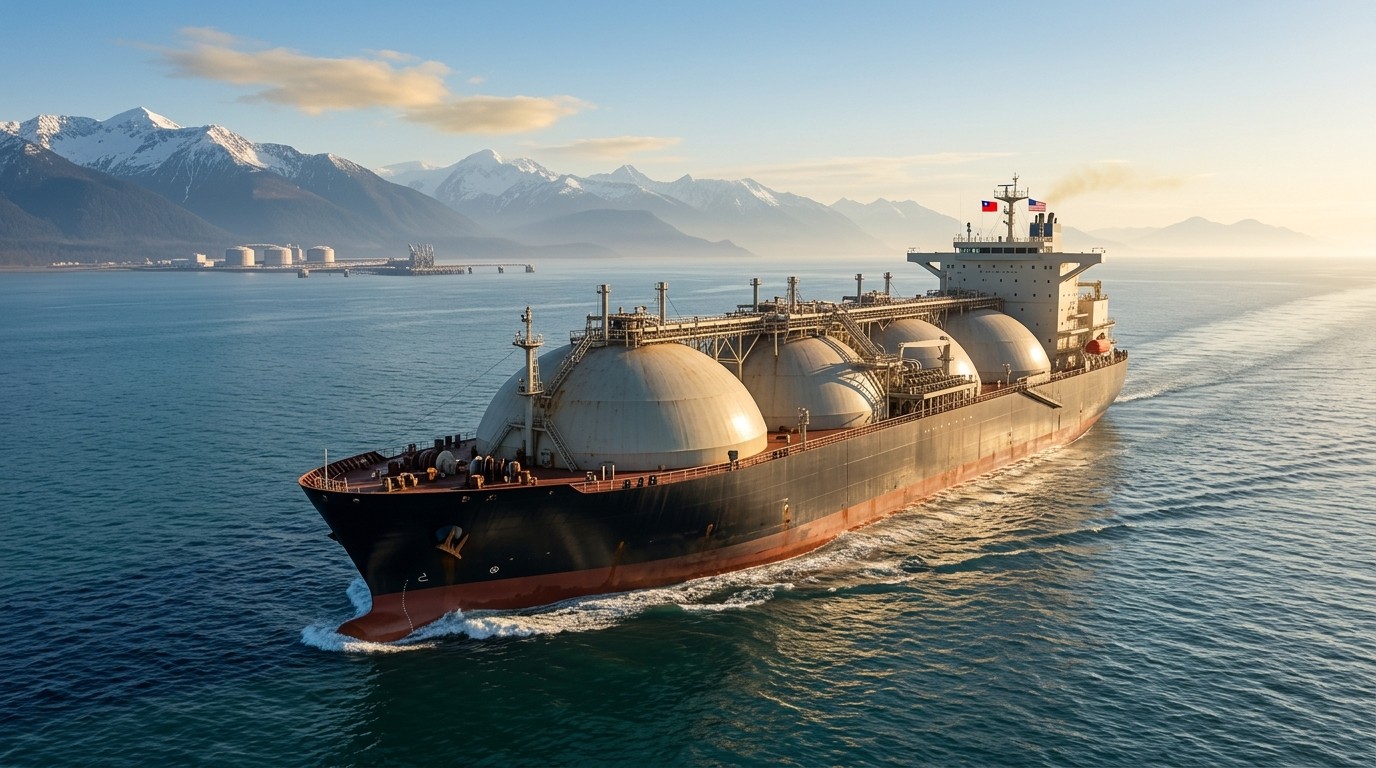
Think about the usual route for Middle Eastern LNG headed to East Asia. Tankers must pass through the Strait of Hormuz, a narrow passage that has seen tension flare more than once in recent memory. Any prolonged interruption there immediately tightens global supply and spikes prices. Alaska offers a completely different map. Gas leaves the North Slope, travels by pipeline to a southern terminal, gets liquefied, and then sails across the open Pacific. No narrow straits controlled by rival powers. No single point of failure that can halt dozens of vessels at once.
That geographic simplicity is the quiet star of this story. For Taiwan, whose energy imports already face unique logistical challenges, the appeal is obvious. Diversifying away from routes that can be disrupted by distant conflicts is not just smart planning. It’s basic resilience. The same logic applies to other Asian buyers who have watched recent events and started asking harder questions about concentration risk.
Perhaps the most interesting aspect is how this project sits at the intersection of domestic U.S. development goals and international energy security needs. Turning stranded Alaskan gas into an export commodity creates jobs, tax revenue, and infrastructure that also serves local customers. At the same time it gives Asian partners a new, politically stable source. When those two interests line up, momentum tends to build.
What the Timeline Really Looks Like
Large energy projects rarely move as fast as the announcements suggest. Permits may be in hand and federal support may be visible, yet construction of a multi-hundred-mile pipeline and a full-scale liquefaction plant still takes years. Early 2030s remains the optimistic target for first cargoes. Between now and then, financing must close, engineering must advance, and market conditions must stay supportive enough to keep equity partners engaged.
I’ve seen similar timelines slip before. Commodity prices can soften, cost estimates can rise, and political priorities can shift. The difference this time appears to be the combination of high-level political backing and the structural demand for non-Middle East volumes. That combination has a better chance of surviving the inevitable delays than a purely commercial project without strategic urgency.
- Pipeline construction from the North Slope to the southern coast remains the longest critical path item.
- Liquefaction capacity must match the offtake volumes already under discussion.
- Shipping logistics across the Pacific are comparatively straightforward once the gas is liquid.
- Local Alaskan demand will also need to be balanced against export volumes.
Each of those pieces carries its own set of engineering and commercial questions. None of them are unsolvable, but all of them require steady execution over a multi-year period.
Broader Implications for Global Energy Flows
Step back from the specific deal and the pattern becomes clearer. Major importers are actively looking for supply sources that sit outside traditional risk corridors. Australia has long played that role for many Asian buyers. North American projects on both coasts are expanding that option set. Alaska adds a northern Pacific route that has been discussed for decades yet rarely moved forward at this scale.
The result, if the project reaches completion, is a more diversified map of LNG trade. Less concentration in a handful of Middle Eastern exporters. More optionality for buyers who can switch sources when one region faces trouble. That kind of flexibility has real value during periods of geopolitical stress. It also tends to moderate price spikes because supply can be redirected more easily.
Of course diversification cuts both ways. New projects need sustained demand to justify their capital costs. If too many similar developments come online at once, the market can soften. Balancing those forces is part of the ongoing conversation among energy planners and investors. Right now the demand side from Asia still looks robust enough to support additional Pacific capacity, especially volumes that carry lower transit risk.
Investment Angle and Commercial Realities
From an investment perspective the equity stake is the most intriguing piece. Putting several billion dollars into a U.S. energy infrastructure project gives the investor both a claim on future cash flows and a measure of influence over development decisions. It also signals confidence that the project will clear the remaining commercial hurdles. State-owned entities often take these positions when the strategic value outweighs pure financial return calculations.
Still, commercial viability remains the gatekeeper. Earlier signals from another major Asian economy showed how quickly interest can become conditional once the numbers are examined more closely. Taiwan’s ministry has been careful to note that binding terms are still under negotiation. That caution is healthy. Long-term offtake contracts must balance price, volume flexibility, and destination rights in ways that work for both sides across commodity cycles.
In my view the most durable deals are those that leave room for adjustment when markets move. Rigid twenty-year contracts can become burdensome for one party or the other. Building in reasonable flexibility while still providing the volume certainty a project needs is the art of these negotiations. The public announcements give a sense of direction; the private term sheets will determine whether the partnership actually endures.
Historical Context of Alaskan Gas Ambitions
Alaska’s gas resources have been known for a long time. The challenge has always been getting the molecules to market at a cost that competes with other global suppliers. Earlier proposals faced higher capital costs, uncertain demand, and shifting political support. What feels different now is the combination of higher global awareness of transit risks and clearer federal backing for domestic energy infrastructure.
Past cycles taught investors that remote projects need strong offtake commitments before capital is fully committed. The current structure appears to be learning that lesson. Securing substantial long-term buyers before final investment decision reduces the risk that the project becomes stranded midway through construction. That sequencing is smarter than the pure build-it-and-they-will-come approach that sometimes characterized earlier attempts.
Local benefits also matter more than outsiders sometimes realize. Alaskan communities stand to gain from construction employment, ongoing operations jobs, and tax revenues. Balancing those local interests with export priorities is part of the political management required for a project of this size. When done well, that balance creates a broader constituency of support that helps the development weather inevitable challenges.
Risk Factors That Still Need Watching
No energy project of this magnitude moves forward without risks. Cost inflation remains a constant concern on large infrastructure builds. Labor availability in remote regions can tighten. Environmental reviews, even when permits are already secured, can face renewed challenges. Commodity price cycles can change the economics for equity partners. And of course political leadership can shift, altering the level of federal support.
On the demand side, Taiwan’s energy mix continues to evolve. Nuclear policy, renewable growth, and industrial demand all influence how much LNG will be required two decades from now. Contracts can include flexibility mechanisms, yet the baseline assumption of steady offtake still needs to hold for the project economics to work. Monitoring those longer-term demand trends will be essential for anyone following the story.
Shipping and logistics introduce another layer. While the Pacific route avoids certain chokepoints, it still requires reliable tanker availability and navigational safety across vast distances. Those are manageable risks compared with the alternative, yet they are not zero. Insurance costs, weather patterns, and fleet capacity all factor into the landed cost of the gas.
How This Fits Into Wider Energy Transition Talks
Some observers will ask how a large new fossil fuel project fits with global decarbonization goals. The honest answer is that natural gas continues to play a bridging role in many Asian energy systems. It displaces higher-emitting coal in power generation and provides flexible backup as renewable capacity grows. For countries that lack abundant domestic resources, imported LNG remains a practical tool for maintaining reliability while emissions intensity declines over time.
That does not make every new project automatic. Each one still needs to demonstrate commercial and environmental responsibility. Modern liquefaction plants are far more efficient than earlier generations. Methane monitoring and leak reduction technologies continue to improve. The projects that succeed long term will be those that treat emissions performance as a core operating metric rather than an afterthought.
From a pure security perspective, however, the case for diversified supply routes remains strong regardless of the broader transition trajectory. Energy systems that depend on a single vulnerable corridor create systemic risk that no amount of renewable growth can fully eliminate in the near term. Having an additional stable source available strengthens the overall system.
What Success Would Actually Look Like
If the project reaches commercial operation on something close to the current schedule, several outcomes become likely. Taiwan gains a meaningful volume of LNG that never has to transit the most contested waterway in global energy trade. Alaska gains a large new industrial development that monetizes previously stranded resources. The United States gains another outlet for domestic energy production and deeper commercial ties with key partners in Asia.
Secondary effects could include more interest from other buyers once the first cargoes demonstrate reliability. Additional equity partners might join if the initial structure proves sound. Local infrastructure upgrades that support the project could benefit other industries in the region. Those ripple effects are harder to quantify in advance yet often prove significant over a twenty-year horizon.
Failure modes are equally clear. If binding agreements never materialize, or if costs escalate beyond commercial tolerance, the project could stall again as earlier versions did. In that case the strategic logic remains, but the practical pathway closes for another cycle. Energy markets have seen that pattern before. The difference this time is the heightened awareness of transit risk, which may keep the conversation alive longer than in previous decades.
A Personal Take on the Strategic Shift
Watching energy markets for a long time teaches you that geography still matters more than most people admit. Pipelines and shipping lanes are not abstract lines on a map. They are physical constraints that shape prices, reliability, and political leverage. When a major buyer decides to lock in volumes that completely avoid the highest-risk corridor, that decision reveals a deeper judgment about the future.
I find the equity component especially telling. It is one thing to sign a purchase contract. It is another to put capital into the development itself. That move suggests the buyer views the project as strategically important enough to accept development risk alongside the supply benefit. In a world where many energy relationships remain purely transactional, this hybrid approach feels more robust.
Of course the story is still unfolding. Negotiations continue. Engineering studies advance. Market conditions evolve. Yet the direction of travel is hard to miss. Buyers with the ability to diversify are doing so. Projects that can offer genuine route diversity are attracting attention they lacked in calmer times. That dynamic is likely to persist even if individual deals take longer to finalize than the initial headlines suggest.
Practical Considerations for Market Watchers
Anyone tracking this development should keep several indicators in view. First, progress on binding offtake and equity agreements. Public statements are useful signals, but signed contracts are the real milestones. Second, updates on project financing and final investment decision timing. Large capital commitments usually come only after commercial foundations are solid. Third, any shifts in the broader Asian LNG demand outlook that could affect volume needs in the 2030s.
Cost reporting will also matter. Early estimates on remote Arctic and sub-Arctic projects have a habit of rising. Transparent communication about budget and schedule helps maintain partner confidence. Finally, political continuity at both ends of the partnership will influence momentum. Energy infrastructure projects that span multiple election cycles need durable bipartisan or multi-party support to reach completion.
- Monitor formalization of the offtake and equity terms.
- Track engineering and permitting milestones that unlock financing.
- Watch competing Pacific LNG projects for signs of oversupply risk.
- Assess changes in Taiwan’s domestic energy policy that could alter import needs.
- Follow local Alaskan stakeholder engagement as a gauge of domestic support.
Those five areas will tell most of the story over the next several years. The rest is execution.
Looking Further Ahead
Twenty years is a long time in energy markets. Technologies change. Demand patterns shift. Geopolitical alignments evolve. A project designed around current realities must still remain relevant across that horizon. The core advantage of a Pacific route free from certain chokepoints is likely to endure. Whether the specific volumes and pricing structures hold up will depend on how well the commercial framework anticipates change.
One quiet possibility is that success here encourages similar thinking elsewhere. Other remote gas resources that once looked uneconomic might attract fresh interest if they can offer comparable route security. Conversely, if this project falters, the lesson may be that even strong strategic logic cannot overcome commercial hurdles without exceptional alignment of interests.
Either outcome will teach something useful. Energy security is not an abstract goal. It is the cumulative result of many individual decisions about where to invest, which routes to trust, and how much concentration risk is acceptable. The current discussion around Alaskan volumes simply makes that calculation more visible than usual.
In the end the story is less about any single announcement and more about a structural shift in how certain buyers evaluate supply options. Conflict-free is a relative term. No energy source is entirely free of risk. Yet some sources clearly carry lower probabilities of sudden interruption than others. Choosing the lower-probability path, even at a potential cost premium, is a rational response to a world that has reminded everyone how quickly assumptions can break.
That is the real significance of the commitment under discussion. It is one more data point in a longer trend of diversification. Whether this particular project becomes the flagship example or simply one of several will be decided by the hard work still ahead. For now the direction is clear enough to warrant careful attention from anyone who follows global energy flows.
The coming months will show whether the public enthusiasm translates into the detailed commercial agreements that turn announcements into operating infrastructure. Until those agreements are finalized, the story remains one of promising potential rather than completed fact. Potential, however, can be powerful when the underlying logic is sound. In this case the logic of avoiding the most vulnerable transit corridor while unlocking underutilized resources has a compelling simplicity that is hard to dismiss.
Energy markets reward those who plan for multiple scenarios. Adding a major new Pacific supply option expands the set of scenarios that can be managed successfully. That expansion alone makes the effort worth watching, even while the final outcome stays uncertain. The next chapters will be written in negotiating rooms, engineering offices, and construction sites rather than in public statements. Those quieter stages often determine whether bold visions become lasting infrastructure.