
I still remember the first time I looked at options pricing and felt that strange mix of curiosity and caution. Watching a familiar token suddenly appear inside a structured derivatives product changes the way you think about holding it. That exact feeling hit me when news circulated that TRX options had reached a major consumer platform with a minimum premium of only five dollars. For many people who follow the token closely, this development opens a practical door that previously felt locked behind higher barriers or more complex interfaces.
What The New TRX Options Availability Really Means
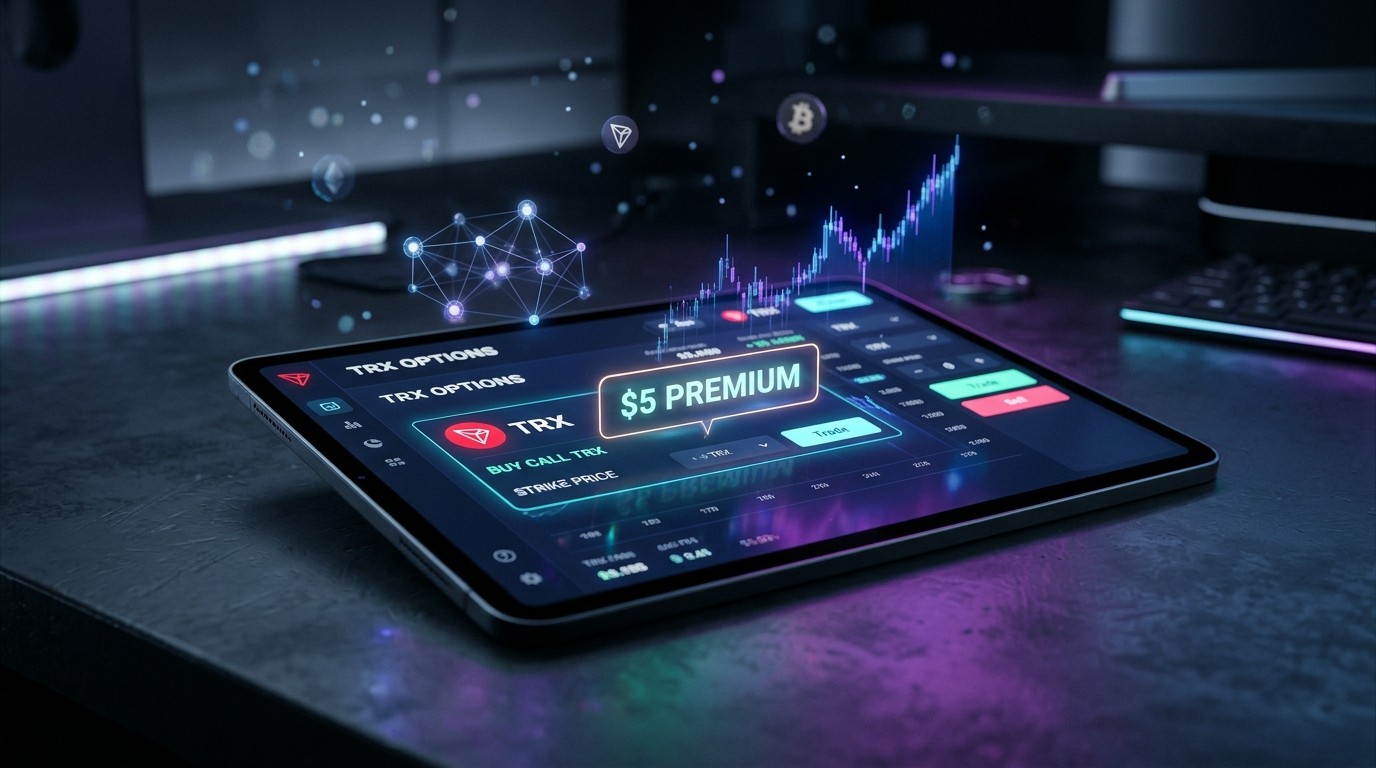
The rollout places TRX among a small group of supported assets inside the platform’s Trading Account. Users who meet the eligibility rules can now select an expiration date, pick a target price, decide on a trade amount, and review live market prices before confirming. The process converts those choices into either a call or a put. Funding happens upfront with USDC sitting in the same account. That simple sequence matters because it keeps the entire experience inside one familiar app rather than forcing people to jump between multiple services.
Contracts at launch run for periods of up to one week. Once purchased, the strike price and expiration become fixed. There is no early exit. You cannot sell the position back or close it before the clock runs out. That design choice shapes everything that follows. The amount paid for the premium sets the maximum possible loss right from the start. No margin calls appear later. No additional deposits are required to keep the position alive. For someone who prefers clear boundaries around risk, this structure feels refreshing even if it removes flexibility.
Eligibility Rules And Geographic Limits
Access is far from universal. Residents of the United States, the United Kingdom, Canada, France, Germany, Spain, Italy, the Netherlands, Malta, Japan and Nigeria sit on the exclusion list. The platform makes the point explicit: using a VPN to work around location checks is not allowed. Beyond geography, an eligible account and a funded Trading Account are required. Additional identity verification or formal acceptance of the Options Agreement and related risk acknowledgments may also be necessary. These layers exist for a reason, yet they also create a clear split between people who can participate and those who cannot.
I have found that geographic restrictions often frustrate holders who already keep the underlying token. Still, the rules remain firm. Anyone outside the permitted regions will simply see the product remain unavailable. That reality forces a practical question: does the rest of the available market still gain meaningful new tools even if certain large countries stay shut out?
How The Contracts Actually Work
These are cash-settled European-style calls and puts. Settlement happens bilaterally between the customer and a single entity based in the British Virgin Islands. That entity acts as principal and sole counterparty on every trade. The contracts never touch a public exchange or any external venue. Customers hold no rights against any hedging counterparty or trading venue. The arrangement keeps everything inside one closed relationship.
We are your sole counterparty to every option and we act as principal, not as your agent or broker.
That language appears in the formal agreement and deserves attention. It removes the usual exchange protections and compensation schemes that many traders take for granted. The risk guide is equally direct: the service lacks the licensing and supervision that licensed financial products normally carry. Users accept those terms when they proceed. In my view, transparency on this point is preferable to vague promises of institutional safeguards that do not actually exist here.
Premium, Fees And The Path To Profit
The five-dollar figure covers only the premium. Separate fees still apply. One charge is calculated as a percentage of the premium paid at the moment of purchase. Another settlement charge applies to the amount by which any qualifying gross payout exceeds that original premium. A spread or markup is already built into the quoted premium itself and does not appear as a separate line item. Fee schedules can change over time, and some accounts may receive discounts, yet any change leaves existing contracts untouched.
Payout calculation follows a straightforward formula. For a call that finishes in the money, the gross payment equals the settlement price minus the strike price, multiplied by the quantity of cryptocurrency covered. For a put the order reverses: strike price minus settlement price, again multiplied by quantity. Receiving a payment does not automatically equal profit. The final amount must first cover the premium and the upfront fee. Only the remainder counts as net gain. That distinction is easy to overlook when excitement runs high, yet it determines whether the trade ultimately adds to or subtracts from an account balance.
Quotes themselves remain valid for only thirty seconds. If confirmation does not arrive inside that window, a fresh quote becomes necessary. The short validity period reflects the speed of crypto markets and keeps displayed prices reasonably close to current conditions. Still, it can feel abrupt for anyone who likes to double-check numbers at a leisurely pace.
Risk Considerations That Cannot Be Ignored
Indicative odds, probabilities and potential payouts shown before purchase are not forecasts. They are not guarantees. Cryptocurrency prices move, sometimes violently, and those moves directly affect whether an option finishes in the money or expires worthless. When a contract expires with no payout, the entire premium and related fees are gone. There is no recovery mechanism. Because positions cannot be closed early, the holder simply waits until expiration regardless of how the market behaves in the meantime.
Perhaps the most interesting aspect is the absence of margin requirements. Buyers never need to own the underlying cryptocurrency. They never face a margin call. They never deposit additional funds to maintain the position. The maximum loss is known and paid in full at the beginning. That clarity appeals to people who dislike the open-ended risk profile of many leveraged products. At the same time, the inability to manage or exit the position introduces a different kind of exposure: time risk. Waiting out a full week while prices swing can test patience and discipline.
Context Within Broader Product Expansion
This options launch does not appear in isolation. The same platform earlier introduced wallet-based perpetual futures that cover a wide range of crypto markets and offer substantial leverage inside a self-custody environment. Later coverage also noted interest in prediction-market applications. Together these moves signal a deliberate effort to expand the range of derivatives-style tools available to retail users who already keep assets on the platform. Adding TRX to the initial options lineup sits inside that larger pattern.
TRX itself has appeared in other investment vehicles. A staked version of the token reached certain brokerage markets earlier under a dedicated ticker. That product focuses on holding and staking rather than directional options exposure. The contrast is useful. One vehicle emphasizes yield through staking rewards. The other emphasizes directional views over short time frames. Different tools serve different goals, and the presence of both expands the menu of choices available to holders.
Practical Steps For Anyone Considering Participation
Anyone who qualifies and feels curiosity should begin by confirming account eligibility and completing any outstanding verification steps. Next comes a careful reading of the Options Agreement and the accompanying risk disclosures. Understanding that a single entity stands as sole counterparty is essential. So is accepting that regulatory protections common in other markets do not apply here. Only after those foundations feel solid does it make sense to explore actual quotes.
- Verify geographic eligibility and account status before anything else
- Review the full Options Agreement and risk acknowledgments with care
- Start with the smallest possible premium size while learning the interface
- Treat the displayed odds and potential payouts as illustrations rather than predictions
- Accept that early exit is impossible and plan position size accordingly
In practice I have watched people underestimate the psychological weight of a locked position. A week can feel longer when the underlying price moves sharply against the chosen direction. Keeping position size modest relative to overall holdings helps preserve emotional balance. The five-dollar minimum makes experimentation relatively affordable, yet repeated small losses still accumulate. Discipline around frequency matters as much as discipline around size.
Settlement Mechanics In Everyday Language
At expiration the platform calculates the settlement price according to its internal rules. That price is then compared with the chosen strike. If the comparison produces a positive difference after multiplying by quantity, a gross payout is generated. Fees are deducted according to the published schedule. The remaining net amount, if any, is credited. If the option finishes out of the money, the position simply expires and the premium stays with the counterparty. There is no physical delivery of the underlying token. Everything resolves in cash terms inside the Trading Account.
This cash-settled approach removes the need to manage actual token transfers at expiration. It also means the product functions purely as a directional bet rather than a vehicle for acquiring or disposing of the underlying asset. Some traders prefer that purity. Others may wish for the flexibility of physical settlement. The current design leaves no choice on that point.
Why Short-Dated Contracts Dominate The Launch
Limiting initial expiries to one week keeps the product simple and reduces the complexity of longer-term pricing models. Shorter contracts also tend to experience faster decay of time value, which works in favor of the seller of the option and against the buyer when price stagnates. For buyers the implication is clear: the underlying must move enough, and soon enough, to overcome both the premium and the fees. Stagnant price action is the enemy of these short-dated long option positions.
Market conditions around the token can shift quickly. Periods of elevated volatility increase the chance that a short-dated option finishes in the money, yet they also inflate the premium paid at purchase. Quieter periods reduce the cost of entry but also reduce the probability of a meaningful move before expiration. Matching the chosen strike and time frame to expected market behavior remains the core skill. No interface can replace that judgment.
Comparing The Experience With Traditional Derivatives
Traditional options markets usually allow early closing, offer clearinghouse protections, and provide access to a wide range of expiries and strikes. This product deliberately forgoes those features in exchange for simplicity, low minimum size, and integration inside an existing consumer wallet experience. The trade-off is explicit. Users gain convenience and a known maximum loss. They give up flexibility, exchange transparency, and certain regulatory backstops. Whether that bargain feels attractive depends entirely on individual priorities and risk tolerance.
I tend to view the product as a specialized tool rather than a replacement for fuller-featured options markets. It suits people who already hold the token, already use the platform, and want occasional short-term directional exposure without opening new accounts elsewhere. It is less suitable for active traders who manage positions dynamically or who require the ability to exit when conditions change.
| Feature | This Product | Typical Exchange Options |
| Minimum Premium | $5 plus fees | Often higher |
| Early Close | Not available | Usually available |
| Counterparty | Single entity | Clearinghouse |
| Settlement | Cash, bilateral | Cash or physical via exchange |
| Geographic Access | Restricted list | Varies by venue |
The Role Of USDC Funding
All purchases draw from USDC balances held inside the Trading Account. That choice keeps settlement currency stable and familiar. It also means users must maintain sufficient USDC before attempting a trade. Converting other assets into USDC inside the same platform is possible for many, yet it adds a conversion step and potential spread cost. Planning liquidity in advance avoids last-minute friction when a favorable quote appears.
Because the premium and fees leave the account immediately, the remaining USDC balance drops by that amount at confirmation. There is no temporary hold or margin lock that later releases. The money is spent. That finality reinforces the importance of treating each purchase as a completed decision rather than a provisional one.
How The Token’s Network Characteristics Fit The Product
Representatives associated with the token’s ecosystem have described the addition as a natural fit, pointing to network scale, user base and the token’s operational role. Those characteristics help explain why the asset appeared in the initial group of seven supported cryptocurrencies. High activity levels and broad recognition can support more consistent options interest over time, even if early volumes remain modest while users explore the new interface.
Still, network fundamentals and short-term options pricing operate on different time scales. A strong underlying network does not guarantee profitable option trades over any given week. Directional accuracy and timing remain the decisive factors for individual results. The product simply provides a structured way to express those views with limited capital at risk.
Potential Behavioral Effects On Holders
Access to low-cost short-dated options can change how some people relate to the tokens they already hold. Instead of simply waiting for longer-term appreciation, a holder might occasionally layer a short-term call or put on top of an existing position. That layering can amplify gains when the view proves correct, yet it can also create a pattern of frequent small bets that slowly erode capital through fees and unsuccessful outcomes. Awareness of that risk is useful.
In my experience the most sustainable approach treats these contracts as occasional tactical tools rather than a daily activity. Setting personal rules around maximum frequency, maximum capital allocated, and required conviction level before entry helps keep the activity in proportion. Without such rules the low minimum premium can quietly encourage over-trading.
Looking Ahead At Possible Evolution
Initial launches often begin with limited expiries and a focused asset list. Over time platforms sometimes expand the range of available dates, add more strikes, or introduce additional tokens. Whether this product follows that path remains to be seen. For now the one-week maximum and the seven-asset starting group define the available opportunity set. Users who find the current offering useful may hope for gradual expansion. Users who find the restrictions too tight may simply continue using other venues.
Regulatory developments in various jurisdictions will also influence future availability. The current exclusion list is already lengthy. Any tightening of rules in additional countries could shrink the eligible user base further. Conversely, clearer frameworks in some regions might eventually allow expansion. Those external factors sit outside the control of any single platform, yet they shape the practical reach of the product.
Balancing Opportunity And Restraint
The arrival of TRX options with a five-dollar minimum premium lowers a practical barrier that previously kept many retail holders on the sidelines of structured derivatives. The integration inside an existing consumer interface removes another layer of friction. At the same time the product carries deliberate limitations: short maximum duration, no early exit, bilateral settlement with a single counterparty, and clear geographic exclusions. Those design choices define both the appeal and the boundaries of the offering.
Anyone who decides to participate benefits from approaching the product with eyes open. Read the agreements. Understand the fee structure. Accept that the maximum loss is paid upfront and that waiting until expiration is the only path forward once a trade is confirmed. Treat displayed probabilities as rough illustrations rather than reliable forecasts. Keep position sizes modest relative to overall capital. Those habits will not eliminate risk, yet they reduce the chance that a new tool becomes a source of unnecessary frustration.
Markets continue to evolve, and the tools available to express views on individual tokens continue to multiply. This particular product occupies a specific niche: simple, short-dated, cash-settled options with a low entry point and firm risk boundaries. For some holders it will prove useful. For others it will remain an interesting but unused feature. Either outcome is legitimate. The important point is that the choice now exists for those who qualify and who find the structure compatible with their own approach to risk and opportunity.
As with any new capability, the first weeks after launch often reveal how real users actually behave. Some will test small positions immediately. Others will watch from the sidelines while they study the interface and the settlement process. A few may discover that the combination of locked duration and bilateral counterparty risk feels less comfortable than they anticipated. All of those reactions provide useful information. Over time the collective experience of early participants will clarify whether the product settles into regular use or remains a niche feature for occasional tactical expression.
I find myself returning to one practical observation. The five-dollar minimum is low enough to encourage experimentation, yet the inability to exit early demands a level of commitment that many short-term traders are unaccustomed to providing. Bridging that gap requires either greater selectivity in the trades that are taken or a willingness to accept the full time risk of each position. Neither path is wrong. Clarity about which path one is actually following simply makes the experience more intentional and, ultimately, more sustainable.
The broader context of expanding derivatives access for retail crypto users continues to unfold. Wallet-based perpetuals, options with defined maximum loss, and other structured products each address different preferences around leverage, complexity and risk. The presence of TRX inside the initial options group underscores the token’s continued visibility among platforms building these tools. Whether that visibility translates into meaningful trading volume will depend on the decisions of individual users who now have the choice in front of them.
For those who decide to step forward, preparation remains the quiet advantage. Confirm eligibility. Study the fee schedule. Practice reading the quote screen until the numbers feel familiar. Decide in advance how much capital, if any, feels appropriate for this style of product. Then, and only then, consider placing a first small trade. That sequence turns a novel feature into a controlled experiment rather than an impulsive reaction to novelty. In markets that already move quickly enough, a little deliberate pacing rarely hurts.
Ultimately the value of any new trading tool is measured by the quality of decisions it enables rather than by the mere fact of its existence. TRX options with a low minimum premium now exist inside a consumer-facing platform for eligible users. The contracts are short, the counterparty is singular, the exit is unavailable, and the maximum loss is known. Those facts define the opportunity. How each person responds to them will determine whether the product becomes a useful addition or simply another unused capability sitting inside an app. The choice, for those who qualify, is now open.