

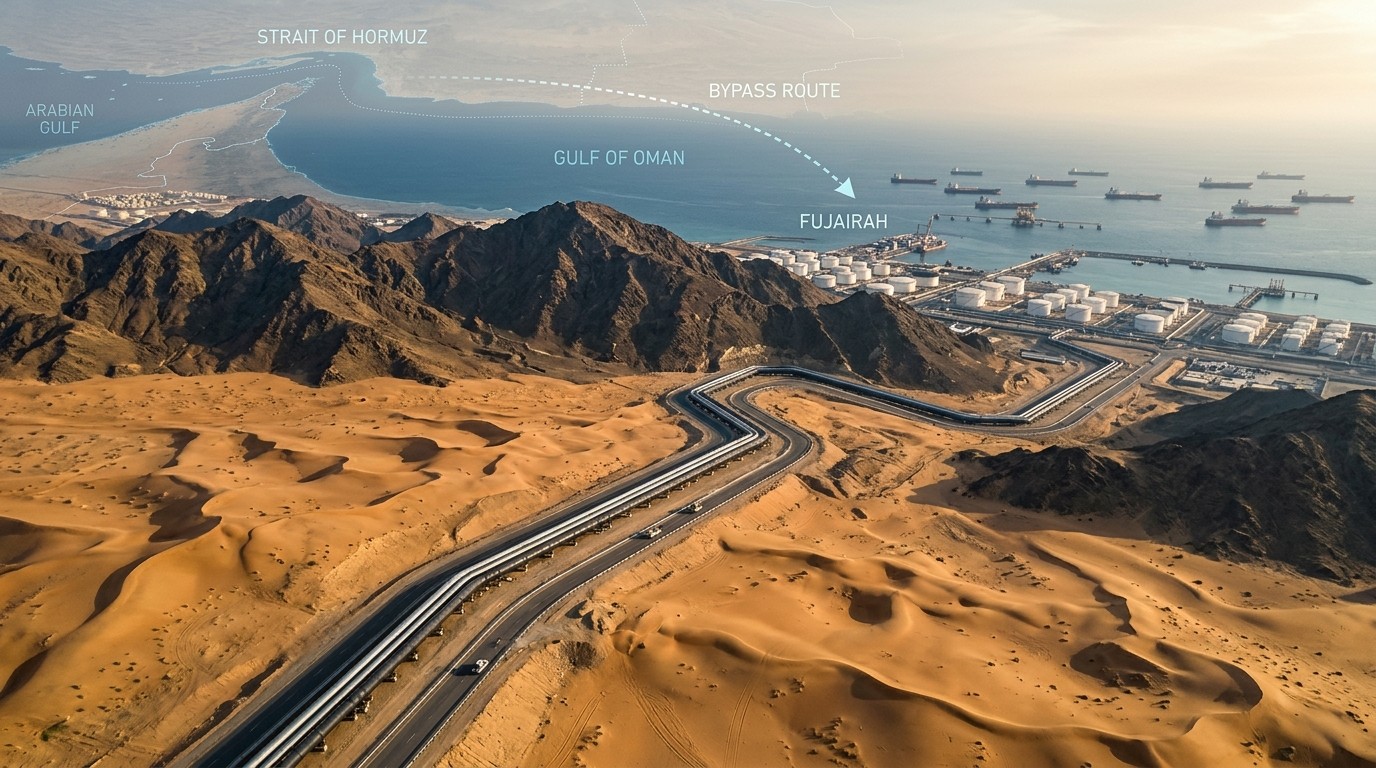

Have you ever wondered why a stretch of water barely 21 miles wide at its narrowest point can still send shockwaves through every major economy on the planet? I was thinking about that exact question last week while watching crude prices twitch on nothing more than a rumor. The latest chatter out of the Gulf suggests the United Arab Emirates is quietly exploring a third crude export pipeline that would completely avoid the Strait of Hormuz. If the reports hold any water, this isn’t just another infrastructure project—it’s a calculated attempt to rewrite the rules of energy security in one of the world’s most volatile regions.
For years the Hormuz chokepoint has functioned like a geopolitical pressure valve. Roughly a fifth of global oil consumption still funnels through those waters every single day. When tensions rise, tankers slow, insurance premiums jump, and traders start pricing in worst-case scenarios. The UAE already operates one pipeline that skirts the strait entirely. It announced plans for a second earlier this year. Now talk of a third has started circulating among Asian refiners. Even if Abu Dhabi’s state energy company has called the reports speculative, the mere possibility is enough to make energy markets sit up and take notice.
Why the Strait of Hormuz Still Dominates Global Energy Thinking
The geography is brutally simple. On one side sits Iran. On the other, Oman. Between them lies a corridor that has been the world’s most important oil artery for half a century. During the Iran-Iraq war in the 1980s, both sides attacked tankers in what became known as the Tanker War. More recently, incidents involving mines, drone strikes, and temporary closures have repeatedly reminded everyone how fragile the status quo remains. I’ve always found it striking that so much of modern industrial civilization still depends on a waterway that can be disrupted by relatively modest means.
Asian economies feel this vulnerability most acutely. China, India, Japan, and South Korea together buy the majority of the crude that exits the Persian Gulf. For them, any interruption isn’t an abstract geopolitical event—it’s a direct threat to refinery runs, industrial output, and inflation. That dependence is precisely why producers on the Arab side of the Gulf have spent years quietly building land-based alternatives. The UAE’s existing Habshan-Fujairah pipeline, operational since 2012, already moves 1.5 million barrels per day and can be expanded to 1.8 million. It runs 252 miles from the western fields to the eastern coast, letting tankers load outside the strait entirely.
The Existing Habshan-Fujairah Line and Its Limits
That first pipeline was a pragmatic response to earlier crises. It proved that Fujairah, sitting on the Gulf of Oman, could serve as a reliable alternative export terminal. Capacity, however, is still modest compared with the UAE’s total production potential. When demand surges or when other Gulf producers face constraints, the single line becomes a bottleneck rather than a complete solution. Expanding it helps, but it doesn’t eliminate the need for additional routes. From what I’ve observed in similar infrastructure stories, once a country proves a bypass works, the next logical step is almost always more capacity.
Earlier this year the UAE publicly confirmed a second project—the West-East Pipeline—expected to come online around 2027 and roughly double the volume that can exit through Fujairah. That announcement alone signaled serious long-term intent. Adding a third line would push the strategy from contingency planning into structural transformation. Asian customers have reportedly been told about the concept, which suggests commercial discussions are at least underway even if final engineering and routing decisions remain open.
Why a Third Pipeline Changes the Calculation
Three separate systems would give the UAE genuine redundancy. Maintenance on one line, weather delays, or even targeted disruption would no longer threaten the majority of export capacity. More importantly, it would further dilute the leverage any single actor holds over Gulf flows. I’ve found that energy markets tend to price risk in increments; each additional million barrels that can move around a chokepoint quietly lowers the premium traders demand for geopolitical insurance. Over time those basis-point differences compound into real money for producers and lower delivered costs for refiners.
Energy security is rarely achieved with one big project. It is built through layers of options that make disruption progressively more expensive and less effective for any adversary.
– Long-time energy infrastructure analyst
Of course, none of this is free. Pipelines cost billions, require years of construction, and still face environmental and community scrutiny even in the desert. The fact that discussions are apparently reaching Asian buyers implies the UAE believes the commercial case is strong enough to justify the outlay. Whether the third line ultimately follows the same general corridor or takes a different route remains unclear, but the strategic direction is unmistakable.
How Neighboring Producers Are Following the Same Playbook
The UAE is not operating in isolation. Saudi Arabia has long maintained the Petroline that runs from the Eastern Province to Yanbu on the Red Sea, giving it an independent outlet. Capacity on that system has been expanded multiple times. Kuwait has floated ideas for new pipelines that would also reduce reliance on Hormuz. When you add these efforts together, the cumulative effect is a gradual erosion of the strait’s monopoly on Gulf crude. In my view, this is less about any single country scoring a victory and more about a collective recognition that depending on one maritime corridor is no longer acceptable risk management.
- Existing UAE Habshan-Fujairah line: 1.5–1.8 million barrels per day
- Announced West-East Pipeline: expected online 2027, significant capacity increase
- Potential third line: still in discussion phase, aimed at further Asian-focused exports
- Saudi Petroline: mature Red Sea route already in operation
- Kuwait proposals: early-stage ideas for additional bypass capacity
Taken as a whole, these projects suggest Gulf producers are treating Hormuz risk as a permanent feature of the landscape rather than a temporary spike. That mindset shift matters more than any individual barrel of capacity. Markets notice when producers invest for resilience instead of simply maximizing short-term volume.
Market Implications for Crude Prices and Asian Buyers
If even two of these bypass systems reach full capacity, the percentage of Gulf oil that must transit Hormuz will decline. That doesn’t eliminate risk—tankers still have to reach Asian ports—but it reduces the probability of a sudden, large-scale disruption. Asian refiners have spent years building commercial relationships and storage to manage exactly this kind of uncertainty. Additional pipeline capacity would give them more negotiating leverage and potentially smoother supply. From a pricing standpoint, lower perceived risk usually translates into tighter differentials and less dramatic spikes when headlines appear.
Perhaps the most interesting aspect is how this plays into longer-term energy transition debates. Critics sometimes argue that new fossil infrastructure locks in dependence. Supporters counter that reliable supply during the transition years is what prevents price spikes that slow electrification and efficiency efforts. I’ve watched both arguments play out for over a decade; the practical reality is that economies still need the barrels while alternatives scale. Infrastructure that makes those barrels more secure tends to be welcomed by the buyers who actually run the refineries.
| Route Type | Approximate Capacity Focus | Strategic Advantage |
| Hormuz Transit | Majority of current Gulf exports | Existing, high volume |
| UAE Fujairah Lines | Growing multi-million barrel potential | Complete maritime bypass |
| Saudi Red Sea | Significant established volume | Independent western outlet |
| Potential Kuwait Options | Early planning stage | Additional diversification |
Construction Realities and Remaining Uncertainties
Building pipelines across desert terrain is technically straightforward compared with many other megaprojects, yet timelines still stretch. Land rights, environmental assessments, and the need to coordinate with existing fields and terminals all take time. The second UAE line is already targeted for 2027; a third would presumably follow later in the decade. That lag means markets will continue to price Hormuz risk for years even if the long-term direction is clear. Political calendars inside the region and beyond can also accelerate or delay decisions. In my experience, energy infrastructure rarely moves in a straight line from announcement to first oil.
The official response from the state energy company has been that the third-pipeline reports are inaccurate and speculative. That denial is worth noting, yet it does not erase the pattern of previous announcements or the commercial conversations reportedly taking place with Asian customers. Companies often push back on incomplete stories while continuing internal studies. The prudent approach is to treat the idea as a live possibility rather than a confirmed project until concrete milestones appear.
Broader Geopolitical Ripple Effects
Reducing dependence on Hormuz does more than protect barrels. It changes the cost-benefit calculation for any actor considering disruption. When a larger share of exports can move regardless of what happens in the strait, the economic pain inflicted on producers shrinks while the political cost of interference rises. That dynamic has already begun to influence diplomatic conversations. At the same time, the existence of alternative routes does not remove all leverage; it simply redistributes it. Shipping lanes outside the Gulf still face their own risks, from piracy to weather to great-power competition.
For Western policymakers the trend is largely welcome. Diversified export routes make coordinated sanctions or pressure campaigns more complicated, but they also reduce the chance of a sudden supply shock that forces painful political choices at home. Asian governments have an even clearer interest: stable volumes at predictable prices. The quiet pipeline-building race therefore sits at the intersection of commercial logic and strategic hedging. I’ve come to believe these projects will matter more for the next ten years than many of the higher-profile diplomatic summits that dominate headlines.
What This Means for Investors and Energy Markets
From an investment perspective, the story reinforces a familiar theme: energy security infrastructure tends to attract capital when geopolitical risk is elevated. Pipeline operators, terminal developers, and the service companies that support them all stand to benefit if multiple projects advance. At the same time, the gradual reduction in Hormuz exposure could modestly compress the risk premium embedded in Gulf crude differentials over time. Those shifts are rarely dramatic in any single quarter, but they accumulate. Traders who position for smoother supply rather than constant crisis pricing may find the environment evolving in their favor.
None of this guarantees lower absolute oil prices. Demand growth in Asia, OPEC+ discipline, and non-Gulf supply trends still dominate the big picture. What the pipeline expansions do is reduce the frequency and severity of the sharp spikes that occur when Hormuz headlines dominate. In a market that has grown accustomed to pricing tail risks, even incremental improvements in physical optionality can change behavior. I suspect we will look back on the mid-2020s as the period when Gulf producers finally moved from talking about diversification to systematically building it.
Looking Ahead: Layers of Resilience Rather Than Single Solutions
The third UAE pipeline, if it materializes, will not end Hormuz’s importance. Significant volumes will continue to move by tanker through the strait for the foreseeable future. What it will do is add another layer to a thickening web of alternatives. Combined with storage expansions, floating storage options, and commercial hedging, the overall system becomes harder to disrupt comprehensively. That resilience is exactly what large importing economies have been quietly requesting for years. Whether the next phase of construction stays on schedule will depend on oil prices, financing conditions, and the regional political climate—variables that rarely align perfectly.
Still, the direction of travel is hard to ignore. Producers are investing real money to give themselves and their customers more choices. In a world where energy remains both an economic lifeline and a geopolitical instrument, those choices matter. The next time crude prices react to news from the Gulf, it will be worth asking how much of the volume can already move around the problem rather than through it. That single question may tell us more about the future of the market than any individual headline.
Energy markets have always rewarded those who prepare for disruption before it arrives. The UAE’s evolving pipeline strategy, alongside similar efforts elsewhere in the Gulf, is a concrete expression of that preparation. Whether the third line is ultimately built exactly as rumored or takes a different form, the underlying logic is unlikely to reverse. For anyone who follows crude, that is a development worth tracking closely over the coming years.



