
Have you ever glanced at your payslip and felt that quiet unease, wondering whether the figure HMRC has taken is actually correct? Last spring I sat with a friend who earns a perfectly ordinary salary and watched her do a double-take when she realised the basic-rate band had not moved in years. That single frozen threshold had already cost her more than she expected. Income tax still accounts for more than a quarter of everything the government raises, yet plenty of people only discover the finer points when a bonus or a pay rise lands them in a higher band. The rules look straightforward on a government page; in real life they reward anyone who bothers to understand the slices.
Why Income Tax Still Shapes Everyday Money Decisions
Most of us treat the monthly deduction as an unavoidable fact of life. That attitude is expensive. Once you see how the system carves your earnings into layers, the same salary can produce very different take-home figures depending on where you sit relative to the thresholds. Couples, in particular, often discover that one partner’s extra income triggers effects that neither expected. I have watched households rearrange pension contributions simply because one person crossed a line they had never noticed before.
The current tax year runs from 6 April 2026 to 5 April 2027. For anyone living in England, Wales or Northern Ireland the headline numbers remain familiar, yet the longer those numbers stay frozen the more powerful they become. Scotland sets its own rates on non-savings, non-dividend income, so the picture north of the border is different. The rest of this piece walks through the practical mechanics that actually decide what leaves your account.
The Personal Allowance and Why It Matters More Than the Rates
Everyone starts with the same tax-free amount: the personal allowance of £12,570. Nothing is charged on the first slice of income up to that figure. The allowance has sat at exactly that level since April 2021 and is scheduled to stay there until at least April 2031. In cash terms it has not kept pace with ordinary wage growth or prices, which is the quiet mechanism known as fiscal drag.
For most employees the allowance is delivered through the tax code. A standard code of 1257L tells the employer to ignore the first £12,570. If you have other income, benefits in kind, or unpaid tax from earlier years, the code changes and the allowance shrinks or disappears from your payslip. Checking the code once or twice a year is one of the simplest ways to avoid a surprise bill later.
There is an extra twist once income rises above £100,000. For every £2 of adjusted net income above that point the personal allowance is reduced by £1. By the time earnings reach £125,140 the allowance has been withdrawn completely. That taper creates an effective marginal rate of 60 per cent on the slice between those two numbers, before National Insurance is even added. Plenty of people still believe the higher rate is simply 40 per cent all the way up; the taper is the detail that changes the arithmetic.
The personal allowance is not a fixed right once your income climbs. It is a sliding benefit that disappears precisely when many households are trying to save more aggressively.
How the Bands Actually Work for England, Wales and Northern Ireland
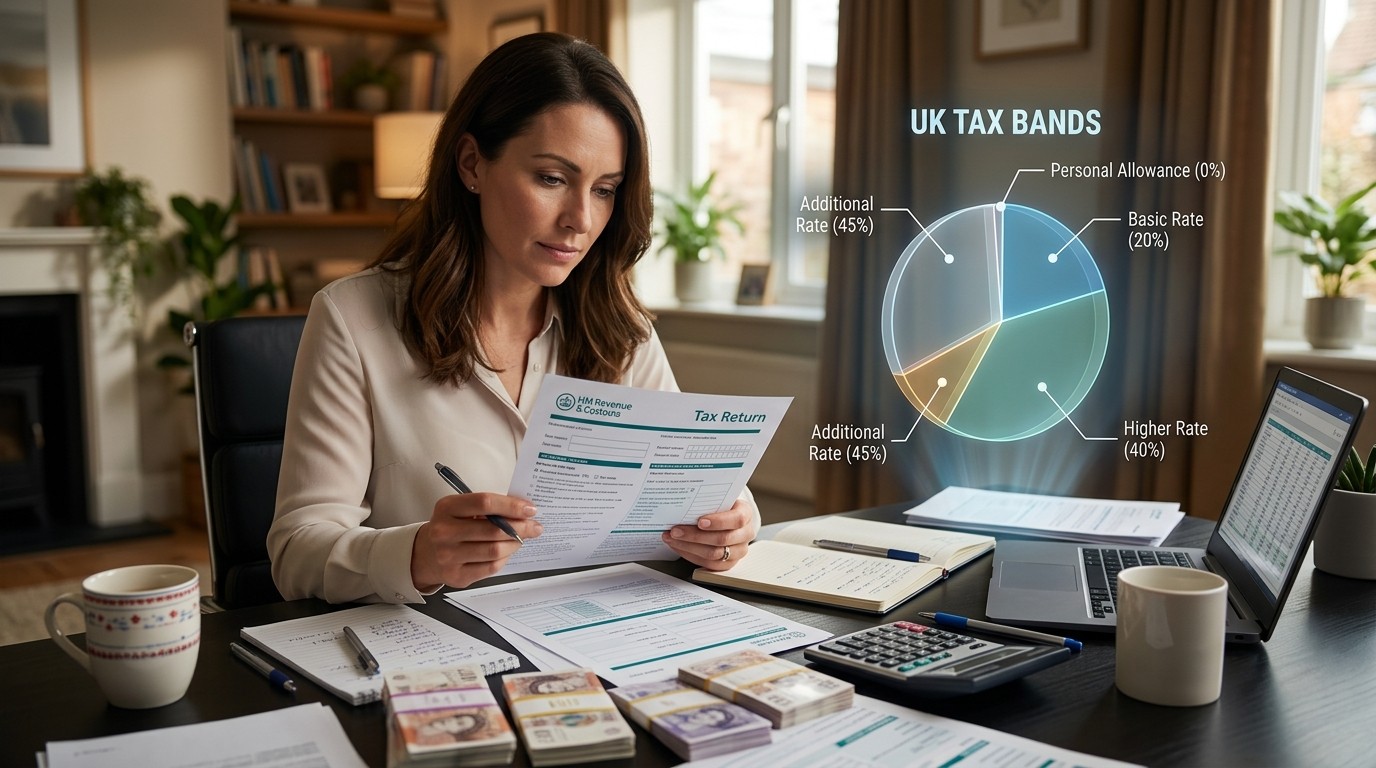
Above the personal allowance the income is divided into three bands. The basic rate of 20 per cent applies to the next £37,700, taking total income up to £50,270. Anything between £50,271 and £125,140 is taxed at 40 per cent. Above £125,140 the additional rate of 45 per cent applies. Only the slice that falls inside each band is charged at that band’s rate; a pay rise that crosses a threshold does not re-tax the whole salary.
That last point still surprises people. A colleague once refused a small promotion because he thought the entire salary would suddenly be taxed at 40 per cent. The extra money is taxed at the higher rate; the earlier money stays at the lower rates. The difference on a few thousand pounds is real but rarely dramatic enough to turn a good offer into a bad one.
| Band | Income range (2026/27) | Rate |
| Personal allowance | Up to £12,570 | 0% |
| Basic rate | £12,571 to £50,270 | 20% |
| Higher rate | £50,271 to £125,140 | 40% |
| Additional rate | Over £125,140 | 45% |
The numbers above assume the full personal allowance is available. Once the taper begins, the effective picture changes and the higher-rate band effectively starts earlier. Savings interest and dividends sit on top of these bands and are taxed at different rates, but the underlying slice system remains the same.
The 60 Per Cent Trap and Other Invisible Edges
Between £100,000 and £125,140 the combination of the 40 per cent rate plus the withdrawal of the personal allowance produces that 60 per cent effective rate on the margin. Add the 2 per cent National Insurance that applies above the upper earnings limit and the combined marginal rate climbs further. For parents the High Income Child Benefit Charge can add another layer once adjusted net income exceeds £60,000. Each of these edges is easy to miss until the money has already left the account.
I have found that the most useful habit is simply to map your expected total income for the year against these lines before the year is half over. A modest pension contribution, a gift-aid donation, or even timing a bonus can pull income back below a threshold and restore the allowance or reduce the charge. The arithmetic is not complicated once you see the lines; the difficulty is remembering they exist.
- Personal allowance fully available below £100,000
- Allowance tapers by £1 for every £2 above £100,000
- Allowance reaches zero at £125,140
- Effective 60% marginal rate on the taper band before National Insurance
Scotland’s Separate Rates and What They Change
If you live in Scotland you pay Scottish income tax on most earned income, pensions and other non-savings income. The rates for 2026/27 are more finely sliced. There is a starter rate of 19 per cent, a basic rate of 20 per cent, an intermediate rate of 21 per cent, a higher rate of 42 per cent, an advanced rate of 45 per cent and a top rate of 48 per cent. The bands are wider at the lower end than they were a couple of years ago, which gives a small amount of relief to modest earners, but the higher rates bite earlier and harder than the rest of the UK.
Your tax code begins with an S if Scottish rates apply. Employers and pension providers use that letter to deduct the correct amount. Savings interest and dividends are still taxed at the UK-wide rates, so the overall picture for someone with mixed income is a hybrid. The practical result is that a Scottish resident on a mid-to-high salary usually pays more income tax than someone on the same salary in England, while someone on a lower salary may pay slightly less.
Fiscal Drag and the Long Freeze on Thresholds
Thresholds that do not rise with wages or prices automatically pull more people into higher bands. That process has been running for several years and has been extended. The personal allowance and the higher-rate threshold are locked until at least 2031. Every time average earnings grow, a larger share of the workforce finds itself paying 40 per cent on a bigger slice of income. The effect is gradual, which is why it rarely makes headlines, yet the cumulative impact on household budgets is substantial.
Recent analysis of the frozen bands shows that hundreds of thousands of people who would have remained basic-rate taxpayers under earlier indexing rules have already crossed into the higher rate. The same freeze also increases the number of people affected by the personal-allowance taper. In my view this is the aspect of the system that most rewards forward planning. Once you accept that the thresholds are unlikely to move soon, the value of using pension contributions or other reliefs to stay below key lines becomes clearer.
Worked Examples That Show the Real Numbers
Take a straightforward salary of £35,000 in England. The first £12,570 is free. The remaining £22,430 is taxed at 20 per cent, producing an income-tax bill of £4,486. National Insurance is charged separately on a similar band structure, but the income-tax portion is already fixed by the bands. Move the same person to £55,000 and the calculation changes. The first £12,570 is still free, the next £37,700 is taxed at 20 per cent, and the final £4,730 is taxed at 40 per cent. The total income tax is roughly £9,432. Only the slice above £50,270 attracts the higher rate.
Now consider £110,000. The personal allowance is partially withdrawn. Adjusted net income of £110,000 means the allowance is reduced by £5,000, leaving an effective allowance of £7,570. The tax calculation therefore treats a larger portion of the income as taxable, and the marginal rate on the last few thousand pounds sits at 60 per cent before National Insurance. A pension contribution that brings adjusted net income back to £99,999 restores the full allowance and can be cheaper, after tax relief, than leaving the money exposed to the taper.
These examples ignore other income, benefits, or student-loan deductions, all of which can alter the final figure. They do, however, illustrate the basic architecture. Once you can sketch the bands for your own expected income, the payslip stops being a mystery and becomes a set of numbers you can influence.
National Insurance and the Combined Marginal Rate
Income tax never arrives alone. Class 1 National Insurance for employees is charged at 8 per cent between the primary threshold and the upper earnings limit, then falls to 2 per cent above that limit. The upper earnings limit currently sits at the same £50,270 point as the higher-rate income-tax threshold. The practical result is a combined marginal rate of 28 per cent through the basic-rate band and 42 per cent through most of the higher-rate band. Inside the personal-allowance taper the combined figure is higher still.
Self-employed people face Class 4 National Insurance on similar bands, although the exact percentages differ slightly. The interaction matters when you are deciding whether extra earnings are worth the effort. A freelance day that pushes you across a threshold can be taxed at a higher combined rate than the same day would have been earlier in the year. Timing and pension planning become more valuable once you see the full picture.
Practical Ways to Influence the Bill
Pension contributions are the most widely used lever. Money paid into a registered pension scheme reduces adjusted net income for the purposes of the personal-allowance taper and the high-income child-benefit charge. The tax relief is given either at source or through self-assessment, depending on the type of scheme. For higher-rate taxpayers the relief is particularly efficient because it pulls income out of the 40 per cent (or 60 per cent) band.
Marriage allowance lets a basic-rate taxpayer transfer part of their unused personal allowance to a spouse or civil partner who is also a basic-rate taxpayer. The transfer is worth a few hundred pounds a year and is simple to claim, yet many eligible couples never do it. Blind person’s allowance is another smaller relief that is often overlooked. Neither of these changes the headline rates, but both improve the final number without requiring large cash movements.
- Map expected income against the key thresholds early in the year
- Consider pension contributions to reduce adjusted net income
- Check whether marriage allowance or other small reliefs apply
- Review your tax code at least twice a year
- Keep records of any gift-aid donations or other allowable deductions
Common Mistakes That Cost Real Money
The most frequent error is assuming the whole salary is taxed at the highest rate that appears on the payslip. Another is ignoring the personal-allowance taper until the self-assessment bill arrives. People who receive bonuses or commission often fail to adjust their tax code in time, so too much or too little is deducted through the year. Side income that is not declared promptly can also push someone across a threshold without them noticing until the following January.
Perhaps the most interesting aspect is how rarely people calculate the marginal rate before accepting extra work. Once the combined income-tax and National Insurance rate climbs above 40 per cent, the net reward for additional hours falls sharply. That does not mean the work is never worth doing; it does mean the decision should be made with the real numbers rather than the headline salary.
Understanding the bands does not require a tax degree. It requires ten minutes with a calculator and a willingness to look at the thresholds before the money has already been spent.
– Independent tax commentator
Dividends, Savings and Other Income Layers
Dividends are treated as the top slice of income and are taxed at different rates: 10.75 per cent for basic-rate taxpayers, 33.75 per cent for higher-rate taxpayers and 39.35 per cent for additional-rate taxpayers in the current year. There is a small dividend allowance that is taxed at 0 per cent, but it has been reduced over successive years. Savings interest benefits from a personal savings allowance that is £1,000 for basic-rate taxpayers and £500 for higher-rate taxpayers; additional-rate taxpayers receive no allowance. These allowances sit on top of the main bands and can be lost once total income rises.
The practical consequence is that a person who stays inside the basic-rate band keeps more of any interest or dividends than someone who has crossed into the higher rate. Again, pension contributions or other adjustments that keep total income below the threshold preserve both the lower rates and the allowances. The system rewards people who look at the whole picture rather than each income stream in isolation.
Self-Assessment and When You Must File
Most employees never need to complete a self-assessment return. The obligation arises once you have untaxed income above a certain level, capital gains above the annual exempt amount, or income that has not been fully taxed at source. Higher-rate taxpayers who receive dividends or interest often find themselves inside the system even if their employment income is correctly taxed through PAYE. The deadline for online filing is 31 January following the end of the tax year, and the payment on account system can require two advance payments during the year.
Filing early removes the January panic and gives you time to spot errors in the tax code or missed reliefs. Many people still leave the return until the final weekend. That habit is understandable, yet it removes any chance to adjust pension contributions or other planning steps before the year ends. The return itself is not especially difficult once the income figures are gathered; the difficulty is usually the gathering.
Testing Your Own Knowledge
A useful exercise is to answer a few simple questions before looking anything up. What is the personal allowance this year? At what income does the higher rate begin? Does a pay rise that crosses £50,270 tax the entire salary at 40 per cent? How does the personal allowance change above £100,000? Most people get at least one of those wrong. The mistakes are rarely dramatic on a single payslip, but they compound over a career.
You can run the same test with a partner or a friend. The conversation usually reveals at least one threshold that neither person had fully internalised. Once the numbers are clear, the planning decisions become obvious rather than theoretical. That is the real value of the quiz format: it surfaces the gaps before they become expensive.
Looking Ahead and Staying Current
The rates and thresholds for 2026/27 are already fixed, and the longer freeze means the same figures will apply for several more years unless policy changes. Scotland will continue to set its own bands on non-savings income. The interaction with National Insurance, child benefit, and other charges will keep producing effective marginal rates that are higher than the headline figures. Anyone who treats the system as static will gradually pay more as a share of income simply because wages grow while the bands do not.
In my experience the people who stay ahead are not those with the most complex arrangements. They are the ones who check their tax code, map their income against the known lines, and use the ordinary reliefs that already exist. The rules are public. The only requirement is the willingness to look at them before the year is over. Once you do, the payslip stops being a surprise and becomes a set of choices you can still influence.
Income tax will remain the largest single levy most households face. Understanding the bands, the personal allowance and the quiet effects of the freeze does not eliminate the bill, but it does put you in a position to keep more of what you earn. That knowledge is available to anyone who spends a little time with the numbers. The rest is simply deciding to use it.