
Have you noticed how the conversation around climate targets in Britain has grown quieter lately? Not because the science disappeared, but because the practical weight of those targets finally landed on kitchen tables and factory floors across the country. What began as a bold national project now feels more like a series of careful recalibrations. In my view, this shift was inevitable once the easy wins in the power sector ran out and the harder work of changing how we heat homes and move around began in earnest.
How Britain’s Climate Ambition Met Everyday Reality
Britain still holds one of the most ambitious legal frameworks for cutting greenhouse-gas emissions anywhere in the developed world. The Climate Change Act created a clear statutory path, and the later decision to aim for net zero by 2050 raised the bar even higher. For a while the numbers looked impressive. By 2024 the country had become the first major economy to cut emissions by more than half from 1990 levels. That progress came largely from cleaning up electricity generation, shutting coal plants and expanding renewables at remarkable speed.
Yet the next stretch of the journey looks far steeper. Roughly nine-tenths of the remaining emissions sit outside the power sector. They live in the gas boilers under kitchen floors, the petrol and diesel cars in driveways, the industrial processes that still rely on fossil fuels, and the planes that keep the economy connected. Changing those systems requires more than building bigger wind farms. It demands shifts in daily habits, large capital outlays from households, and infrastructure upgrades that take years to deliver.
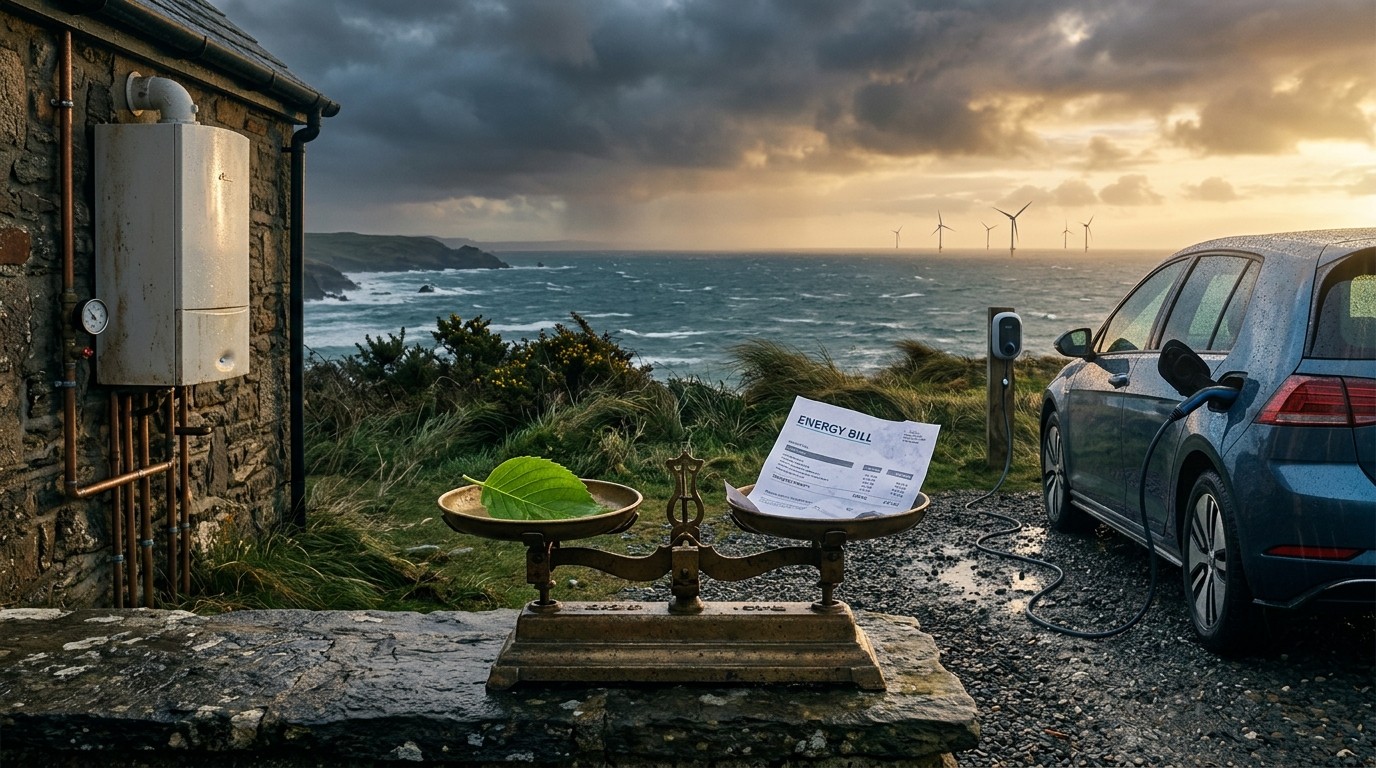
I’ve found that people often underestimate how visible and personal these remaining changes feel. Switching a power station is invisible to most citizens. Asking millions of households to replace a working boiler or buy a different kind of car is anything but invisible. When energy prices spiked earlier this year, the difference in impact was stark. A typical household still using a gas boiler and petrol car saw bills rise almost four times more than a household already equipped with a heat pump and an electric vehicle. Rural homes relying on oil faced an even steeper jump. Those numbers stick in the mind far longer than any distant 2050 deadline.
The Quiet Retreat From Interim Targets
Officially the 2050 net zero goal remains intact. Ministers continue to describe it as government policy. Yet almost every milestone on the road toward that destination is being softened, delayed or quietly dropped. The planned ban on new oil-fired boilers due in 2026 has disappeared from the near-term agenda. The 2035 phase-out of gas boilers looks increasingly flexible. Ambitions for installing 600,000 heat pumps a year by 2028 have been set aside once it became clear the supply chain and consumer demand could not keep pace.
Similar softening is underway in transport. Rules requiring a rising share of new car sales to be electric are expected to be relaxed. The target for sustainable aviation fuel to make up ten percent of jet fuel by 2030 is under review. Even the once firm pledge to run a fully clean electricity system by 2030 has been adjusted to something closer to 95 percent carbon-free, and even that figure is now described more as an aspiration than a binding commitment.
Perhaps the most interesting aspect is how little public drama has accompanied these changes. There has been no grand announcement of a policy U-turn. Instead the language simply becomes more cautious. When the energy secretary was asked recently whether the clean power goal would be met, the answer avoided any firm guarantee. That hesitation speaks volumes.
Why the Political Consensus Fractured
For more than a decade a broad cross-party consensus supported ambitious climate targets. That consensus has thinned noticeably. The cost-of-living pressures that dominated recent years forced a reordering of priorities. When household budgets are stretched, abstract long-term goals lose political power. The current administration has made clear that reducing immediate energy costs for families sits above almost every other consideration.
Recent budget decisions reflect that shift. Hundreds of millions of pounds previously earmarked for carbon capture and hydrogen projects were redirected toward defence. Green levies that once sat on household energy bills are being moved into general taxation, softening the direct hit on consumers even if the overall public cost remains. Approvals for new North Sea production, including the Jackdaw field and the ongoing debate around Rosebank, signal a more pragmatic stance on domestic oil and gas.
Some observers argue this is simply realism catching up with ambition. Others see a deeper erosion of commitment. In my experience watching these debates, both things can be true at once. The technology for deeper decarbonisation exists in many cases, yet the speed of deployment, the capital required, and the political tolerance for higher near-term costs have all proven more constrained than earlier models assumed.
The Grid Bottleneck Nobody Wanted to Discuss
One structural problem keeps surfacing in every serious discussion of the energy transition: the electricity network itself. Britain’s grid was built for a different era, with large centralised power stations feeding demand centres. It was never designed for the rapid growth of intermittent renewables concentrated in the windy north and offshore zones while the bulk of demand remains in the south and southeast.
As a result, clean electricity is sometimes constrained or even paid to switch off while gas plants still fire up elsewhere. Upgrading transmission capacity is expensive, slow, and often unpopular with communities asked to host new pylons or substations. Until that infrastructure gap closes, the theoretical potential of renewables cannot fully translate into lower bills or greater energy security for households.
I’ve spoken with people in the sector who describe this mismatch as the single largest practical barrier remaining. Building more generation without matching network capacity is like pouring water into a bottle with a narrow neck. Eventually the bottle overflows, and the overflow is wasted potential.
Household Choices and the Cost of Change
For most families the energy transition still arrives through the monthly bill and the occasional large purchase decision. Heat pumps remain significantly more expensive to install than like-for-like gas boiler replacements, even after subsidies. Electric vehicles have fallen in price, yet many households still face higher upfront costs and lingering questions about charging infrastructure, especially outside major cities.
The distribution of those costs matters. Urban professionals in modern homes often find the transition manageable. Rural households with older properties, limited public transport, and oil heating face a steeper climb. When policy treats every household as equally able to absorb change, political resistance grows. That resistance is already visible in opinion surveys and local election results.
A more gradual approach that prioritises the most cost-effective measures first may ultimately prove more durable. Improving home insulation, for example, reduces demand regardless of the heating technology that follows. Expanding reliable public charging networks makes electric vehicles practical for more drivers. These steps lack the drama of sweeping bans, yet they build the foundation that later targets will need.
Industrial Reality and Global Competition
Manufacturing and heavy industry face their own version of the same dilemma. Processes that rely on high-temperature heat or chemical feedstocks derived from fossil fuels cannot simply switch overnight. Carbon capture, hydrogen, and electrification all offer pathways, yet each carries high capital costs and uncertain commercial returns in the near term.
Companies operating in global markets also watch competitors in countries that move more slowly on climate regulation. If domestic policy raises costs without equivalent action elsewhere, production can simply migrate. That outcome reduces UK emissions on paper while doing little for global totals and potentially weakening the domestic industrial base. The tension between climate ambition and industrial competitiveness is no longer theoretical; it shapes investment decisions every quarter.
Making the transition manageable and affordable is not a retreat from a net-zero future. It is simply a realistic way of getting there.
That perspective has gained ground even among those who remain strongly committed to the long-term goal. Rapid progress in electricity has shown what focused policy can achieve. Extending that success into harder sectors requires similar focus on cost, technology readiness, and public consent rather than purely on target dates.
What a More Pragmatic Path Might Look Like
A realistic strategy would keep the 2050 destination while treating interim milestones as guides rather than rigid commandments. It would accelerate grid reinforcement so that existing and planned renewable capacity can actually reach consumers. It would prioritise the lowest-cost carbon reductions first and expand support for households that face the highest barriers to change.
Domestic oil and gas production would be viewed through a dual lens: reducing import dependence in the short and medium term while technology and infrastructure for deeper decarbonisation mature. New licences would not be automatic, yet neither would blanket bans that simply shift production and associated emissions overseas.
On the consumer side, clearer long-term signals matter more than sudden bans. Manufacturers need predictability to invest in heat-pump and electric-vehicle supply chains. Installers need steady demand to train workers and build capacity. Households need confidence that the technologies they are asked to adopt will be reliable and affordable over their full lifetime.
- Accelerate electricity network upgrades to unlock existing renewable potential
- Focus early support on the most cost-effective household measures such as insulation
- Maintain flexibility on technology pathways rather than locking in single solutions too early
- Balance domestic energy security with long-term emissions goals
- Communicate realistic timelines so public trust does not erode further
Lessons From the First Half of the Journey
Britain’s rapid decarbonisation of electricity remains a genuine success story. Renewables rose from a tiny share of the mix two decades ago to more than half in recent years. That achievement was built on consistent policy, falling technology costs, and a willingness to retire older high-carbon generation. The second half of the transition will require the same ingredients applied to more complex systems.
One clear lesson is that targets alone do not deliver outcomes. Delivery depends on infrastructure, skills, supply chains, and public acceptance. When any of those elements lags, the targets themselves begin to lose credibility. Restoring credibility may require fewer headline dates and more visible progress on the practical enablers of change.
Another lesson concerns fairness. Policies that impose steep costs on households with limited options generate political backlash that can set the broader agenda back years. Designing support that reaches the people who need it most is not merely a social concern; it is a practical requirement for sustained progress.
Looking Ahead Without Illusions
The 2050 net zero goal still sits on the statute book. Whether it is achieved will depend less on the legal wording and more on the cumulative effect of thousands of investment, technology, and behavioural decisions over the coming decades. The recent scaling back of interim targets is best understood as an acknowledgment that earlier timelines underestimated the difficulty of the remaining work.
Some will view every delay as a betrayal of climate responsibility. Others will see it as overdue realism. The truth, as is often the case, sits somewhere in between. Britain has already demonstrated that rapid emissions reductions are possible when the conditions align. Extending that success into homes, transport, and industry will require patience, better infrastructure, and policies that keep the public on side rather than asking them to absorb costs they cannot easily bear.
In the end the energy transition is not a single leap but a long series of practical steps. The current moment of recalibration may feel uncomfortable to those who preferred the earlier rhetoric of rapid transformation. Yet if it produces a more durable and affordable path, it may ultimately serve the original goal better than sticking rigidly to targets that were always going to prove difficult to meet.
The coming years will reveal whether the government can turn this quieter, more pragmatic approach into tangible progress on the ground. Households will judge the outcome not by distant legal deadlines but by the size of their energy bills, the reliability of the system, and the sense that the transition is being managed with their interests in mind. That, more than any single policy announcement, will decide how far and how fast Britain continues to move toward a lower-carbon future.
For investors, businesses, and families alike, the message is becoming clearer. The direction of travel remains, yet the pace is being adjusted to match what the economy and society can realistically sustain. Understanding that adjustment, and planning around it, may prove more valuable than clinging to earlier assumptions that no longer match the evidence on the ground.
The story of Britain’s climate targets is still being written. The latest chapter is less dramatic than some of the previous ones, yet it may turn out to be more decisive. Reality has a way of asserting itself. The question now is how skilfully the country adapts.