
Have you noticed how every time you check flight prices lately the numbers seem to keep climbing? I found myself staring at a booking screen last week wondering why a simple domestic hop felt more expensive than it did just a few months ago. Turns out the answer sits partly with fuel, and United Airlines just put some hard numbers on that reality for the rest of 2026.
United Airlines Lowers Full-Year Profit Expectations
United Airlines came out with its third-quarter results and a fresh set of guidance numbers that caught quite a few people off guard. The carrier now expects adjusted earnings between 50 cents and $1.50 per share in the fourth quarter. That range sits well below what many analysts had been modeling. At the top end of that forecast, full-year adjusted earnings would land no higher than $7.22 a share. Back in July the company had pointed toward a much stronger $9 to $11 range for the entire year. The gap is real and it comes down mostly to one stubborn cost: jet fuel.
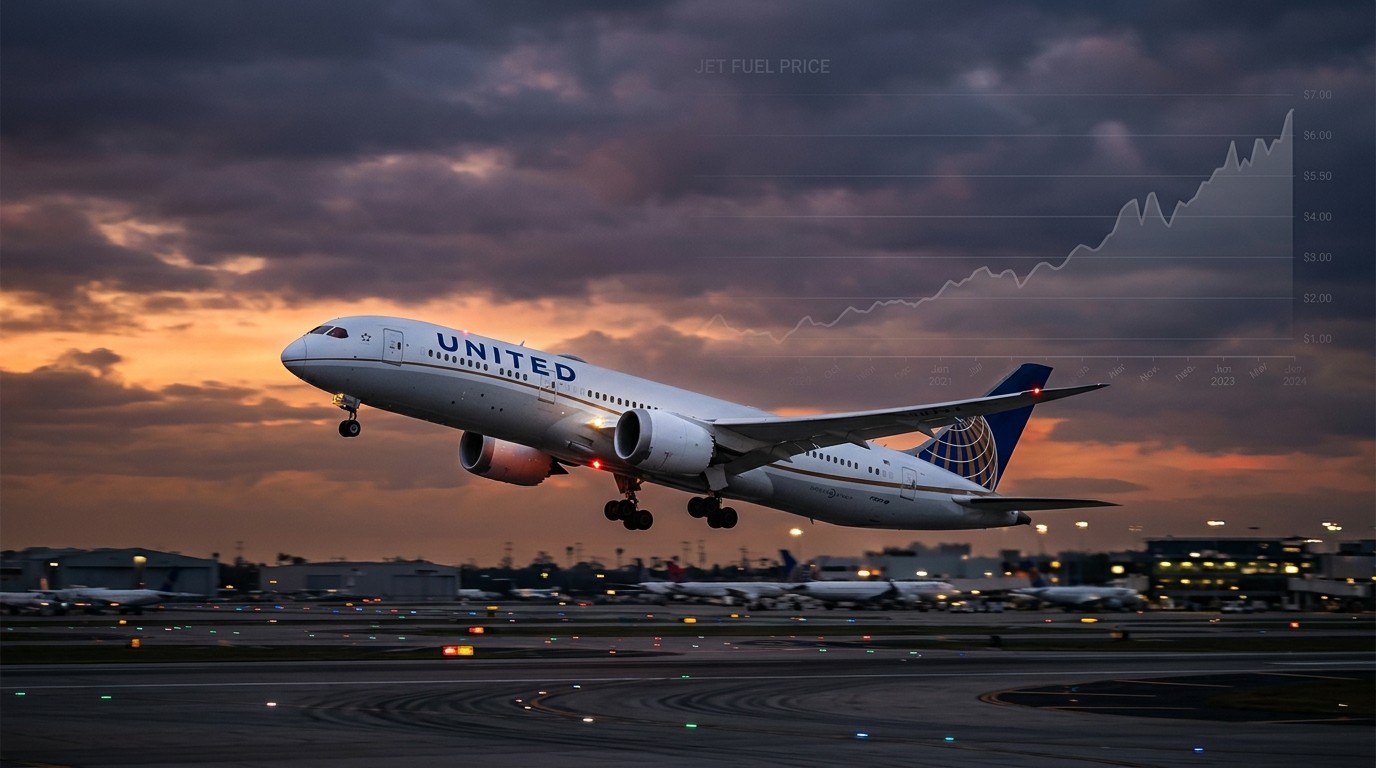
Fuel is the single largest expense for most airlines after labor, and the recent climb has been painful. United now anticipates paying an average of $4.80 a gallon in the fourth quarter. That is a noticeable jump from the $3.90 average it saw in the third quarter. Those extra dollars per gallon add up fast across a fleet that burns millions of gallons every day. I’ve watched fuel swings for years and this kind of move always forces management teams to recalibrate their outlooks quickly.
What the Third-Quarter Numbers Actually Showed
Even with the forward-looking caution, the third quarter itself looked solid on the surface. Adjusted earnings came in at $2.54 per share, just a touch under the $2.57 consensus. Revenue hit $17.88 billion against expectations of roughly $17.9 billion. Net income rose 8.5 percent year over year to $1.03 billion, or $3.14 per share on a reported basis. A year earlier the company had posted $949 million, or $2.90 a share. Revenue climbed 17.4 percent from the prior-year period, reaching $17.88 billion from $15.23 billion.
Unit revenue told an interesting story. Domestic passenger unit revenue increased 14.5 percent, while international unit revenue rose 17.4 percent. Those gains point to higher average fares rather than simply more empty seats filled. Passenger counts themselves were up more than 2 percent from last year. People are still traveling. They are just paying more for the privilege, and the airline is collecting that extra revenue even as fuel eats into the bottom line.
In my view the demand picture remains the more encouraging part of the release. Airlines can manage costs to a degree, but they cannot invent passengers if people decide to stay home. Right now travelers appear willing to keep booking despite the higher ticket prices that usually accompany elevated fuel costs.
Why Fuel Costs Hit So Hard This Year
Jet fuel does not move in isolation. Global crude markets, refining capacity, geopolitical tensions, and even seasonal demand for diesel all play a role. When the price at the rack jumps, airlines feel it almost immediately because most of them do not hedge as aggressively as they once did. United is no exception. The jump from $3.90 to an expected $4.80 a gallon represents a meaningful hit that flows straight through the income statement.
I’ve found that periods of rising fuel often create a temporary disconnect between top-line strength and bottom-line results. Revenue can look healthy while margins compress. That is exactly the dynamic United is describing. Strong bookings and higher fares are helping, yet they have not been enough to offset the full impact of the fuel surge on full-year earnings.
A surge in fuel prices this year has added billions of dollars to airlines’ costs, eating into profits despite strong demand and driving up airfares.
That simple statement captures the tension every major carrier is navigating right now. Demand is there. Pricing power exists. The cost side, however, refuses to cooperate.
Passenger Behavior Remains Resilient
Perhaps the most interesting aspect of the update is the continued willingness of customers to book. Passenger counts up more than 2 percent year over year may not sound dramatic, yet in an environment of higher fares it signals underlying strength. People are not walking away from travel the way some observers feared they might once prices started climbing.
Domestic unit revenue up 14.5 percent and international unit revenue up 17.4 percent both point to the same conclusion: average fares are higher. Airlines have managed to push prices without seeing a collapse in volume. That combination is rare and valuable. It suggests that leisure travelers still prioritize trips and that corporate demand has recovered enough to support premium pricing on many routes.
I keep coming back to the idea that travel has become less discretionary for many households than it was a decade ago. Experiences matter. Family visits, milestone trips, and even the simple desire to get away after long stretches of work seem to hold firm even when the ticket price stings a little more. United’s numbers support that view.
Implications for the Rest of the Airline Industry
United is not operating in a vacuum. When one of the largest network carriers revises its full-year outlook downward because of fuel, the rest of the industry pays attention. Other airlines face the same fuel environment. Some may have different hedging strategies or route networks that provide a modest buffer, yet the broad direction remains similar.
Higher fuel costs tend to push fares higher across the board over time. Carriers try to recover the extra expense through ticket prices, ancillary fees, and careful capacity management. The risk is always that demand eventually softens if prices rise too far. So far that tipping point does not appear to have been reached. The fact that United can still report rising passenger counts while cutting its profit outlook tells you demand is absorbing the price increases for now.
Capacity decisions will matter in the coming months. Airlines that grow too aggressively while fuel stays elevated can dilute unit revenue and pressure margins further. Those that hold capacity steady or grow modestly may protect yields better. United’s commentary suggests it is watching the balance carefully.
What This Means for Travelers Right Now
If you are planning trips over the next few months, the message is fairly clear. Fares are unlikely to drop sharply in the near term while fuel remains elevated. The combination of solid demand and higher operating costs gives airlines little incentive to discount heavily. That does not mean every route will be expensive, of course. Competitive markets and off-peak travel windows still offer opportunities. But the overall direction of pricing has an upward bias.
I’ve started looking further ahead when I book and being more flexible on travel dates. Those two habits often unlock better prices even in a firm fare environment. Loyalty programs and credit-card points also become more valuable when cash fares rise. None of that is new advice, yet the current cost pressure makes it more relevant.
Business travelers face a slightly different calculation. Higher fares on last-minute or flexible tickets can add up quickly. Companies that once defaulted to premium cabins may push more employees into economy or encourage earlier booking to lock in lower rates. The data on unit revenue suggests those adjustments are already happening in some segments, though overall demand has held up.
Investor Perspective on the Guidance Cut
From an investor standpoint the lowered full-year outlook is the headline. Moving from a $9 to $11 range down to a high end of $7.22 is a meaningful revision. Markets tend to dislike negative guidance changes, especially when they stem from a cost item that management cannot fully control. At the same time, the underlying demand trends remain constructive. That mixed picture often produces volatility in the shares rather than a one-way move.
The fourth-quarter guidance of 50 cents to $1.50 in adjusted earnings sits well below prior expectations near $1.76. The midpoint of the new range implies a soft finish to the year on a profit basis even if revenue continues to grow. Investors will watch fuel prices closely over the next several weeks. Any sustained pullback in jet fuel would create upside to the current outlook. Continued strength or further increases would keep pressure on margins.
Balance-sheet strength and free-cash-flow generation also matter in this environment. Airlines that entered the year with solid liquidity are better positioned to weather a period of compressed margins. United has worked on its balance sheet in recent years, and that work provides some cushion. Still, earnings power is what drives valuation multiples over time, so the reduced 2026 outlook will likely factor into how the market values the stock near term.
Looking at the Broader Cost Picture
Fuel is the most visible pressure, yet it is not the only one. Labor costs have risen across the industry after successive rounds of contract negotiations. Maintenance, airport fees, and aircraft ownership expenses continue their gradual climb. When fuel jumps on top of those existing pressures, the combined effect shows up quickly in guidance.
Airlines have become more disciplined about capacity than they were in previous cycles. That discipline helps protect unit revenue when costs rise. United’s ability to grow passenger counts modestly while lifting unit revenue substantially suggests the network is being managed with an eye on profitability rather than pure market share. That approach is more sustainable, in my experience, than the old habit of flying every available seat regardless of yield.
Technology and operational efficiency also play a role. Better matching of aircraft size to demand, improved turn times, and more sophisticated revenue-management systems all help offset some of the cost inflation. None of those tools fully neutralize a 90-cent jump in fuel per gallon, but they soften the blow.
Historical Context for Fuel Spikes
This is not the first time airlines have faced a rapid rise in fuel prices. Previous spikes forced capacity cuts, fare increases, and in some cases industry consolidation. The difference this time is that demand has recovered more fully from earlier disruptions and corporate travel has regained much of its previous strength. That recovery gives carriers more pricing power than they possessed during some earlier fuel shocks.
I remember periods when fuel ran up and demand was soft at the same time. Those combinations proved far more damaging. Today the demand side is holding, which changes the math. Airlines can pass through a portion of the higher costs. The open question is how much of the increase they can ultimately recover without dampening future bookings.
Hedging strategies have also evolved. Many carriers reduced their hedge books after years of mixed results. That decision leaves them more exposed to spot-price moves in both directions. When prices fall they benefit fully. When prices rise they feel the full impact. United’s current guidance reflects that greater exposure.
Potential Paths for the Fourth Quarter and Beyond
Several variables will determine whether United lands near the high or low end of its new fourth-quarter range. Fuel prices themselves sit at the top of the list. A sustained drop in crude or refining margins would help. Weather, holiday travel patterns, and any unexpected shifts in corporate demand also matter. International routes have shown particularly strong unit-revenue growth, so continued strength there would provide a useful offset.
Looking further ahead into 2027, the key question becomes whether fuel stabilizes at a lower level or remains elevated. If prices settle closer to the third-quarter average, margins could recover relatively quickly. If they stay near current levels, airlines will need to keep fares firm and capacity disciplined to protect profitability. Neither path is guaranteed, which is why management teams are cautious in their public comments.
I’ve learned over the years that airline guidance often proves conservative when demand is resilient. The current cut is sizable, yet the passenger trends give some reason for measured optimism. The next few monthly traffic updates will be worth watching closely for any signs of softening.
How Capacity and Fleet Decisions Factor In
United, like its peers, has a long-term fleet plan that includes new aircraft deliveries. Those planes are more fuel-efficient than the older models they replace. Over time the improving efficiency helps mitigate some of the cost pressure. In the short run, however, delivery delays and the need to keep older aircraft flying can limit the benefit. The transition is gradual rather than sudden.
Decisions about how many seats to fly in the coming quarters will influence both revenue and cost. Too much capacity risks lower load factors and weaker yields. Too little capacity leaves money on the table when demand is solid. The art of airline management lies in finding the right balance, and the current fuel environment raises the stakes of those decisions.
Premium cabin performance also deserves attention. Higher-margin seats in business and premium economy have been important contributors to revenue growth across the industry. As long as corporate and high-end leisure demand remains healthy, those cabins can help offset some of the fuel pressure on the main cabin.
The Human Side of Higher Airfares
Behind the earnings numbers sit millions of individual travel decisions. Families weighing whether a holiday trip still fits the budget. Business travelers deciding if an in-person meeting justifies the higher ticket price. Students planning study-abroad or spring-break itineraries. Each of those decisions adds up to the passenger-count and unit-revenue figures United just reported.
In my experience most people still find a way to take the trips that matter most to them. They may choose a less convenient connection, travel midweek, or pack lighter to avoid bag fees. The desire to move around the country and the world has proven remarkably durable. That durability is what allows airlines to raise fares without immediately losing volume.
At the same time, there is a limit. If fuel-driven fare increases continue for several more quarters, some marginal trips will get postponed or cancelled. The industry has not reached that point yet according to the latest data, but it remains a risk worth monitoring.
Putting the Numbers in Perspective
A quick look at the key figures helps frame the situation:
| Metric | Reported / Guided | Context |
| Q3 Adjusted EPS | $2.54 | Slightly below $2.57 expected |
| Q3 Revenue | $17.88 billion | Up 17.4% year over year |
| Q4 Adjusted EPS Guidance | $0.50 – $1.50 | Below prior $1.76 consensus |
| Full-Year High-End Outlook | $7.22 | Down from prior $9–$11 range |
| Q4 Fuel Price Assumption | $4.80 per gallon | Up from $3.90 in Q3 |
| Passenger Count Growth | More than 2% | Despite higher fares |
Those numbers tell a coherent story. Near-term results were largely in line. Forward-looking profitability is under pressure from fuel. Demand continues to support higher fares and modest volume growth. The combination is neither a disaster nor a clean win. It is a classic airline-industry balancing act.
What to Watch in the Coming Weeks
Several data points will clarify the outlook. Monthly traffic reports will show whether passenger trends remain steady. Fuel-price movements will determine how much of the current cost pressure sticks. Commentary from other major carriers will reveal whether United’s experience is unique or shared across the industry. Finally, any updates on corporate travel demand will help assess the durability of the higher unit-revenue figures.
I plan to keep an eye on all of those signals. Airline stocks can move quickly on shifts in fuel or demand, and the current environment offers both risk and opportunity. For travelers the practical takeaway is simpler: book with some flexibility and expect fares to stay firm while fuel remains elevated.
The third-quarter report and revised guidance together paint a picture of an industry that is still generating solid revenue growth yet struggling to translate that growth into the same level of profit it anticipated earlier in the year. Fuel is the main culprit. Demand is the main offset. How those two forces interact over the next two quarters will shape both airline earnings and the prices passengers pay for seats.
United has shown it can attract passengers and raise average fares even in a tougher cost environment. That capability provides a foundation. The challenge now is protecting as much of the margin as possible until fuel costs ease or efficiency gains catch up. For anyone who follows the sector or simply buys plane tickets, the next few months will offer a live case study in how airlines navigate a classic cost shock while demand stays resilient.
In the end the story is less about one quarter’s numbers and more about the ongoing tension between operating costs and customer willingness to pay. Right now customers are still showing up. The profit outlook has been lowered to reflect reality. Both facts can be true at the same time, and that is exactly the situation United Airlines is managing as 2026 heads into its final stretch.