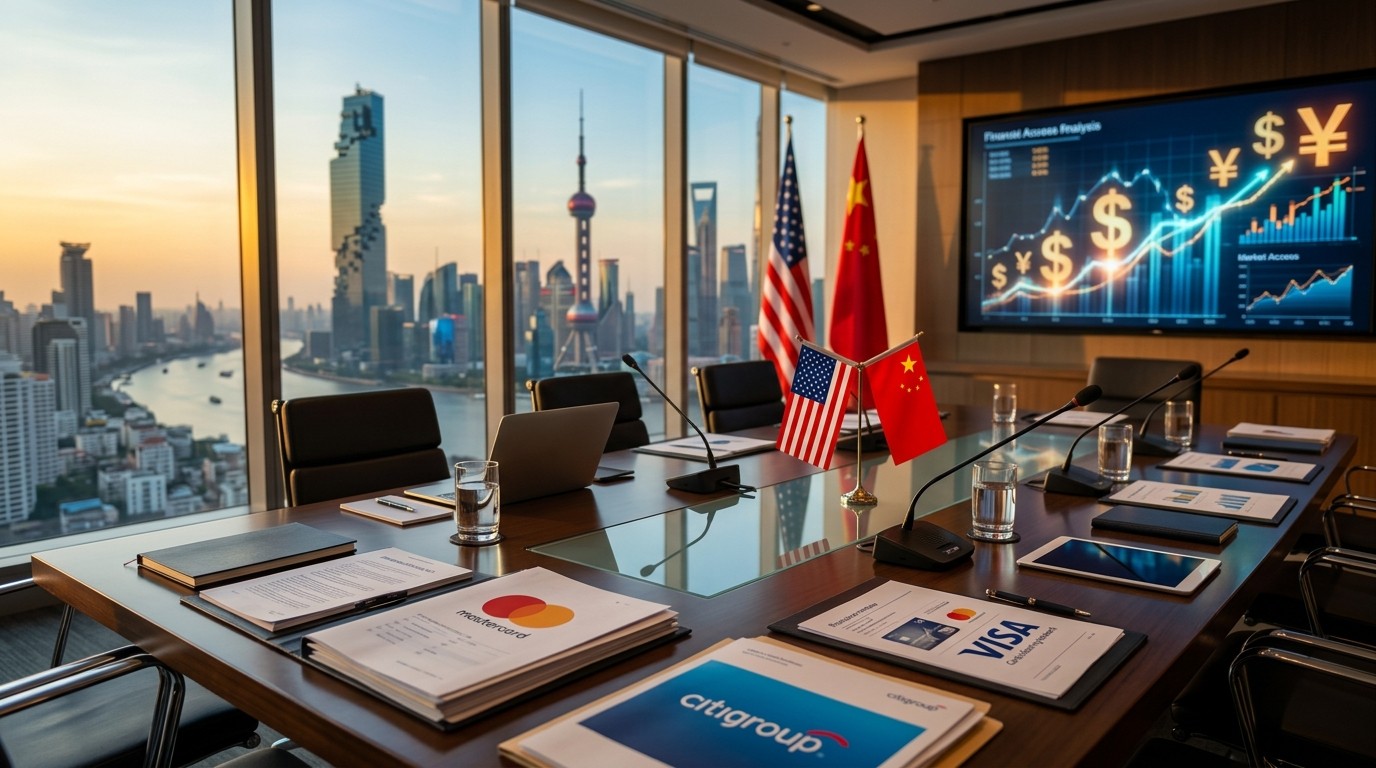

I still remember the quiet tension that hung over global markets last month when two presidents sat down in Washington. Everyone wondered whether the handshake would actually turn into something concrete. This week in Bangkok, we got a clearer answer. US officials raised specific market access questions for Mastercard and Citigroup during closed-door talks with their Chinese counterparts, and the details are starting to matter more than the headlines.
What Really Happened in Those Bangkok Meetings
The meetings took place on the sidelines of the Group of 20 finance gatherings and the annual IMF-World Bank sessions. A Treasury team led by Deputy Secretary Francis Brooke sat down with officials from the People’s Bank of China and the finance ministry. According to a US Treasury official speaking on condition of anonymity, the conversations focused squarely on market access for American financial firms.
Mastercard, Visa and Citigroup all came up. The official made clear that regulatory approvals formed part of the broader agreement reached when President Trump met Chinese leader Xi Jinping in Washington last month. These Bangkok sessions were about implementation, not new promises. That distinction feels important. Talk is cheap in diplomacy. Actual progress on licenses is what investors watch.
China’s central bank, its National Financial Regulatory Administration, the securities regulator, and the relevant embassies did not respond right away to requests for comment. Neither did Visa. Citigroup and Mastercard simply declined to say anything. Silence is normal in these situations, yet the lack of denial often speaks louder than a carefully worded statement.
Visa Already Moved Ahead
Just three days before the Bangkok talks, China gave Visa the green light to start preparing a wholly owned domestic card-clearing business. The company now has up to a year to get ready before it applies for a full operating license. That step marks a real shift. For years foreign card networks operated under tight restrictions or through joint ventures. A wholly owned entity changes the competitive landscape.
I’ve followed the payments space long enough to know that clearing licenses are the real prize. Without the ability to clear transactions independently, foreign networks remain guests in someone else’s house. Visa’s approval suggests Beijing is willing to open the door wider, at least for selected players.
Mastercard currently runs yuan card payments through a joint venture with NetsUnion Clearing Corp. That arrangement started operations in 2024. The pending approval under discussion would let Mastercard operate as a fully independent player. The difference between a joint venture and a wholly owned subsidiary is not just legal paperwork. It affects strategy, technology control, and long-term profitability.
Citigroup’s Securities Ambitions
Citigroup has been quieter but no less determined. The bank has already hired several dozen people for its China unit and plans to grow that team to around one hundred. Its goal is a wholly owned securities license that would allow A-share brokerage, underwriting, research and principal trading in the onshore market.
The application went in back in late 2021. Recent reports suggested approval could arrive soon. In Bangkok the US side brought the topic up again. Timing matters. When political will aligns with regulatory processes, licenses that sat for years can move quickly. When that alignment disappears, applications gather dust.
One person familiar with the situation noted that Citigroup sees China as a long-term growth market despite the well-known challenges. That view is not universal on Wall Street, yet the bank’s continued investment in people and infrastructure suggests genuine conviction rather than mere political posturing.
Why These Approvals Matter Beyond the Headlines
China began opening its financial sector more seriously in 2018. Foreign ownership caps on securities, futures and fund management firms gradually disappeared. Yet payments and certain capital-market activities remained tightly controlled. Domestic players still dominate card clearing and many onshore securities businesses. Cross-border capital flows face restrictions that can frustrate foreign institutions.
Licensing American firms is often described as a limited concession. In my view that description is accurate but incomplete. Even limited openings create precedent. Once one network or bank receives full independence, others can point to the same treatment. Competitors notice. Regulators notice. Investors notice.
The move suggests the US-China trade environment remains benign, and Beijing is keen to keep up the momentum. Licensing US financial firms is a limited concession on market access, though it signals China is continuing to open up, and this should marginally bolster investor confidence in Chinese assets.
That assessment from a seasoned China analyst captures the mood well. Markets do not need dramatic breakthroughs every week. They need evidence that agreements reached at the presidential level actually translate into operational reality on the ground.
The Broader Diplomatic Context
Trump and Xi are expected to meet again in November in Shenzhen during the Asia-Pacific Economic Cooperation summit. That will be their third face-to-face encounter this year. Each meeting raises the stakes for follow-through. If Bangkok produced only polite discussions with no subsequent movement, the next summit becomes harder. If licenses begin to appear, both sides can claim progress.
Financial market access sits at the intersection of trade, security and domestic politics. American firms want the chance to compete on equal terms. Chinese authorities want to modernize their markets without losing control over systemic risk or capital flows. Those two goals do not always align neatly. The current process looks like a careful attempt to find workable middle ground.
Perhaps the most interesting aspect is the sequencing. Visa received preparation approval first. Mastercard and Citigroup are next in the conversation. The order suggests deliberate pacing rather than sudden liberalization. Beijing appears to be testing the waters while extracting whatever diplomatic or commercial reciprocity it can.
What Success Would Look Like for the Firms
For Mastercard, independent clearing capacity means greater control over technology, data and pricing. Joint ventures force compromise. Wholly owned structures allow global product standards to be applied more consistently. That matters when competing against established domestic networks that already enjoy deep merchant relationships and government support.
Citigroup’s securities ambitions are more complex. A-share brokerage and underwriting require local research teams, trading infrastructure and client relationships built over years. The bank has already invested in hiring. A license would unlock the ability to monetize that investment fully. Without it, the headcount remains a cost center rather than a revenue engine.
- Independent card clearing removes the need for local joint-venture partners
- Full securities licenses open brokerage, underwriting and principal trading
- Staffing growth signals long-term commitment beyond symbolic presence
- Regulatory timelines of up to one year create clear milestones for investors
These steps will not transform the competitive landscape overnight. Domestic players retain enormous advantages in distribution, brand recognition and regulatory familiarity. Still, the direction of travel matters more than the absolute size of any single license.
Investor Implications and Market Sentiment
Investors watching Chinese assets have grown used to mixed signals. Policy announcements that sound liberalizing often come with fine print that preserves control. Genuine progress on foreign financial access therefore carries extra weight. It suggests that at least some channels remain open even when broader geopolitical tensions rise and fall.
In my experience, markets reward consistency more than sudden leaps. A series of incremental approvals can do more for confidence than one dramatic reform that later gets walked back. The current pattern looks closer to the incremental approach.
Equity investors in the payments and banking names will watch for concrete license grants rather than meeting statements. Options markets may begin pricing higher volatility around the November summit if further announcements appear likely. Fixed-income investors focused on Chinese assets will note any improvement in the overall risk narrative.
Challenges That Still Remain
None of this removes the structural constraints. Capital account convertibility remains limited. Data localization rules continue to complicate operations for foreign firms. Political risk can reappear quickly if broader trade or technology disputes escalate. Licensing is necessary but not sufficient for long-term commercial success.
Foreign institutions also face intense competition from domestic giants that have spent decades building scale. A license grants the right to compete. It does not guarantee market share. Execution, local talent retention and product adaptation still decide outcomes.
I’ve seen too many optimistic forecasts about China market openings that later disappointed. The current moment feels different mainly because the political sponsorship at the highest levels is more explicit. That sponsorship can accelerate regulatory processes. It can also evaporate if priorities shift.
Looking Ahead to the Next Summit
The November meeting in Shenzhen will offer the next natural checkpoint. Both sides will want deliverables to show. Additional progress on Mastercard or Citigroup could serve that purpose. Conversely, any slowdown would raise questions about the durability of the Washington understandings.
For now the Bangkok talks represent quiet but meaningful follow-through. US officials raised specific company names. Chinese counterparts engaged. Visa already received preparation approval. The machinery of implementation appears to be turning, even if the pace remains deliberate.
Market access in China has never been a straight line. It moves in fits and starts, influenced by domestic priorities, external pressure and political timing. The latest developments suggest that the window opened in Washington last month has not closed. Whether it widens further depends on the next rounds of conversation and the actual licenses that follow.
The story is still unfolding. American financial firms have waited years for clearer pathways into one of the world’s largest consumer and capital markets. The current diplomatic engagement offers the best chance in some time to convert high-level agreements into operational reality. That alone makes the Bangkok discussions worth watching closely.
Practical Takeaways for Market Watchers
Anyone tracking these developments should keep several points in mind. First, the distinction between preparation approval and full operating license is real. Visa’s one-year runway shows how staged the process remains. Second, staffing decisions by Citigroup reveal more about genuine commercial intent than press releases ever could. Third, the political calendar matters. High-level summits create deadlines that can accelerate or stall bureaucratic processes.
Finally, the broader environment still mixes openness with control. China continues to invite foreign participation in selected areas while retaining tools to manage systemic risk and capital flows. That dual approach is unlikely to disappear soon. Firms that succeed will be those that navigate both the opportunities and the constraints with equal skill.
The Bangkok meetings may not generate dramatic front-page news on their own. Yet they form part of a longer sequence that began with a presidential visit and may continue through further summits and regulatory decisions. In the patient world of financial market access, such sequences often prove more important than any single announcement.
I find myself cautiously optimistic. Not because every barrier has fallen, but because concrete company-level issues are being discussed at senior levels and some approvals are already moving. That combination has been rare in recent years. If it continues, the impact on American financial firms operating in China could become material over the medium term.
The coming months will test whether the momentum holds. For now the evidence points to steady, if unspectacular, progress on issues that matter to Mastercard, Citigroup and the broader US financial industry. In a relationship as complex as the one between Washington and Beijing, steady progress is often the best outcome available.