
Have you noticed how a single fuel can quietly set the tempo for an entire economy? I keep coming back to that question whenever diesel shows up in policy briefings, freight invoices, and grocery markups at the same time. It is not a glamorous commodity. It does not get the same dinner-table chatter as gasoline. Yet it moves food, construction materials, factory output, and just about every last-mile delivery that keeps cities from stalling. When officials start talking about emergency stocks and export bans, the story is no longer a niche energy file. It is a winter-risk story with a price tag attached.
Why A Diesel Showdown Now Matters More Than Headlines Suggest
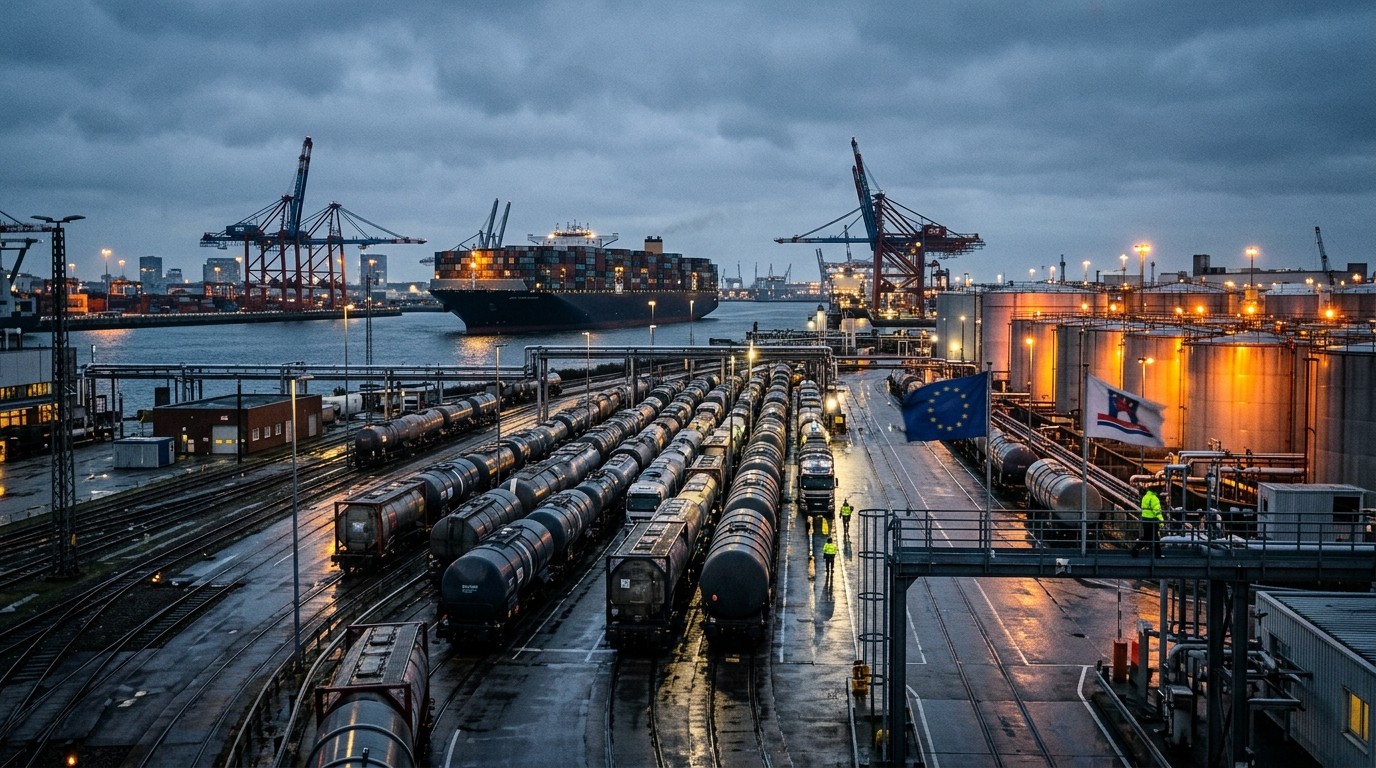
The refined products crunch has not faded as the Northern Hemisphere winter draws closer. In public remarks from the Oval Office, the US president said conversations about a possible diesel export ban happen almost daily. The administration is pointing at the war in Ukraine as a major driver of the squeeze and is pressing European governments to release emergency diesel inventories. The message is blunt: create a buffer now, or face the prospect of restricted American shipments.
According to officials familiar with the talks, Washington has asked Germany and France to tap strategic diesel holdings. The broader request, as described by a source in a European capital, is for roughly 120 million barrels over six months. That works out to something like 660,000 barrels a day of extra supply if the volumes actually reach the market. I have found that numbers of that size tend to sound abstract until you translate them into trucks, harvests, and heating demand. Then they feel very concrete.
It is in Europe’s best interest to work with the United States as we pursue multiple pathways to boost the supply of refined products and lower costs for consumers.
– A US official
That line is diplomatic on the surface. Underneath it sits a harder calculation. The United States remains a major supplier of diesel and other middle distillates to the Atlantic Basin. If those barrels stay home, European buyers must scramble. If those barrels keep flowing, American consumers may keep asking why domestic pump prices still sting. Policy rarely offers a clean win in this corner of the energy market.
The Winter Clock Is Already Running
Winter does not wait for committee meetings. Heating demand rises. Agricultural logistics tighten around late-year shipments. Construction slows in some regions and accelerates in others before frost sets in. Diesel sits in the middle of all of it. I have watched this pattern enough times to know that markets do not need a full-blown shortage to inflict damage. They only need the fear of one.
Elevated diesel prices across the West raise the odds of an economic shock, according to commodity strategists who compare the setup with past energy squeezes. The comparison is not perfect. No two crises rhyme line for line. Still, the mechanism is familiar: costly freight raises the price of nearly everything that travels by road. Weak balance sheets in trucking feel it first. Then retailers feel it. Then households feel it in quieter ways, one receipt at a time.
Perhaps the first crack is already visible. A cluster of US trucking firms has filed for bankruptcy in a short stretch as diesel costs climbed. That does not prove a system-wide collapse. It does show how thin the margin can be when fuel is both a daily input and a financial stress test. In my experience, people underestimate how fast a fuel spike moves from a tanker rack to a layoff notice.
What An Export Ban Would And Would Not Fix
The president warned that an export restriction could weigh on gasoline prices even if it helped diesel. That trade-off is easy to miss in partisan noise. Refineries do not produce one product in isolation. They run a slate. Change the export channel for diesel and you can change the economics of the whole barrel. Sometimes that helps the product politicians want to help. Sometimes it does not.
Russia has also extended its own export limits on industrial fuel. That matters because global diesel trade is a network, not a single pipe. When one large exporter tightens, other regions inherit the tightness. Dark-export estimates have recently helped lift Persian Gulf crude shipments back toward prewar rates in some weekly snapshots. Refined product exports, by contrast, have lagged well behind recent-year averages. Crude availability and product availability are not the same story. Anyone who treats them as identical is going to misread the market.
- Crude can look ample while diesel remains scarce at the rack.
- Refinery outages, maintenance, and conversion limits can bottleneck supply even when oil is available.
- Policy bans can reroute barrels without creating new molecules.
- Seasonal demand can overwhelm paper inventories that look fine on a spreadsheet.
Energy analysts have warned that the refining squeeze may linger well beyond a single winter. One view circulating among market desks is that pain at the pump and at the diesel rack could stretch into 2027. I am not in the prediction business, and long-range calls are often humbled by weather, geopolitics, or a surprise capacity addition. Even so, the direction of the warning is useful: this is not being framed as a two-week inconvenience.
Europe Caught Between Allies, Rivals, And Its Own Choices
Europe looks boxed in. Some of the damage traces back to the Russia-Ukraine war. Some traces back to wider Middle East disruption. Some traces back to Chinese product flows and buying patterns. A sizable share, as market commentators have argued, is self-inflicted through refinery closures, slow permitting, and policy mixes that reduced local processing capacity while demand for freight fuel stayed stubborn.
Europe is finding itself sandwiched from all sides when it comes to refined products, diesel in particular. Policy response: head in the sand.
That is a harsh verdict. Is it entirely fair? Not always. European governments have spent years trying to cut emissions, modernize fleets, and reduce exposure to unstable suppliers. Those goals are not frivolous. The trouble is timing. You can retire refining capacity faster than you can retire diesel demand. When those two clocks are out of sync, prices do the talking.
The US energy secretary said announcements from Europe about tapping emergency diesel supplies could come soon. That sentence is doing a lot of work. It tells markets that Washington expects movement. It also tells European capitals that delay itself is now a political signal. I have found that “very soon” in energy diplomacy can mean next week or next quarter. Traders will not wait politely for the press conference.
How Emergency Stocks Actually Work In Practice
Strategic inventories sound like a magic vault. They are not. Releasing barrels can calm a spike if the market believes more supply is truly arriving. If the release is too small, too late, or too wrapped in conditions, prices may barely blink. Worse, a poorly timed release can leave countries thinner just as a second shock arrives. That is the classic dilemma of emergency reserves: use them too early and you look reckless; use them too late and you look irrelevant.
There is also the question of quality and location. Diesel sitting in one country is not instantly diesel at a German truck stop or a French distribution terminal. Logistics, barge traffic, pipeline constraints, and blending specs all matter. A headline number of 120 million barrels can shrink once you ask where the fuel is, who owns it, and how fast it can move.
| Policy Lever | Intended Effect | Main Risk |
| European stock release | Add near-term diesel supply | Weaker buffer if another shock hits |
| US export restriction | Keep more diesel at home | Higher European prices and trade friction |
| Refinery run increases | Create more actual product | Maintenance limits and crack-spread swings |
| Demand restraint | Ease pressure on tight markets | Slower freight and industrial activity |
Look at that grid long enough and you see why nobody loves the menu. Every option has a hangover. That is usually a sign the physical market is tight, not that politicians are uniquely clumsy. Tight markets punish delay and punish overreaction with almost equal enthusiasm.
The Quiet Transmission From Diesel To Daily Life
People still treat diesel as a trucker’s problem. It is not. If produce travels farther, the extra fuel cost shows up in the produce. If contractors bid higher because generators and machines drink more expensive fuel, housing and infrastructure work get pricier. If municipal fleets spend more on buses and waste collection, local budgets get squeezed. The chain is boring, which is why it is so effective. Nobody writes poetry about middle distillates. Everybody pays for them.
I keep a simple mental model for this. Gasoline is the consumer-facing fuel. Diesel is the system fuel. When gasoline jumps, voters notice immediately. When diesel jumps, the economy notices first and voters notice later. That lag is politically dangerous. By the time the complaint reaches a campaign speech, the damage may already be baked into freight contracts and retail margins.
- Spot diesel rises at the wholesale rack.
- Carriers add fuel surcharges or cut unprofitable routes.
- Shippers pass costs into wholesale goods.
- Retail prices and service bids adjust with a delay.
- Weaker operators exit, leaving less spare freight capacity.
Step five is the sleeper. Bankruptcies do not just remove companies. They remove trucks, drivers, and scheduling flexibility. The next demand surge then meets a thinner industry. That is how a fuel problem becomes a capacity problem. It does not require a cinematic shortage. It only requires a few hard months and a lot of floating-rate debt.
Refining Reality Versus Political Timelines
You cannot will a refinery into existence before winter. Permitting, capital, skilled labor, and environmental reviews take years. Even existing plants have turnaround schedules that are not optional if you want them to keep running safely. That is why “boost supply” is easier to say than to do. Product markets live on conversion capacity. If conversion capacity is tight, crude abundance is only partial comfort.
Some of the current strain is structural. Older plants have closed in the Atlantic Basin. New capacity has clustered in other regions. Trade can fill gaps until politics interrupts trade. Then the map looks different overnight. In my view, that is the least appreciated part of the present dispute. The argument is not only about barrels. It is about who gets first claim on a scarce processing system.
There is a temptation to treat an export ban as a domestic price machine. History is messier. Restrictions can lift local availability and still leave prices high if refiners change runs, if gasoline yields shift, or if traders price in future scarcity. Markets are not vending machines. They are arguments with a clearing price.
Geopolitics In The Fuel Tank
Wars reroute energy even when they do not stop it. Sanctions, insurance costs, shipping risk, and unofficial flows all reshape who sells what to whom. Analysts tracking so-called dark exports have described Gulf crude volumes recovering in recent weekly data. Product markets have not shown the same bounce. That gap should make anyone cautious about victory laps. Oil in the ground or even oil on the water is not diesel in a tank.
The Russia-Ukraine conflict remains the political center of gravity in official comments. That is understandable. It is also incomplete. Product tightness can come from several doors at once: conflict risk, weather, Chinese export policy, unplanned outages, and years of underinvestment in certain refining configurations. When several doors open together, prices do not wait to assign blame.
I am wary of single-cause stories. They travel well on television. They travel poorly through a complex trade system. If Europe releases stocks and the United States keeps exporting, prices may ease. If Europe holds stocks and Washington restricts exports, prices may lurch. If both sides hesitate, the market will invent its own answer, and that answer is usually more expensive.
What Consumers And Businesses Should Watch Next
Forget the theater for a moment. The practical checklist is shorter than the rhetoric.
- Do European governments actually authorize a meaningful stock release?
- Does any US export measure cover diesel only, or a broader product slate?
- How do crack spreads behave after the first official statements?
- Are trucking failures remaining isolated or starting to cluster by region?
- Does winter weather arrive mild, average, or brutal in major demand centers?
Those five items will tell you more than a week of commentary. Weather remains the wildcard nobody can spin. A mild season buys time. A harsh one turns inventories into a public argument almost immediately. Businesses that live on tight delivery windows should not wait for perfect clarity. Perfect clarity is a luxury this market is not offering.
If you run a fleet, the unglamorous work still matters: hedge where it is responsible, tighten routing, and avoid assuming last year’s fuel budget still applies. If you invest around industrial activity, watch freight indicators as closely as energy futures. If you simply buy groceries and pay heating bills, the transmission will be slower but no less real. I wish that were more dramatic. It is just how cost stacks work.
The Politics Of Sharing Scarcity
Alliances look generous in surplus and transactional in shortage. That is not a moral judgment. It is a description of incentives. American officials argue that European releases would help consumers on both sides by cooling a shared market. European officials have to weigh voter reaction, industrial needs, and the possibility that today’s release becomes tomorrow’s empty cupboard. Both positions can be sincere and still collide.
There is a subtle opinion I cannot quite shake: energy security speeches often celebrate independence, while energy trade quietly funds living standards. Cut the trade and you may buy a headline about control. Keep the trade and you may buy a headline about vulnerability. Governments bounce between those two scripts depending on the price of the week. Voters deserve a more honest version. Interdependence is not a slogan. It is a spreadsheet with weather on top.
Refined product markets punish delay and overreaction with almost equal enthusiasm.
That is why the next few announcements matter more than the last few speeches. Words can move a prompt contract. Physical barrels move the winter. If Europe signals a sizable, credible release and US export policy stays flexible, the worst-case freight shock becomes less likely. If talks stall, traders will treat every outage and cold front as kindling. I would rather be early in watching that fork than late in explaining it.
A Longer Crunch Than One News Cycle
Market desks have already floated the idea that refining tightness could persist for years, not months. That does not mean prices stay at emergency levels every week. It means the market may keep a scarcity premium in the background. Spikes become easier. Dips become shallower. Policy surprises become more expensive because there is less spare product to absorb them.
Could new capacity and demand destruction change that path? Of course. High prices are a ruthless teacher. They encourage efficiency, substitution, and, eventually, investment. They also encourage political intervention, which can either grease the adjustment or freeze it in place. The outcome depends on whether governments try to create more processing and smarter demand, or merely argue over who gets the last cargo.
I have seen energy debates get captured by ideology faster than by engineering. That is a shame, because diesel is an engineering story first. Molecules, distillation curves, sulfur specs, shipping windows, and tank heels decide more than talking points. If the public conversation stayed closer to those details, the policy menu would look less like a morality play and more like a logistics problem. Logistics problems are solvable. Morality plays tend to run overtime.
Where This Leaves The Atlantic Energy Bargain
The United States is asking Europe to open the vault. Europe is being told that refusal could mean fewer American barrels. Consumers on both shores want lower costs. Refiners want workable margins. Truckers want to stay in business. Those wishes do not line up neatly. Somebody will absorb the residual pain. The only open question is how that pain is distributed, and whether it arrives as a managed adjustment or a messy surprise.
So here is the part I keep repeating to myself. Watch the inventories, not the adjectives. Watch freight stress, not the volume of official concern. Watch whether winter arrives kindly. And watch whether any stock release is large enough to change the physical balance rather than just the press schedule. If those pieces move in a constructive direction, the export-ban threat may remain a lever instead of a law. If they do not, diesel will keep writing the economic weather report, one expensive mile at a time.
That is not a comfortable ending. It is an honest one. Fuel crises rarely announce themselves with a single explosion. They seep. They show up in bankruptcy notices, surcharge lines, and quieter factory schedules. The current warning from Washington to European capitals is a reminder that the seep has already started. The useful work now is less about picking a villain and more about getting barrels, trucks, and policy clocks to run in the same season.