
Have you ever watched a market get excited about a story that still needs ten or twenty years to become real? That is the feeling around the Venezuela oil revival right now. Headlines talk about historic deals, vast reserves, and a sudden opening after years of isolation. Then you sit with the actual condition of the fields, the pipelines, the power grid, and the politics, and the clock looks a lot slower.
Why The Rebound Story Is Bigger Than Near-Term Barrels
Energy security has moved back to the center of Western policy talk. The idea is simple enough: keep more supply closer to home, reduce reliance on distant chokepoints, and treat fuel as a national-security issue rather than a purely commercial one. Venezuela sits right on that map. It has enormous documented reserves, a long history of heavy crude that many Gulf Coast refiners already know how to run, and a production base that once ranked among the world’s largest.
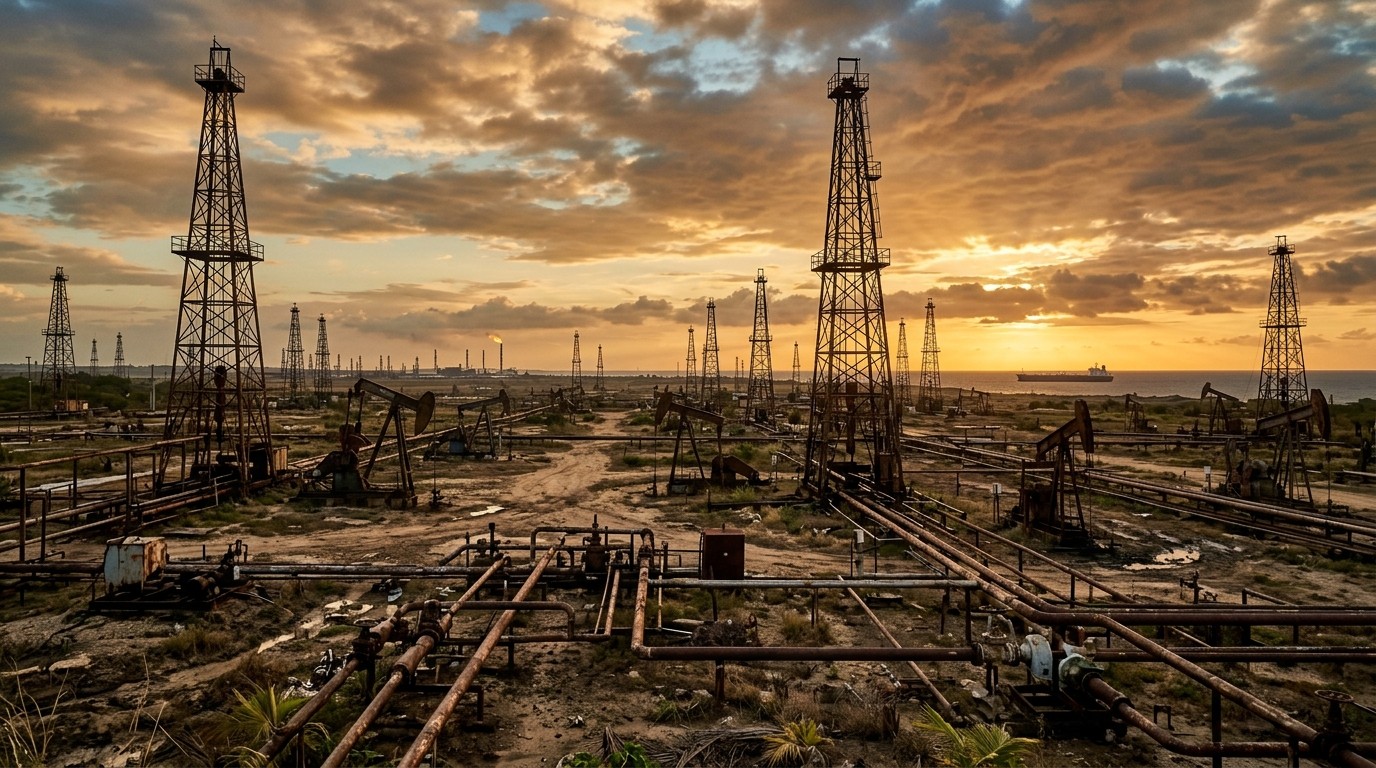
That last point is the trap. People hear “record output” and imagine a tap that can be turned. I have found that oil systems do not work that way after a long collapse. Wells water out. Reservoirs lose pressure. Skilled crews leave. Compressors fail. Upgraders sit idle until someone spends real money, not just optimism. A revival can still happen. It just does not happen on a news-cycle timetable.
Reaching the old record highs will likely take a decade or two and a great deal of good fortune.
That kind of warning matters because markets keep trying to price a prompt surge. Bond prices have already jumped on the political shift. Traders talk as if extra barrels could ease a tight diesel market in a matter of months. Perhaps the most interesting aspect is the gap between those hopes and the physical work still required on the ground.
What A Historic Deal Actually Changes
A new commercial and political framework can unlock access. It can assign development rights, set royalty terms, and give outside operators a legal path back into the Orinoco Belt and conventional fields. Control language around tens of billions of barrels of reserves sounds dramatic, and in a reserve-accounting sense it is. Reserves are not the same thing as flowing oil.
Think of reserves as a warehouse inventory that still needs trucks, roads, loaders, and drivers. Venezuela’s warehouse is huge. The logistics have been neglected for years. Any structure that splits equity between commercial partners and a state-backed security stake may stabilize the political side of the project. It does not automatically repair a delayed workover, a broken gas-injection system, or a missing spare part.
Royalty and tax projections in the hundreds of billions over a quarter century also need a sober reading. Those numbers assume production stays online, prices cooperate, and the fiscal rules do not swing after the next election cycle. In my experience, long-dated resource math looks gorgeous on a slide and fragile in a country that has already rewritten the rulebook more than once.
The Physical Reality Behind Record Output
Peak Venezuelan output belonged to another era of infrastructure and staffing. Extra-heavy crude from the Belt usually needs diluent, upgraders, or specialized refining capacity. Conventional fields need water handling, electricity, and consistent maintenance. When those pieces decay, decline accelerates. Bringing volumes back is not a matter of flipping a political switch.
Here is the unglamorous sequence that actually moves barrels:
- Secure title, security, and a fiscal regime that lenders can underwrite.
- Audit wells, surface facilities, and export routes field by field.
- Restore power, water, and gas handling before chasing headline growth.
- Stage workovers, then new drills, then major upgrader or pipeline spend.
- Prove reliable liftings before refiners treat the supply as dependable.
Skip a step and you get a short burst, not a durable revival. That is why a decade or two is not a pessimistic slogan. It is a project-management estimate dressed in plain language.
Why US Refiners Care More Than Casual Readers Think
A slice of the US refining system was built around heavy, sour grades. Those plants make diesel, jet, and other middle distillates that the world keeps needing. When heavy barrels disappear, refiners substitute other slates, run less efficiently, or chase more expensive alternatives. A credible Venezuelan return would be useful. A noisy but unreliable return would be a headache.
The current diesel tightness makes the temptation obvious. Extra heavy crude that can be turned into distillate looks like relief. I keep coming back to quality and consistency, though. A cargo that arrives late, off-spec, or only once is not a solution. Refiners plan crude slates weeks and months ahead. They need a rhythm, not a rumor.
So the near-term market effect may be more psychological than physical. Prices can move on the promise. Inventories move on the ships.
Investors Already Priced A Faster Miracle
Sovereign paper linked to Venezuela has rallied on the political thaw. That is rational in one sense. Defaulted or deeply distressed claims look better if sanctions ease, exports rise, and a recognized authority can negotiate. The risk is timing. A prompt revival thesis can strand anyone who bought the story as if barrels were already at the dock.
Equity-style bets on field developers face a different clock. Capital intensity is high. Payback stretches. Local content rules, security costs, and currency frictions can eat the model. I’ve seen resource reopenings look cheap on day one and expensive by year three, once the true deferred maintenance bill shows up.
| Market hope | Operational reality | Typical lag |
| Sanctions relief equals instant exports | Terminals, tankers, and quality control must restart | Months to a few years |
| Record reserves equal record flow | Wells and upgraders need heavy spend | Many years |
| Political deal locks in policy | Elections can reopen the bargain | Every cycle |
| Bond rally confirms recovery | Cash flow still depends on liftings | Ongoing |
None of this means the opportunity is fake. It means the opportunity is long-duration. That is a different animal from a short squeeze in a commodity headline.
The Orinoco Question And Who Comes Back
Talk of major operators negotiating a return to the Belt is not surprising. The resource is world-class. The technology is known. What changed is permission and politics. Even then, extra-heavy projects are patient-money projects. Steam, dilution, upgrading, and environmental handling all cost more than a simple onshore well in a friendly basin.
Companies that left years ago will want contract stability, arbitration rights, and a path to repatriate cash. They will also want partners who can handle security and community relations. A structure that includes a state or defense-linked stake may reassure some counterparties and worry others. Capital has a memory. It remembers expropriation risk even when the current mood is warmer.
If negotiations succeed, the first phase is usually not a flood of oil. It is studies, pilots, and selective restarts. The photogenic moment comes later, when a cluster of wells and an upgrader actually run together for more than a quarter.
Energy Security Is Not The Same As Energy Speed
Policy language about a Western energy doctrine sounds forceful. Bring supply closer. Treat the hemisphere as a strategic basin. Reduce exposure to distant shocks. Fair enough. Strategy still has to survive engineering. A barrel that takes fifteen years to restore does not solve a shortage this winter.
That mismatch is where public debate gets sloppy. People collapse “we signed a deal” into “the diesel problem is fixed.” Those are different sentences. One is diplomatic. The other is logistical. I’ve found that the cleanest way to stay honest is to separate three clocks: the political clock, the project clock, and the market clock. They rarely tick together.
- The political clock can move in weeks.
- The project clock moves in years.
- The market clock prices both, often too early.
Keep those three in view and the Venezuela story becomes less mystical. It is a long rebuild with strategic value, not a surprise inventory dump.
A Side Door: Metals And The Broader Resource Thaw
Oil is not the only file on the desk. Reports of a first aluminum shipment in years point to a wider attempt to reopen commodity channels. That matters because it shows counterparties testing logistics, payments, and compliance after a long freeze. A metals cargo is smaller than a crude program, yet it is a useful dry run for documentation, shipping, and offtake trust.
If those side channels work, oil traders will notice. If they stumble, oil will face the same friction. Resource recoveries are ecosystems. Power plants, ports, customs desks, and banks all have to function at the same time. One working mine or smelter does not prove the petroleum system is healthy. It does prove that some doors are no longer sealed shut.
The Election Cloud Over A Twenty-Year Build
Here is the uncomfortable part. A rebuild that needs a decade or two also needs policy continuity. Military, diplomatic, and financial backing can look solid in one administration and contested in the next. Midterm politics in the United States are not a footnote. They are a risk factor in the discount rate.
Investors now have to ask a blunt question. Will the commitment last as long as the wells need? If the answer is only “maybe,” capital will arrive in shorter bursts. Short bursts do not restore a super-giant heavy-oil province. They patch a few fields and leave the rest for later.
The real bet is not whether Venezuela has oil. The bet is whether the political sponsorship can outlast the reconstruction calendar.
That is not cynicism. It is how long-cycle energy projects live or die. Pipelines do not care about slogans. They care about budgets that survive more than one news cycle.
How To Think About Volume Scenarios Without Fooling Yourself
It helps to sketch ranges instead of a single heroic number. A first phase might stabilize existing output and recover some shut-in wells. A second phase might add meaningful incremental barrels if upgraders and export systems hold. A third phase, the one that flirts with old peaks, needs sustained drilling, social license, and a fiscal deal that still looks fair when prices sag.
I like to keep the language ordinary. Low case: modest recovery, frequent interruptions. Base case: a multi-year grind higher that still falls short of history. High case: a genuine return toward former strength after a long stretch of luck, capital, and quiet politics. Notice what is missing from that list. Instant abundance.
Simple recovery frame:
  Access and security first
  Then reliability of liftings
  Then growth drilling
  Only later a shot at old peaks
If someone sells you the last step as the first step, walk away. Or at least haircut the model.
What “Good Fortune” Really Means In This Basin
Analysts who talk about luck are not being poetic. They are listing variables nobody can fully control. Reservoir performance after years of damage. Diluent availability. Storm seasons. Community unrest. Spare-part sanctions that linger in the fine print. A price crash that freezes the second wave of investment. Any one of those can turn a neat timeline into a slog.
Good fortune, in this setting, looks boring. Quiet fields. Predictable rules. Power that stays on. Crews that stay paid. Courts that honor contracts. That is the unsexy formula. Flashy ceremonies do not substitute for it.
And yes, there is a human layer. Engineers who left may not rush home. Training a new generation takes time. Institutional memory is an asset, and Venezuela spent years leaking it. You cannot import that overnight, even with a well-funded joint venture.
Market Implications If The Slow Path Is The True Path
If the slow path is right, global balances do not get a sudden Venezuelan shock to the downside. Tightness in distillates may ease for other reasons, or not at all. Heavy-sour differentials may stay firmer than a “flood of Belt crude” narrative implies. That would support complex refiners who can still source alternative heavies, and it would disappoint anyone positioned for an immediate surplus.
It also changes how to read energy-security speeches. Strategic intent can be real while the volumetric contribution stays small for a long time. Policymakers can still value the option. Traders should value the option differently from the flow.
There is a portfolio angle too. Long-dated claims on Venezuelan cash flows become duration instruments. They behave less like a quick special situation and more like a political infrastructure bond with operational covenants that nobody can fully write down.
A Practical Checklist For Readers Following The Story
You do not need a trading desk to follow this intelligently. Watch a few unromantic indicators. Are workovers actually rising? Are upgraders running above token rates? Are liftings regular rather than ceremonial? Do fiscal terms survive the first dispute? Is security quiet enough for night crews? Those questions beat any slogan about the biggest deal in history.
- Track reliable export loadings, not announcement volume.
- Separate reserve headlines from well-level activity.
- Treat election calendars as project risk, not background noise.
- Assume heavy crude needs extra kit before it becomes diesel.
- Give more weight to multi-year capex than to day-one ceremonies.
Do that and the story stays interesting without becoming a fairy tale.
The Temptation To Oversell Speed
Why does the fast version keep winning the first day’s attention? Because it is easier to tell. A deal is a scene. A twenty-year work program is a binder. Audiences reward scenes. Markets sometimes do the same until the binder asserts itself.
I do not blame people for wanting a clean ending. After years of decline, a revival narrative feels like justice, strategy, and profit in one package. Wanting it does not make the iron rust disappear. The honest tone is hopeful and slow. Hopeful because the rock is still there. Slow because almost everything above the rock has to be rebuilt.
If that sounds less exciting than the opening press conference, good. Excitement is a poor substitute for throughput.
Where This Leaves The Next Stretch Of Headlines
Expect more negotiation leaks, more cargo tests, more talk of partners returning, and more political claims of control over a giant reserve base. Some of that will be meaningful. Some will be branding. The filter is simple. Did a facility that was dead last year run this year, month after month? If yes, the revival is getting real. If not, the story is still in the speech phase.
Stay tuned, sure. Just stay calibrated. A Western energy-security push can open the door. Walking through that door with steel, people, and patience is the part that takes a decade or two. The old record is not forbidden. It is distant. Distance is the detail too many summaries leave out.
And that, more than any single contract clause, is the point worth carrying into the next market open. The barrels may come. They will not sprint.