

What Qualifies As A Citi Travel Purchase For Rewards

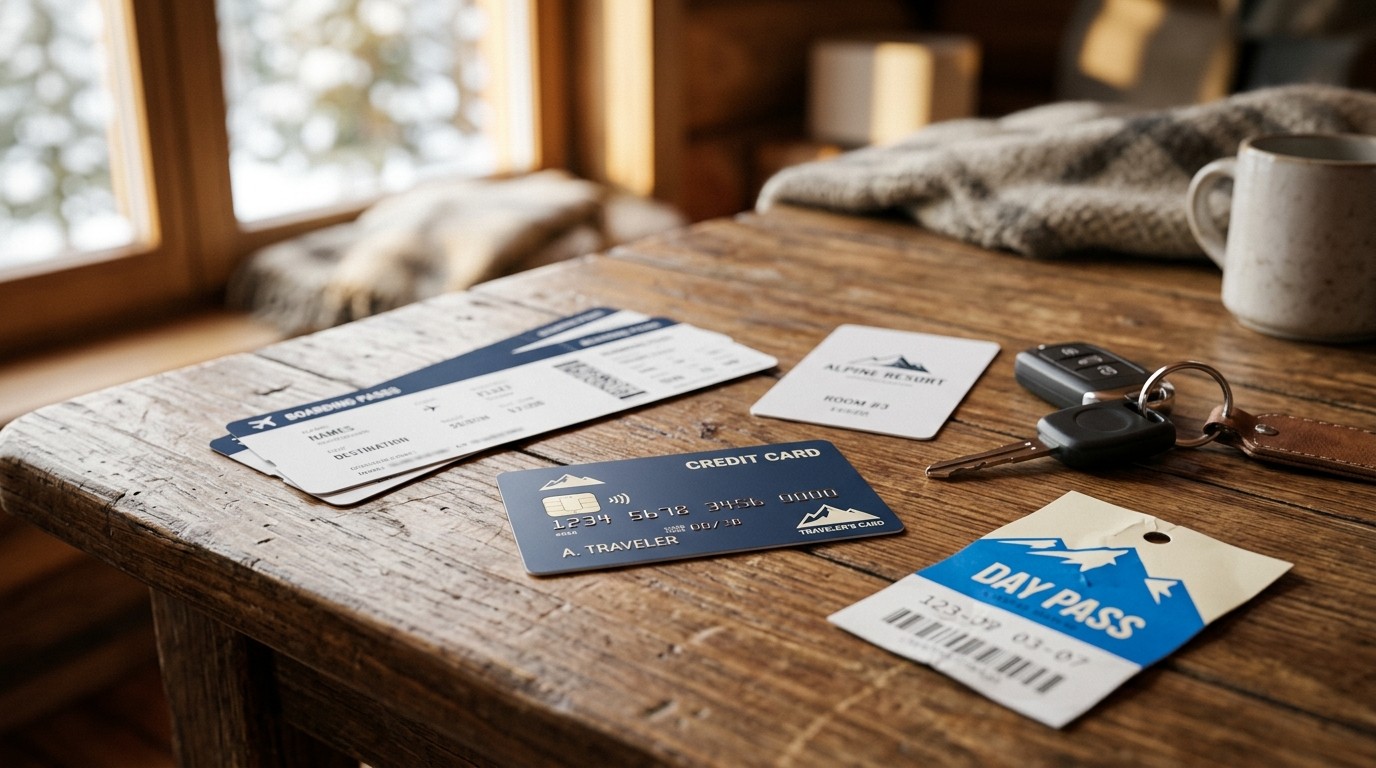
Ski lift tickets look like travel. Citi may not agree. The code behind the swipe decides whether you earn 3% or drop to 1%, and the surprise often shows up after checkout.
Financial market analysis from 28/09/2026. Market conditions may have changed since publication.
I still remember the first time a winter trip looked like a slam dunk for bonus cash back and then… it wasn’t. The lodging felt like travel. The lift tickets felt like travel. Even the shuttle from the parking lot felt like travel. The statement told a quieter story. One charge sat in the bonus bucket. Another slid into the leftover 1% pile. That gap is not a glitch. It is how card networks sort the world.
How Citi Decides What Counts As Travel
When people ask what qualifies as a Citi travel purchase, they usually want a clean list. Airlines. Hotels. Rental cars. Maybe a cruise. That list exists, and it is useful. It is also incomplete. The real filter is not your itinerary. It is the four-digit label a merchant carries when the charge hits the network.
I’ve found that the frustration starts here. You book a mountain weekend thinking in human categories. Citi’s system thinks in processor categories. A ski resort can look like a hotel one week and something closer to a timeshare or recreation vendor the next, depending on how the front desk rings you up. Same mountain. Different code. Different rate.
Why Merchant Category Codes Quietly Run The Show
Every swipe, tap, or online checkout gets stamped with a merchant category code. That stamp is assigned through the business’s payment setup, not through your vacation photos. A Citi spokesperson-level explanation of this idea is simple: the code decides the rewards. Not the snow. Not the suitcase. Not the fact that you left town.
The category on the receipt in your head and the category on the statement are not always friends.
You can try asking a merchant how it is classified. Sometimes a manager knows. Often nobody at the desk has ever heard the question. For big brands, cardholders compare notes in forums. For smaller properties, the only reliable test is a small charge before you drop four figures on a week of lodging.
That sounds tedious. It is. It is also cheaper than discovering the coding after the trip, when the only leftover move is a shrug.
What Usually Lands In The Eligible Travel Bucket
On cards such as the Costco-branded Citi Visa, eligible travel is not a poetic phrase. It is a short roster. Travel agencies. Cruise lines. The issuer’s own travel booking path. Hotels. Car rentals. Airfare. Those are the lanes that tend to pay the higher rate, often 3% cash back when the rest of the card is paying far less.
Notice what sits on that list. It is the classic trip machinery: getting there, sleeping there, moving around once you arrive, or handing the whole package to an agency. Costco Travel belongs in that group because it is processed as travel, not because a warehouse club logo magically upgrades every ski jacket in the cart.
- Airfare booked as an airline or agency sale
- Hotel stays that code as lodging, not as a club or timeshare product
- Traditional car rental counters and major rental brands
- Cruise line charges that run through the cruise merchant type
- Bookings made through a travel agency or the card’s travel portal
If your charge looks like one of those, you are in decent shape. If it only feels adjacent, keep reading.
The Quiet Exclusions That Catch People Off Guard
The same program that celebrates hotels can sidestep other overnight stays. Timeshares. Campgrounds. Bed and breakfasts. Train and commuter travel. Those often earn the base rate, not the travel bonus. That is a cold splash if you planned a scenic rail weekend or a cabin that markets itself like a boutique hotel.
I have a soft spot for small inns. They can be wonderful. They can also code like a general lodging oddity rather than a chain hotel. A B&B owner is running a hospitality business. The network may still file it next to categories that Citi does not boost.
Commuter rail is the other sneaky one. You are moving from city to city. That is travel in any ordinary sentence. The rewards engine may treat it like local transit. Bonus gone.
Ski Resorts, Lift Tickets, And The Split Receipt Problem
This is the question that started the whole mess for a lot of cardholders. Do resort charges and lift tickets count? Sometimes the room does. Sometimes the mountain extras do not. A resort can wear more than one mask.
Pay the hotel folio as lodging and you may get the travel rate. Buy lift tickets at a window that rings through a recreation or amusement-style code and you may not. Add a season pass through a third-party seller and the code can change again. Package the room, tickets, and lessons through an agency and the whole bundle is more likely to travel-code because the seller is a travel agency, not a mountain retail shop.
How you book matters as much as where you sleep. A direct resort website can split charges across departments. An agency invoice can collapse them. I’ve seen couples argue in the parking garage about which card to use for the tickets. The boring answer is: use the card that still pays well if the code misses.
| Charge type | Likely coding path | Bonus outlook |
| Hotel room at a major chain | Lodging / hotel | Often bonus travel |
| Lift tickets at the window | Recreation or similar | Often base rate |
| Resort fee on the folio | Follows the room code | Mixed, often with lodging |
| Package via a travel agency | Travel agency | Often bonus travel |
| Timeshare week or campground | Excluded lodging types | Usually base rate |
| Train tickets | Transit / rail | Usually base rate |
Treat that table as a weather forecast, not a statute. Processors update. Properties change banks. A resort that coded cleanly last season can surprise you this year.
Restaurants On The Road Are Not Automatic Travel
Some Citi products pay a restaurant bonus that sits next to the travel bonus. That helps a dinner after a flight. It does not turn every meal into travel. A resort restaurant might code as dining. It might also roll into the room folio and inherit the hotel code. Two dinners, two outcomes.
If you care about every point, ask to pay food separately and watch a test charge. If you do not care that much, pick the card that pays a solid rate on both dining and lodging and stop micromanaging the steak.
The Costco Angle Without The Warehouse Myth
The Costco Anywhere Visa by Citi is popular because the headline rates look generous: strong gas and EV charging tiers, then a combined restaurant and eligible travel rate that beats a plain 1% card. There is no annual fee if you already pay for membership. Foreign transaction fees are absent, which matters on a real trip, not a staycation.
The catch is structure. Rewards on that product are more boxed in than a typical cash-back card. You wait for an annual certificate. You redeem at warehouse locations in a defined way. You live with category walls. That is fine if you already shop there and already travel in the “classic” lanes. It is less fine if your trips look like rail, campgrounds, lift windows, and quirky inns.
Perhaps the most interesting aspect is how people overfit the card to every vacation. They assume a warehouse travel brand plus a Visa logo means the mountain is covered. The membership gets you the card. The merchant code still does the sorting.
- Confirm the purchase type against the published eligible travel list.
- Watch how the merchant descriptor appears on a small test charge.
- Prefer agency or portal booking when the stay is expensive and the coding is fuzzy.
- Keep a flat-rate card in the same wallet for anything that smells like an exclusion.
- Do not wait until April to notice a winter trip coded poorly.
When A Flat-Rate Card Beats Category Hunting
Category bonuses are candy until they become homework. A 3% travel rate is attractive. A reliable 2% on everything is adult. If you cannot predict the code, the “safe” card often wins on peace of mind and sometimes wins on math too.
Think about a $2,000 mountain week. If $1,200 codes as hotel and $800 codes as tickets, lessons, and a locker, a 3% / 1% split is not the fantasy rate printed on the brochure. A flat 2% card would have paid a steady figure on the whole pile. You give up a little on the room. You stop leaking value on the extras.
Citi’s Double Cash style product is the obvious in-house comparison: earn when you buy, earn again when you pay, land near 2% if you stay current. No annual fee. Rewards sit in a points currency you can cash or, in some setups, move toward travel partners. It will not thrill a points maximizer. It will rescue a sloppy coding week.
Other issuers run the same idea with a simple unlimited cash rate and a $0 annual fee. Pairing that card with a transfer-capable sibling can later turn dull cash into flights, but you do not need that trick on day one. You need a card that does not punish a lift ticket.
If you have to research a ski window like it is a legal case, the bonus category is already costing you time.
How To Test A Merchant Without Wrecking The Budget
Call and ask. Fine. Then still test. Buy the cheapest prepaid item or a refundable hold when the property allows it. Wait for the pending description. Wait again for the posted description. Pending text lies more often than people think.
Look at the merchant name. A string that includes “HOTEL” or a known chain is encouraging. A string that includes “RESORT RETAIL,” “AMUSEMENT,” or a ticket vendor is a warning. Then check the rewards posting, not just the description. Some apps show estimated category before the statement closes. Trust the estimate only after you have seen it match reality a few times.
In my experience, the people who get burned are not careless. They are optimistic. They booked the trip as travel, so they assumed the card would too. Optimism is a lovely travel companion. It is a weak auditor.
Booking Paths That Improve Your Odds
If the trip is a package anyway, let a travel agency or the card’s travel desk be the merchant of record. Agency codes are on the friendly list. You may pay a bit more in package pricing. You may also lock the bonus on tickets that would have failed at the window.
Direct airline and hotel sites still work when those merchants are what they claim to be. Third-party bed sites can scramble the code, especially when a private host sits behind a platform. Read the charge name before you celebrate.
Car rentals are usually cleaner than mountains. The big counters know who they are. Independent local lots can be messier. Same advice: small hold, watch the post, then put the real deposit on the card that behaved.
Foreign Spend, Annual Fees, And The Rest Of The Fine Print
A travel category is only half the product. No foreign transaction fee matters the moment you leave the country. An annual fee changes the break-even math. A rewards certificate you can use only once a year changes when the value becomes real money in your pocket.
The Costco-tied card shines if you already pay for membership and already buy gas in the boosted tier. It dims if you wanted flexible cash every month and trips that look nothing like a brochure. A no-fee flat card shines if you hate tracking. It dims if you put huge, clean hotel and airfare spend on a card that would have paid 3% instead of 2%.
There is no universal winner. There is a winner for the way you actually book, not the way a commercial films a suitcase.
A Practical Wallet Setup For Mixed Trips
Keep one category card for obvious travel: flights, chain hotels, rental cars, agency invoices. Keep one flat-rate card for everything that might argue. Use the category card first only when you already know the merchant. Use the flat card when you do not.
Couples who travel together should agree on this before the front desk line. Nothing sours a check-in like two people whispering about codes while a clerk waits for a chip to process. Decide the default. Make exceptions only when the merchant is obvious.
Simple trip split:
  Known airline / hotel / rental / agency → bonus travel card
  Tickets, lessons, shuttles, odd lodging → flat-rate card
  Dining → restaurant-bonus card if you have one, else flat-rate
  Anything confusing → flat-rate, no debate
That split will not maximize every dollar. It will prevent the statement surprise that makes people swear off bonus categories entirely.
What “Eligible Travel” Does Not Mean
It does not mean “I traveled.” It does not mean “this expense happened far from home.” It does not mean “this company sells things to tourists.” It means the merchant’s file says travel in the way the issuer defined travel.
Souvenir shops in airports still look like retail. Parking lots still look like parking. Resort spas can look like personal care. Luggage stores can look like department stores. You left home. The code stayed local.
Once you accept that, the whole topic gets less emotional. You stop feeling cheated by a mountain. You start treating codes like weather. You pack for both.
A Note On Welcome Offers And Transfer Value
Some Citi products dangle a cash or points bonus for early spend. That bonus can outweigh a single miscoded ski week. Do the arithmetic on the offer first. Then decide whether category purity even matters in year one.
Transferable thank-you style points change the story again. If your cash-back-looking earnings can move to an airline or hotel partner, a 2% floor becomes more interesting. If your earnings are trapped in an annual warehouse certificate, flexibility drops and predictability matters more. Match the redemption cage to the way you travel.
Common Myths That Waste Time
Myth one: if the website has photos of planes, it is travel. No. Myth two: paying at a hotel front desk always codes as a hotel. Not if the desk is ringing a golf shop, a ticket office, or a timeshare contract. Myth three: calling the issuer after the fact will recode a merchant out of kindness. Sometimes an agent can file a review. Often the code is the code.
Myth four: a bigger charge is more likely to count. Size is irrelevant. A $9 coffee in an airport can be dining. A $900 lesson package can be recreation. The network does not grade by dollar drama.
Myth five: last year’s coding is a contract. Merchants switch processors. You should assume nothing permanent except the need to glance at the statement.
Putting A Real Weekend Through The Filter
Imagine a Friday flight, a Saturday night in a slope-side lodge, Sunday tickets, a rental car, and a grocery run for cabin snacks. The flight is the easy win. The car is usually an easy win. The lodge is a maybe that leans yes if it is true lodging. The tickets are the leak. The groceries are just groceries.
If you force every line onto the travel card, you might still do well on the big two and stumble on tickets. If you split cards without thinking, you might put the flight on the flat card and waste a clean bonus. Two minutes of sorting before you tap beats two weeks of forum searching after you return.
Would I personally put lift tickets on a bonus travel card and hope? Only if I had already tested that window. Otherwise the flat card goes out first. I like bonus categories. I like sleep more.
How Couples And Friends Should Handle The Card Dance
Shared trips create shared statements and shared irritation. One person tracks categories like a sport. The other person just wants the room keys. Agree on a default card for fuzzy spend. Let the hobbyist use the bonus card only on obvious items. Split reimbursement later if you must. Do not turn the checkout counter into a seminar.
If one partner already holds the warehouse membership card and the other holds a flat 2% card, you already have the kit. Stop applying for a third product to solve a coding problem that a wallet split already solves.
When To Ignore The Bonus Entirely
Ignore it when the difference is smaller than the hassle. Ignore it when a refund policy is cleaner on another card. Ignore it when a travel insurance benefit, purchase protection, or rental coverage sits on a different piece of plastic. Rewards are one layer. Trip protection can be worth more than a two-point swing on a ticket.
Ignore it when you are exhausted. A miscoded charge at 1% instead of 3% on $200 is four dollars. Four dollars is not a personality. Keep your priorities in the right coat pocket.
A Straight Answer To The Original Ski Question
Do eligible travel rewards on a Citi Costco Visa include resort charges and lift tickets? Resort lodging can, when it codes as a hotel and not as a timeshare-style stay. Lift tickets often do not, unless they ride along inside an agency or travel-package charge that itself codes as travel. Resort fees that land on the room folio tend to follow the room. Tickets sold like recreation tend to follow recreation.
That is not a vibe-based answer. It is a coding-based answer. If you need certainty for a pricey week, test, or book the mountain as a package through a travel seller that Citi already treats as travel.
Book the trip you want. Then pick the card that survives the code you cannot see yet.
Final Take Before You Pack The Plastic
Citi travel bonuses are real. They are also narrower than the word travel. Use them where the merchant is obviously in the club. Use a flat-rate card where the mountain, the inn, or the ticket window might file itself somewhere dull. Watch one test charge. Keep the annual redemption calendar in mind if your rewards arrive as a yearly certificate instead of on-demand cash.
The goal is not to win a coding contest. The goal is to come home with the trip you planned and a statement that does not feel like a prank. Once you see the four-digit stamp as the actual decision maker, the whole rewards puzzle gets quieter. And quieter, on a travel week, is worth more than an extra fraction on a locker rental.
The language of cryptocurrencies and blockchain is the language of the future.


Related Articles
Why Value Matters In Today’s Consumer Choices
Why are consumers so focused on value in 2025? From inflation to rising rates, discover what’s driving smarter spending and how businesses are adapting...
BRICS Summit 2025: Will De-Dollarization Reshape Markets?
As the BRICS Summit 2025 looms, talks of de-dollarization heat up. Could this reshape global markets? Click to uncover what’s at stake...
Can Private Funds Spark a Nuclear Energy Boom?
Could private funds unlock a new era for nuclear energy? As tech giants eye clean power, the stakes are high. But can costs and risks be tamed? Click to find out.