
Have you ever watched a market threshold approach and felt that quiet tension in the air, the sense that something important is about to shift? That is exactly where fixed-income markets stand right now. The 10-year Treasury yield has climbed to levels not seen in more than two decades, yet a clear majority of professional investors say they still need higher yields before they seriously consider moving money out of stocks and into bonds. The number that keeps coming up is 6 percent. I’ve been following these surveys for years, and this particular reading feels different. It is not just another data point. It is a line in the sand that could reshape portfolios across the board.
The Yield Level That Could Force a Real Portfolio Rotation
According to the most recent global fund manager survey, 37 percent of respondents said they would start shifting from equities toward bonds once the 10-year yield reaches 6 percent. Another 14 percent pointed to 6.5 percent as their personal trigger. Only 19 percent felt yields were already high enough to justify a meaningful move. That leaves a large group still sitting on the sidelines, waiting for one more step higher.
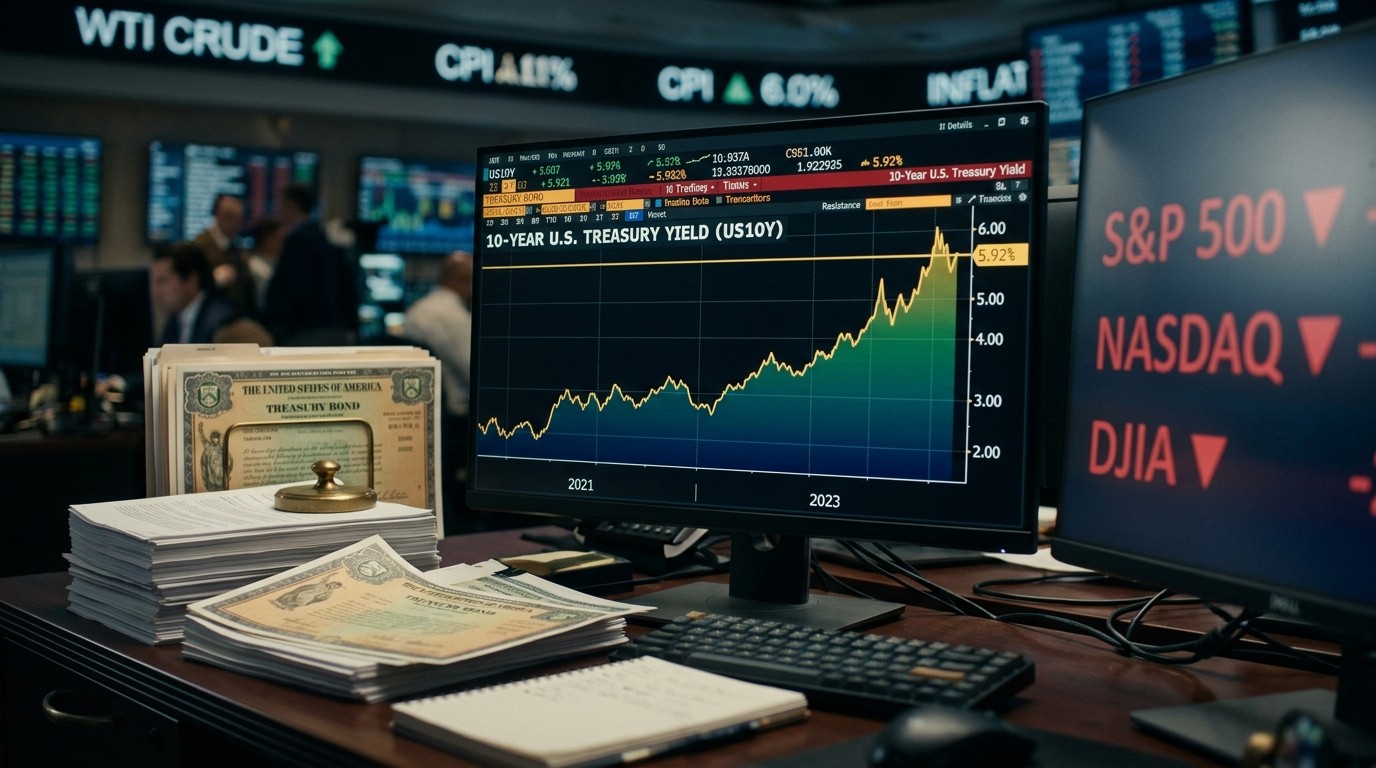
The 10-year yield recently touched 5.365 percent, its highest mark in 24 years, before settling back near 5.21 percent. That is close enough to make the conversation serious. In my view, the gap between current levels and the 6 percent threshold is small enough that a few weeks of sticky inflation data or geopolitical tension could close it. Markets rarely move in straight lines, yet the direction of travel has been clear for months.
Why Higher Yields Suddenly Look More Attractive
Bonds have spent years looking relatively unappealing compared with the strong returns delivered by equities. When the 10-year yield sat near 1 or 2 percent, the income simply could not compete with potential capital gains in the stock market. That calculation changes once yields climb into the mid-to-high 5 percent range and threaten 6 percent. At those levels, the risk-free rate starts to offer real competition.
I have spoken with enough portfolio managers to know that many of them keep a mental checklist. When the yield on longer-term government paper approaches the expected long-term return on equities, the conversation inside investment committees shifts. Suddenly the question becomes less about growth and more about certainty of cash flow. That psychological pivot is powerful.
Higher Treasury yields can make bonds more attractive relative to stocks while also pushing up borrowing costs across the economy.
The second half of that statement matters just as much. Rising yields do not only change relative valuations. They also raise the cost of mortgages, corporate debt, and consumer credit. Housing activity slows. Companies grow more cautious about expansion plans. Households rethink big purchases. The entire economic machine feels the pressure.
Geopolitical Risks and the Inflation Shadow
The recent surge in yields has not happened in isolation. Investors have grown increasingly concerned that higher oil prices linked to conflict in the Middle East could feed through into broader inflation. When energy costs rise, the risk of an “inflationary mindset” taking hold becomes real. Central bankers watch that possibility closely.
One regional Federal Reserve president recently noted that higher rates might be necessary to prevent such a mindset from embedding itself. That kind of language tends to keep bond yields elevated. Markets hear the message loud and clear: policy makers remain ready to lean against any reacceleration in price pressures.
This week’s inflation reports will therefore carry extra weight. Consumer price data arrives first, followed quickly by producer prices. Any upside surprise could push the 10-year yield closer to that 6 percent mark that so many managers are watching. A softer print might offer temporary relief. Either way, the path of least resistance still points higher until clearer evidence of cooling appears.
What a Move Above 6 Percent Would Actually Mean
Let us be practical for a moment. A 6 percent 10-year yield would represent a genuine regime change for a generation of investors who came of age during the ultra-low-rate era. Suddenly the opportunity cost of holding cash or short-duration instruments becomes harder to ignore. Pension funds, insurance companies, and retail investors alike would find the income case for intermediate and long bonds far more compelling.
I have found that once a critical mass of large players begins reallocating, the flows can reinforce themselves. Bonds rise in price as demand increases, which lowers yields somewhat, yet the very act of rotation can pressure equity valuations at the same time. That dual movement is what many strategists quietly discuss behind closed doors.
- Higher risk-free rates compress equity valuation multiples
- Income-focused investors gain a viable alternative to dividend stocks
- Leverage becomes more expensive for both companies and households
- Growth-sensitive sectors often underperform in such environments
None of this guarantees an immediate bear market in stocks. Markets can and do climb the wall of worry. Still, the relative attractiveness of bonds would improve enough that many balanced portfolios would look different six months later.
The Psychology of the 19 Percent Who Already See Value
It is worth pausing on the minority who already consider current yields high enough. These investors are not necessarily predicting an imminent recession. Many simply believe that locking in yields above 5 percent offers an attractive risk-adjusted return over a multi-year horizon. In their view, waiting for 6 percent risks missing the best entry points if yields peak earlier than expected.
Perhaps the most interesting aspect is how differently institutions and individuals sometimes react. Large asset managers often move more slowly because of committee processes and benchmark constraints. Individual investors can act faster, yet they frequently wait for clearer signals from the professionals. That lag creates windows of opportunity for those willing to position ahead of the crowd.
Borrowing Costs and the Broader Economic Feedback Loop
Every percentage point increase in the 10-year yield eventually feeds into mortgage rates, auto loans, and corporate bond spreads. The lag is not always immediate, yet the direction is consistent. Higher financing costs tend to slow housing turnover, reduce capital expenditure, and encourage companies to focus on efficiency rather than expansion.
I remember earlier cycles when yields rose quickly and the economic impact only became obvious several quarters later. The same pattern could play out again. Markets price the change in financing conditions long before the hard data fully reflect it. That is why equity investors watch the bond market so carefully these days.
How Different Investor Types Might Respond
Not every portfolio will react the same way if yields climb toward 6 percent. Consider the range of approaches:
- Conservative income investors may accelerate purchases of intermediate Treasuries and high-quality corporate bonds.
- Growth-oriented equity managers could reduce exposure to rate-sensitive sectors such as utilities and real estate.
- Balanced fund managers might gradually increase the fixed-income allocation inside target-date or multi-asset strategies.
- Speculative traders may use the move as an opportunity to express views on the duration of the tightening cycle.
The common thread is a reassessment of opportunity cost. When the safe asset starts yielding more, every other asset class has to justify its existence more carefully.
Looking Ahead to the Next Critical Data Points
This week’s inflation numbers will not settle the debate by themselves. Markets will continue to parse every comment from policy makers and every movement in oil prices. Yet the survey results already tell us something useful: a substantial portion of professional capital is waiting for a higher yield before making a significant rotation.
In my experience, these thresholds often act as self-fulfilling magnets. Once enough participants identify the same level, price action tends to gravitate toward it, at least temporarily. Whether 6 percent ultimately proves to be the peak or merely a way station remains unknown. What feels clearer is that the relative value conversation between stocks and bonds has shifted meaningfully.
Investors who ignore the rising attractiveness of fixed income may find themselves adjusting later and at less favorable levels. Those who begin thinking through the implications now can prepare their portfolios with greater deliberation. The gap between 5.2 percent and 6 percent does not look enormous on a chart, yet the behavioral change it could trigger is substantial.
Practical Considerations for Portfolio Construction
If yields do continue higher, several practical steps deserve attention. First, the duration profile of existing bond holdings becomes more important. Longer-maturity paper will experience greater price volatility, yet it also offers more income if the move proves temporary. Second, the quality of corporate credit exposure warrants review. Rising rates often coincide with tighter financial conditions that can pressure weaker balance sheets.
Third, the equity side of the portfolio may benefit from a fresh look at valuation sensitivity. Companies that rely heavily on low discount rates for their growth stories often face the largest multiple compression when yields rise. Conversely, businesses with strong free cash flow and the ability to return capital to shareholders can look relatively more resilient.
I have found it useful to run simple scenario analyses. What does the portfolio look like if the 10-year settles near 5.5 percent for an extended period? What if it briefly overshoots to 6.25 percent before retreating? Those exercises rarely produce perfect forecasts, yet they force clearer thinking about risk and opportunity.
The Longer-Term Backdrop That Makes This Moment Different
This is not simply another short-term yield spike. After more than a decade of suppressed rates, the return of higher nominal yields changes the entire investment landscape. Savers finally have options that deliver meaningful income without taking equity risk. Pension plans can fund liabilities more easily. Insurance companies regain a traditional tool for matching assets and liabilities.
At the same time, governments face higher interest expense on their debt. Corporations that refinanced aggressively during the low-rate years will eventually confront higher coupons. Households with floating-rate debt feel the pinch more quickly. These forces operate slowly, yet they accumulate.
The survey finding that only a minority of managers already see current yields as high enough suggests that the market has further to travel before a broad consensus forms. That gap between current reality and the threshold many participants are watching creates both risk and opportunity.
Balancing Caution with Opportunity
No one should treat 6 percent as a magical number that guarantees success. Markets have a habit of surprising even the most careful observers. Still, the collective judgment of global fund managers carries weight. When a clear majority identifies a specific level as the point at which the risk-reward between stocks and bonds tips, that information deserves respect.
Perhaps the most useful takeaway is simply heightened awareness. The old regime of near-zero rates is gone. The new regime is still being defined. Yields near multi-decade highs force every investor to revisit long-held assumptions about asset allocation, expected returns, and the true cost of capital.
Whether the 10-year ultimately reaches 6 percent this year or next remains uncertain. What feels more certain is that the conversation has already changed. Bonds are no longer an afterthought. They have reclaimed a seat at the table, and the debate over when they become too attractive to ignore is now fully underway.
For anyone managing money through this transition, the survey results offer a useful mirror. Most professional investors still need higher yields before they act decisively. That collective hesitation itself becomes part of the market dynamic. Understanding it may prove as valuable as any single data release that arrives in the coming days.
The path from here will depend on inflation persistence, energy prices, and the willingness of policy makers to keep rates elevated. Yet the destination many managers are watching remains clear. When the 10-year yield approaches 6 percent, a meaningful portion of capital is prepared to rotate. That simple fact is already shaping how portfolios are being positioned today.
In the end, markets are about relative value. As long as equities offer the prospect of growth and bonds offer rising income, the tug-of-war continues. The latest survey simply tells us where a large group of sophisticated investors currently draws the line. Crossing that line could mark one of the more important allocation shifts of the decade.