
Have you ever watched two similar companies report earnings on the same night and then wake up to completely opposite stock reactions? That is exactly what played out this week with Alphabet and Microsoft. One delivered numbers that sent shares tumbling more than 12 percent in a single session, while the other held its ground with only a mild dip amid broader market softness. I keep coming back to the same question: what makes investors treat these two technology heavyweights so differently when both are pouring money into artificial intelligence?
The Stark Difference in Market Response After Earnings
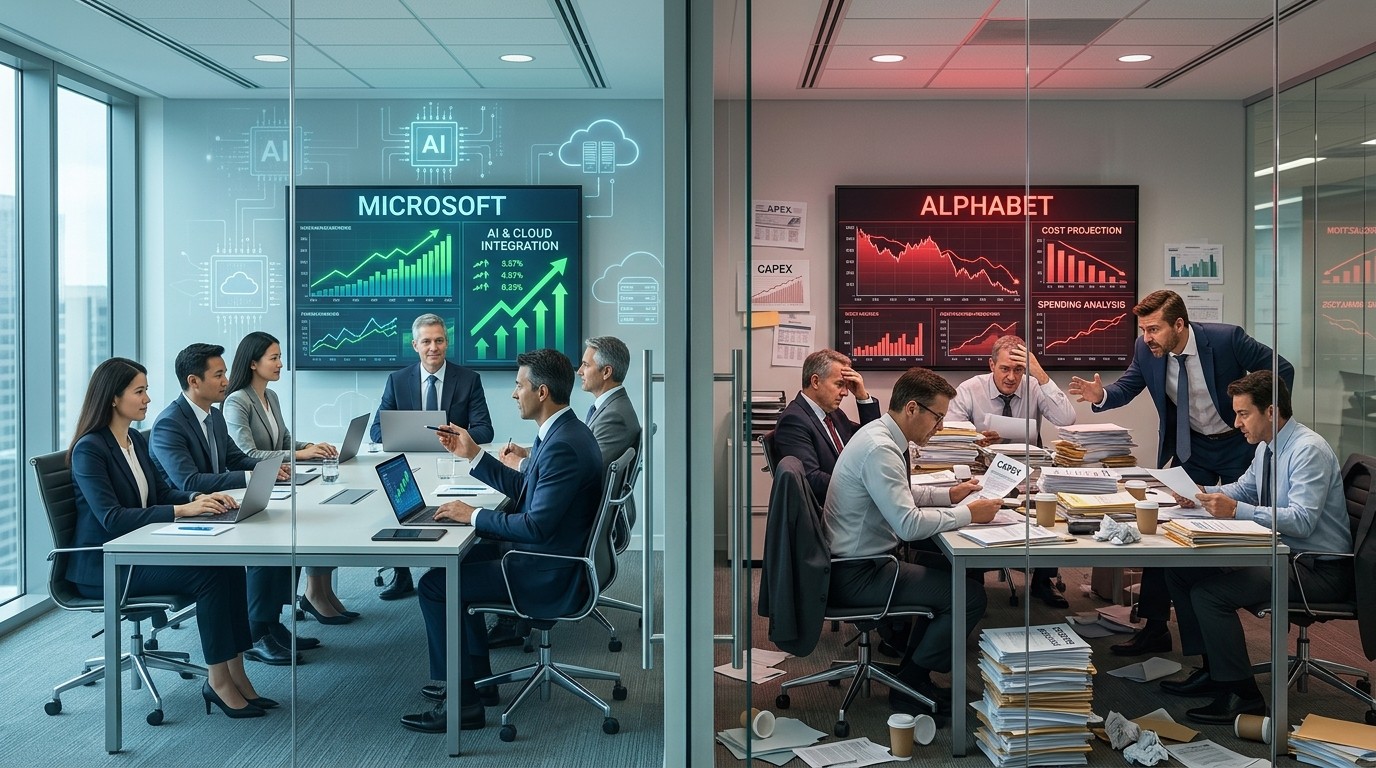
The contrast feels almost theatrical. Alphabet, the parent company behind Google, saw its stock head toward the largest one-day decline in its history. Microsoft, meanwhile, opened higher before settling into a modest decline that felt more routine than alarming. Both companies sit at the center of the artificial intelligence race. Both operate massive cloud businesses. Yet the market delivered a clear verdict. In my view, that verdict centers on one simple idea: financial discipline.
Investors appear willing to reward companies that show they can chase growth without losing control of the balance sheet. They grow impatient when spending looks unconstrained, especially when core operations show any sign of slowing. That is the story unfolding right now.
Microsoft’s Measured Approach to AI Ambitions
Microsoft checked nearly every box that matters to careful investors. The company beat estimates on revenue and earnings per share. Its Azure cloud segment grew 48 percent year over year in constant currency terms, ahead of the consensus expectation around 45 percent. Free cash flow came in at 18.6 billion dollars, down only about one billion from the prior quarter. That kind of stability stands out when peers are reporting deeper cash outflows.
What stood out most was the sense of control. Management demonstrated that it could invest aggressively in artificial intelligence capacity while still keeping capital spending somewhat contained. Earlier in the year the stock had dropped more than 25 percent as concerns mounted about competition and the sustainability of its subscription model. Those worries faded once the company began reporting accelerating cloud growth alongside measured spending guidance. Shares recovered roughly 51 percent from their late-June low through the latest close.
I find it telling that the same leadership team receives consistent praise for pairing vision with restraint. The combination of chief executive and chief financial officer appears to matter a great deal. When both roles work in sync, the narrative and the actual numbers can shift in tandem. Microsoft managed to do exactly that after a rocky start to the year.
What I noticed is that this is a disciplined approach with AI.
That observation captures the essence of the market’s preference. Investors do not mind heavy investment when the company shows it understands the difference between necessary spending and excess.
Alphabet’s Mixed Results and Growing Cash Concerns
Alphabet’s report told a different story. The company missed expectations on several key measures, including overall revenue, operating income, and adjusted earnings per share. Search revenue growth slowed on a sequential basis, raising familiar questions about whether artificial intelligence tools from competitors might eventually chip away at the company’s long-standing advertising engine.
There were bright spots, of course. Google Cloud revenue essentially doubled year over year. The Gemini application is described as the fastest-growing product in company history. Those achievements deserve recognition. Yet they struggled to offset the negatives in the eyes of many investors. Free cash flow moved deeper into negative territory at minus 9.1 billion dollars, worse than the 5.86 billion dollar outflow recorded in the previous quarter. Management also indicated that capital expenditures would rise further in 2027 to support the artificial intelligence buildout.
That combination created unease. When a company spends more than it generates and simultaneously signals even higher future outlays, the market often demands a higher standard of proof that the investment will pay off. In this case, the proof felt incomplete to many observers.
Goofus and Gallant: A Simple Way to Frame the Contrast
Some market commentators have reached for an old analogy from children’s magazines to describe the two companies. Microsoft plays the role of the responsible character who plans carefully and stays within means. Alphabet, in this telling, resembles the less careful counterpart who spends freely without the same visible restraint. The comparison may sound simplistic, yet it captures how investors are currently sorting the two names.
The responsible company keeps free cash flow relatively steady even while expanding capacity. The other sees cash flow turn more negative and projects higher spending ahead. One delivers growth that exceeds expectations while controlling the cost side. The other posts growth in certain segments but misses on broader metrics and faces questions about its core business.
I’ve found that markets often reward predictability almost as much as pure growth. When a leadership team can articulate a clear plan and then deliver numbers that match the plan, confidence builds. When the numbers miss and the spending outlook expands without equally clear near-term returns, confidence erodes quickly.
The Role of Leadership in Shaping Investor Trust
Leadership quality receives heavy emphasis in these discussions for good reason. Microsoft’s recovery this year owed much to the partnership between its chief executive and chief financial officer. Together they adjusted the narrative after early concerns about artificial intelligence competition and potential disruption to the traditional software subscription model. By the time the July quarter results arrived, the company showed both accelerating growth and spending discipline. That combination proved powerful.
Alphabet possesses impressive assets. Custom chips, a leading search franchise, a rapidly expanding cloud business, and a consumer-facing artificial intelligence application all sit under one roof. On paper the company looks well positioned. Execution, however, is what investors judge in real time. Questions have arisen about decisions such as selling specialized processing units to outside customers while simultaneously needing to rent capacity from third parties. Monetization of certain large platforms also draws scrutiny.
One seasoned observer noted that the cloud business effectively rescued the overall report. Without that strength, the stock reaction might have been even more severe. That observation underscores how dependent the current valuation has become on continued cloud momentum and eventual returns from artificial intelligence investments.
Free Cash Flow as the Real Scoreboard
Perhaps the most interesting aspect is how free cash flow has become the quiet scoreboard for this entire sector. Companies can report impressive revenue growth and still face skepticism if the cash generated after capital spending moves in the wrong direction. Microsoft’s relatively stable free cash flow number provided reassurance. Alphabet’s deeper negative reading raised questions about the pace and efficiency of its buildout.
Investors understand that artificial intelligence infrastructure requires large outlays. Data centers, specialized chips, and power capacity do not come cheap. The issue is not the spending itself. The issue is whether management demonstrates a clear sense of prioritization and sequencing. Spending more than necessary, or expanding the outlook further without corresponding near-term visibility, tends to create friction.
- Stable or improving free cash flow builds confidence even during heavy investment periods
- Sequential increases in cash outflow without clear offsets create caution
- Guidance that points to higher future capital spending requires stronger accompanying evidence of returns
- Core business trends still matter because they fund the longer-term bets
These points are not revolutionary. Yet they explain a large part of the divergent reactions this week.
Past Lessons from Holding Through Uncertainty
It is worth remembering that markets have written off strong companies before, only to watch them recover. Alphabet itself provides a recent example. Positions were closed in the past at moments of doubt, only for the stock to rally significantly once certain overhangs lifted. That history suggests caution against permanent dismissal. Smart teams can adjust. Product momentum can surprise. Cost discipline can improve.
At the same time, the current downgrade in conviction around Alphabet reflects genuine concerns about execution rather than a permanent loss of faith. The company retains formidable advantages. The question is whether management will demonstrate the same level of spending control that investors currently reward at Microsoft.
Microsoft, for its part, still faces its own challenges. Competition remains intense. The long-term returns on artificial intelligence spending are not yet fully proven for any player. Yet the market appears willing to grant more patience when the near-term numbers and the spending trajectory both look orderly.
What Disciplined Capital Allocation Looks Like in Practice
Disciplined capital allocation does not mean refusing to invest. It means matching the pace of investment to the visibility of returns and the strength of the underlying cash engine. Microsoft has so far managed to accelerate certain growth lines without dramatically expanding its capital expenditure outlook relative to peers. That restraint, combined with solid results, has supported the recent rebound in the shares.
Alphabet argues, with some justification, that its vertical integration across chips, cloud, and consumer applications positions it uniquely. Custom silicon can lower costs over time. A large search user base provides distribution. Cloud growth is accelerating impressively. Those are real strengths. The market’s current hesitation centers less on the assets and more on the current financial trajectory and the tone of the latest commentary.
In my experience, investors often separate the long-term competitive position from the short-term financial discipline. A company can own the best assets and still face a temporary valuation discount if the spending path looks too open-ended. Closing that gap usually requires either clearer evidence of returns or a more measured spending message.
Core Business Health Still Anchors the Story
Search remains the primary cash generator for Alphabet. Any deceleration, even if temporary or modest, draws attention because it funds so much of the rest of the enterprise. Artificial intelligence tools from other providers create legitimate long-term questions about how users discover information and how advertising dollars flow. Management must continue demonstrating that the core franchise remains resilient while the newer businesses scale.
Microsoft faced its own version of this worry earlier. Concerns about artificial intelligence disrupting traditional software seating models weighed on the stock. The company addressed those concerns by showing both product traction and financial control. The market responded. Alphabet faces a similar test now with its advertising and search businesses.
Cloud growth helps both companies, yet it does not fully erase questions about the legacy engines. Balanced progress across both the old and the new tends to produce the strongest investor confidence.
Looking Ahead: Room for Recovery and Further Gains
Neither story is finished. Microsoft still has room to run if it continues delivering growth alongside discipline. Some observers see potential for the shares to move meaningfully higher over time if the current trajectory holds. Alphabet retains the capacity to regain favor. Previous periods of skepticism have been followed by strong recoveries once execution improved or external overhangs cleared.
The key variable remains the same: evidence that capital is being deployed with clear priorities and measurable progress. Free cash flow trends will continue to matter. Guidance around future capital spending will be scrutinized. Progress in monetizing artificial intelligence products and sustaining core growth will influence the narrative.
I’ve watched enough earnings seasons to know that markets can shift their assessment quickly when the numbers and the messaging improve. Companies that look undisciplined in one quarter can restore confidence in the next if they tighten the spending plan and deliver sequential improvement. The reverse is also true. Consistent discipline tends to compound over time into higher valuation multiples.
Practical Takeaways for Evaluating Tech Spend
When assessing large technology companies in the middle of heavy infrastructure cycles, a few practical filters help. First, examine the trajectory of free cash flow rather than focusing solely on revenue growth. Second, listen carefully to how management describes the relationship between current spending and expected returns. Third, watch for consistency between the growth story and the capital expenditure outlook. Fourth, evaluate whether the core cash-generating businesses remain healthy enough to support the longer-term bets.
- Track free cash flow trends across several quarters rather than isolated numbers
- Compare capital spending guidance against peer behavior and historical patterns
- Assess whether growth acceleration in high-priority segments is accompanied by broader operational control
- Note the tone and specificity of management commentary around prioritization
- Consider the track record of the leadership team in adjusting course when needed
These filters do not guarantee perfect timing. They do help separate companies that are investing with clear intent from those that appear to be spending without the same visible constraints.
Why the Market Prefers Predictable Progress
Markets rarely punish ambition itself. They do punish ambiguity around the cost of that ambition. Microsoft has so far kept the cost side relatively predictable while delivering growth that exceeded expectations. Alphabet’s latest report introduced more questions on both the growth quality of the core business and the trajectory of cash flow. That combination produced the sharp reaction.
The artificial intelligence race will continue for years. Capacity will keep expanding. Competitive positions will shift. Through it all, the companies that pair bold investment with visible financial discipline are likely to enjoy greater investor patience. Those that allow spending to appear open-ended while core metrics soften will face higher hurdles.
That dynamic explains the divergent paths of these two stocks this week. It also offers a useful lens for evaluating future reports across the sector. Growth remains essential. Control over the spending that produces that growth may matter even more in the current environment.
The coming quarters will reveal whether Alphabet can tighten its approach and restore the kind of confidence Microsoft currently enjoys. History suggests that capable teams can make those adjustments. Until clearer evidence arrives, the market is likely to continue distinguishing between the two based on the simple but powerful idea of financial discipline.
In the end, investors are not asking companies to stop investing in the future. They are asking them to invest with intention, measure progress carefully, and keep the balance sheet from becoming an afterthought. Microsoft has met that standard more convincingly in recent reports. Alphabet still has work to do on that front. The stock reactions this week simply made that distinction impossible to ignore.